How Western Union Actually Prices Your Transfer
Most people walk into a Western Union transaction thinking they know what they're paying. They don't. The fees aren't where the margin lives. The margin lives in the exchange rate. I've watched people get genuinely confused when they realized the fee they saw online was half a dollar but they ended up receiving forty dollars less than the mid-market rate would have given them. Here is how the system works under the hood, the way nobody in the branch or on the FAQ page explains it to you.
Western Union Currency Converter Rates The Essential Guide To Global Transfer Costs
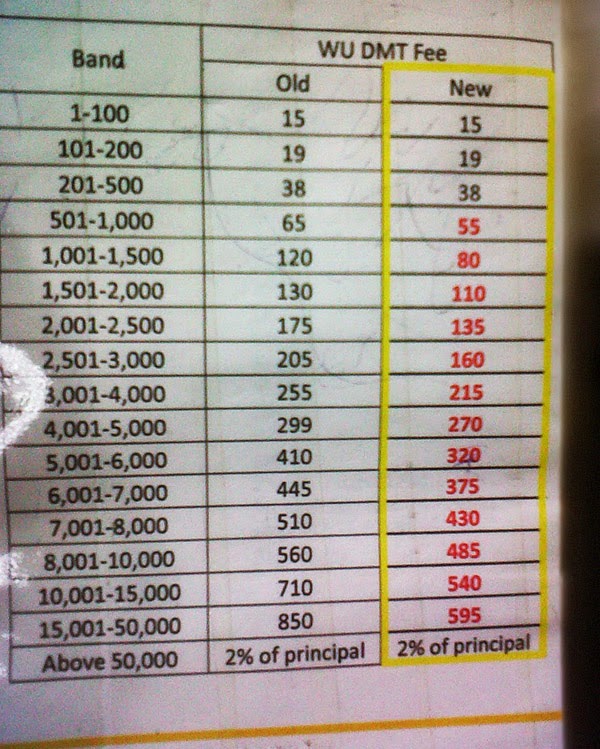
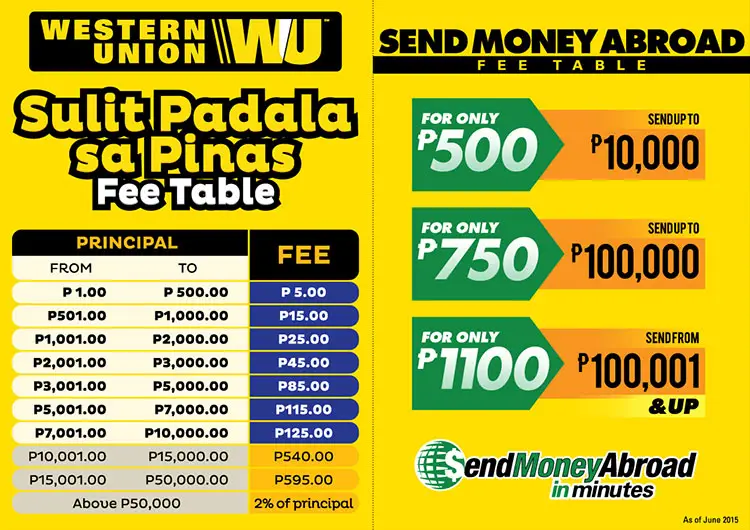
Western Union uses a proprietary markup on the interbank exchange rate. When you look at their converter, the rate shown is not the spot rate from Bloomberg or Reuters. It is their own internal rate, which includes a spread that typically ranges from two to five percent depending on the currency pair, the country you are sending from, the country you are sending to, and how much money you are moving. The fee structure is transparent on their site. You pick the amount, pick the countries, and it shows you the fee and the exchange rate side by side. That part is honest. What it does not show you clearly is how far that exchange rate deviates from the actual market rate. The fee might be zero for a particular transaction because they are compensating entirely through the spread. A zero-fee transfer is almost never the cheaper option. I learned this the hard way in 2019 when I was helping my sister send money from the UK to Nigeria. The converter showed a nine-pound fee. Seemed steep. I paused, looked up the mid-market rate for GBP to NGN on XE, and saw that Western Union's rate was roughly four percent worse than the real rate. On a five hundred pound transfer, that was about twenty pounds hidden in the spread. If I had just accepted the nine-pound fee as the total cost, I would have been wrong by more than double. The workaround I used was calculating the total cost myself: I took the mid-market rate, applied it to her amount, and compared it to what she would actually receive through Western Union. That gave me the real cost, which was around twenty-nine pounds total instead of nine. We switched to a specialist remittance provider for that corridor and cut the total cost down to roughly fifteen pounds.
What Drives The Rate Up Or Down
The spread is not fixed. It moves based on a handful of variables that are opaque to the sender. Currency pair liquidity matters a lot. USD to EUR will have a tighter spread than USD to ETB or USD to PKR. The less liquid the destination currency, the wider the spread, and the more you lose on every transfer. Western Union builds this into their pricing automatically but never calls it out explicitly. Delivery method changes things too. Cash pickup often carries a different fee structure than bank deposit or mobile wallet credit. Sometimes the mobile wallet route has a better rate but a higher fee. Sometimes it is the opposite. The app will show you both options but the comparison is not framed in a way that highlights the true cost difference.
Get the Full Details
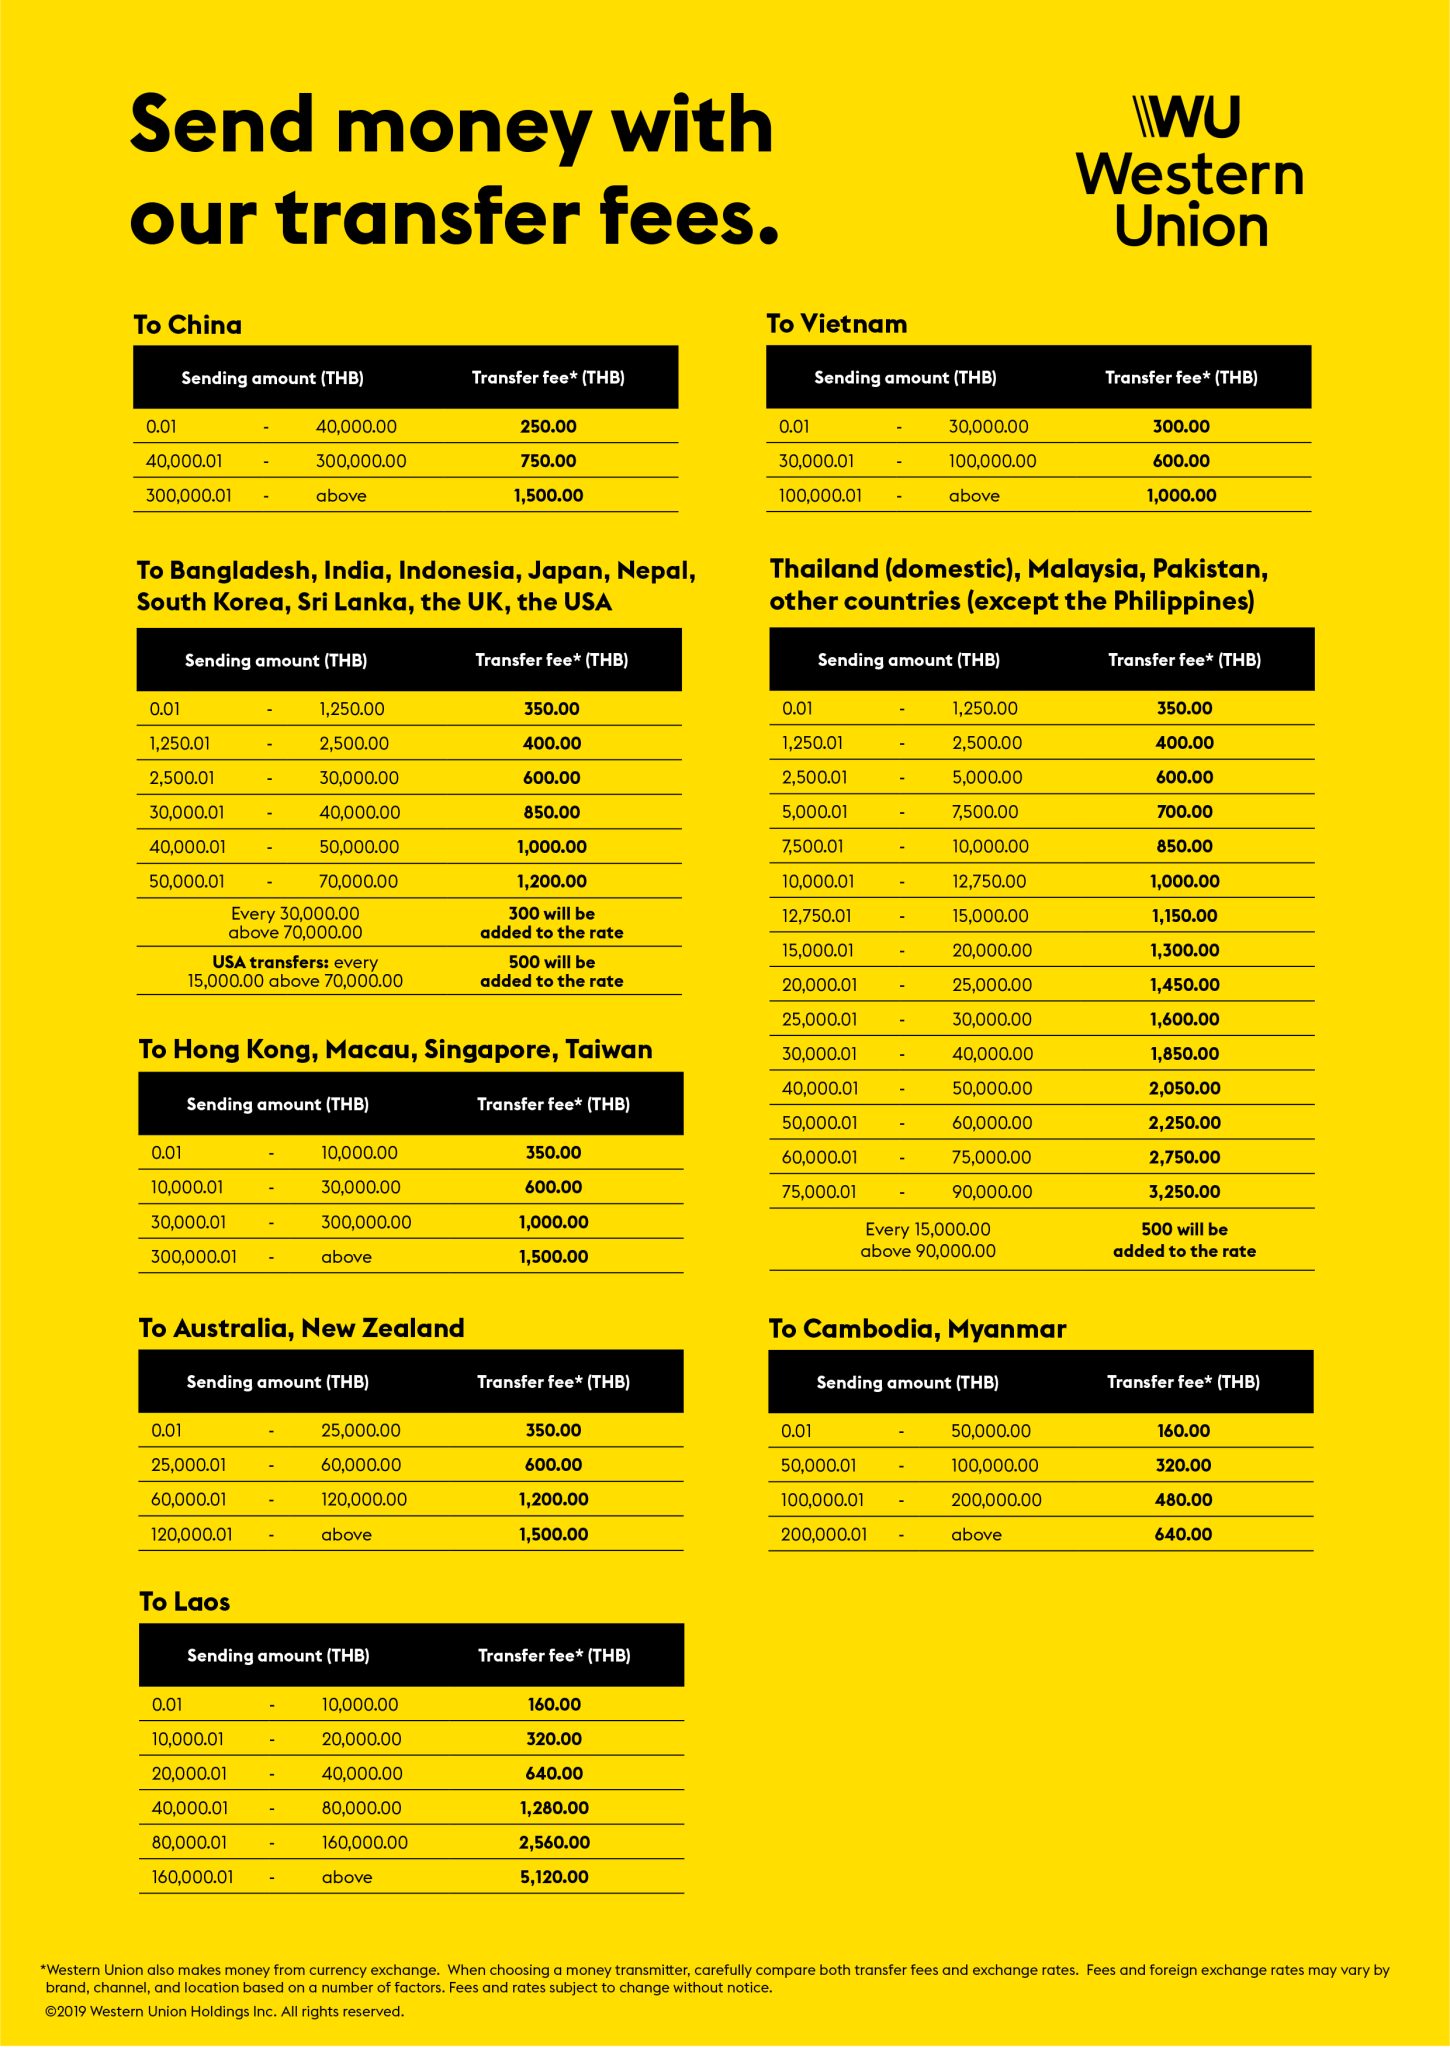
Volume discounts exist but they are not advertised. If you are sending more than a thousand dollars per month consistently, your rate improves. You do not get a notification about this. You have to call customer service or talk to a representative at a branch and ask for it. Most people never do. I have seen repeat senders lose hundreds of dollars a year just from not asking.
When Western Union Makes Sense And When It Does Not
Western Union works well for urgent transfers where speed matters more than cost. Cash pickup in minutes at a physical agent location is still unmatched for reliability in certain corridors. If someone needs money today and the destination is a rural area with no bank access, Western Union is often the only thing that works. For planned transfers where cost matters, it is usually the wrong choice. Wise, PaySend, and a few other specialist remittance platforms consistently beat Western Union on the exchange rate for most corridors. The difference is not marginal. It is usually enough to justify setting up an account with an alternative, even accounting for the friction of onboarding. There are also edge cases where Western Union is the only option. Certain sanctioned countries, certain currency controls, and certain high-risk corridors simply do not have alternative providers willing to touch them. In those cases you pay the premium because there is no market competing against them. That is a structural problem, not a pricing quirk you can optimize around.
How To Evaluate Any Transfer Before You Commit
Do not trust the fee number alone. Do not trust the exchange rate number alone. You need both numbers together to understand the real cost. Open a mid-market rate reference. XE, OANDA, or even Google's currency converter all show the real rate. Take your transfer amount and multiply it by the mid-market rate. That is what the recipient should get if there were zero markup. Now look at what Western Union says they will deliver. The difference between those two numbers is your true cost. Add the fee to it if the fee is listed separately, or subtract the fee from the delivered amount if the rate already includes it. Either way, the math reveals the actual percentage you are paying. I run this calculation myself before every transfer now. It takes about thirty seconds once you know where to look. I have caught myself about to commit to deals where the true cost was eight percent instead of the two percent I thought I was getting. The converter shows a green checkmark and a seemingly reasonable number. The fine print hides the spread in a section most people never scroll past.
Common Mistakes People Make
The biggest mistake is assuming that a promotional rate or a discounted fee day means you got a good deal. Promotions usually apply only to the fee. The exchange rate stays the same, which means the promotion is mostly cosmetic. You save five dollars on the fee and lose thirty dollars on the rate. The net result is worse than the standard rate on a normal day. Another mistake is locking in a rate through the app and then walking into a branch to complete the transfer. The rate you see online is valid for a short window, usually fifteen to thirty minutes. Once it expires, you are back to the current rate. Branch staff will sometimes process a transaction at the counter rate rather than the quoted rate if you do not explicitly insist on the quote. It happens more often than you would think. A third mistake is ignoring the recipient-side costs. Some corridors charge the recipient a fee when they pick up cash. Western Union sometimes offers receiver-pays models where the sender pays nothing but the exchange rate is significantly worse. The recipient ends up paying more through the rate, and the sender has no idea because the app frames it as a free transfer.
What To Watch For In Your Receipt
After a transfer completes, the confirmation email or receipt includes the exchange rate used. Most people delete that email without reading it. The rate on the receipt is the rate you actually got. Compare it to the mid-market rate on the same day. If the gap is wider than three percent on a major currency pair, something is off. If it is wider than that on a minor currency pair, that might just be normal. Every corridor has different norms. I keep a spreadsheet of my transfers. Not because I am obsessive. Because after six months of data, I could see which corridors were consistently bad and which were acceptable. It took me about two weeks to set up the spreadsheet and about a minute per entry to log. The long-term value was obvious once I had enough data to see patterns. Without that data, every transfer feels like a guess. Western Union will continue to be available for transfers for the foreseeable future. The question is whether it is the right tool for your specific corridor and timeline. Knowing the true cost instead of the advertised cost is the difference between feeling like you made a reasonable decision and realizing later that you overpaid by a noticeable margin. The math is straightforward. The opacity is intentional. Your job is to close the gap between what you are told and what you actually pay.