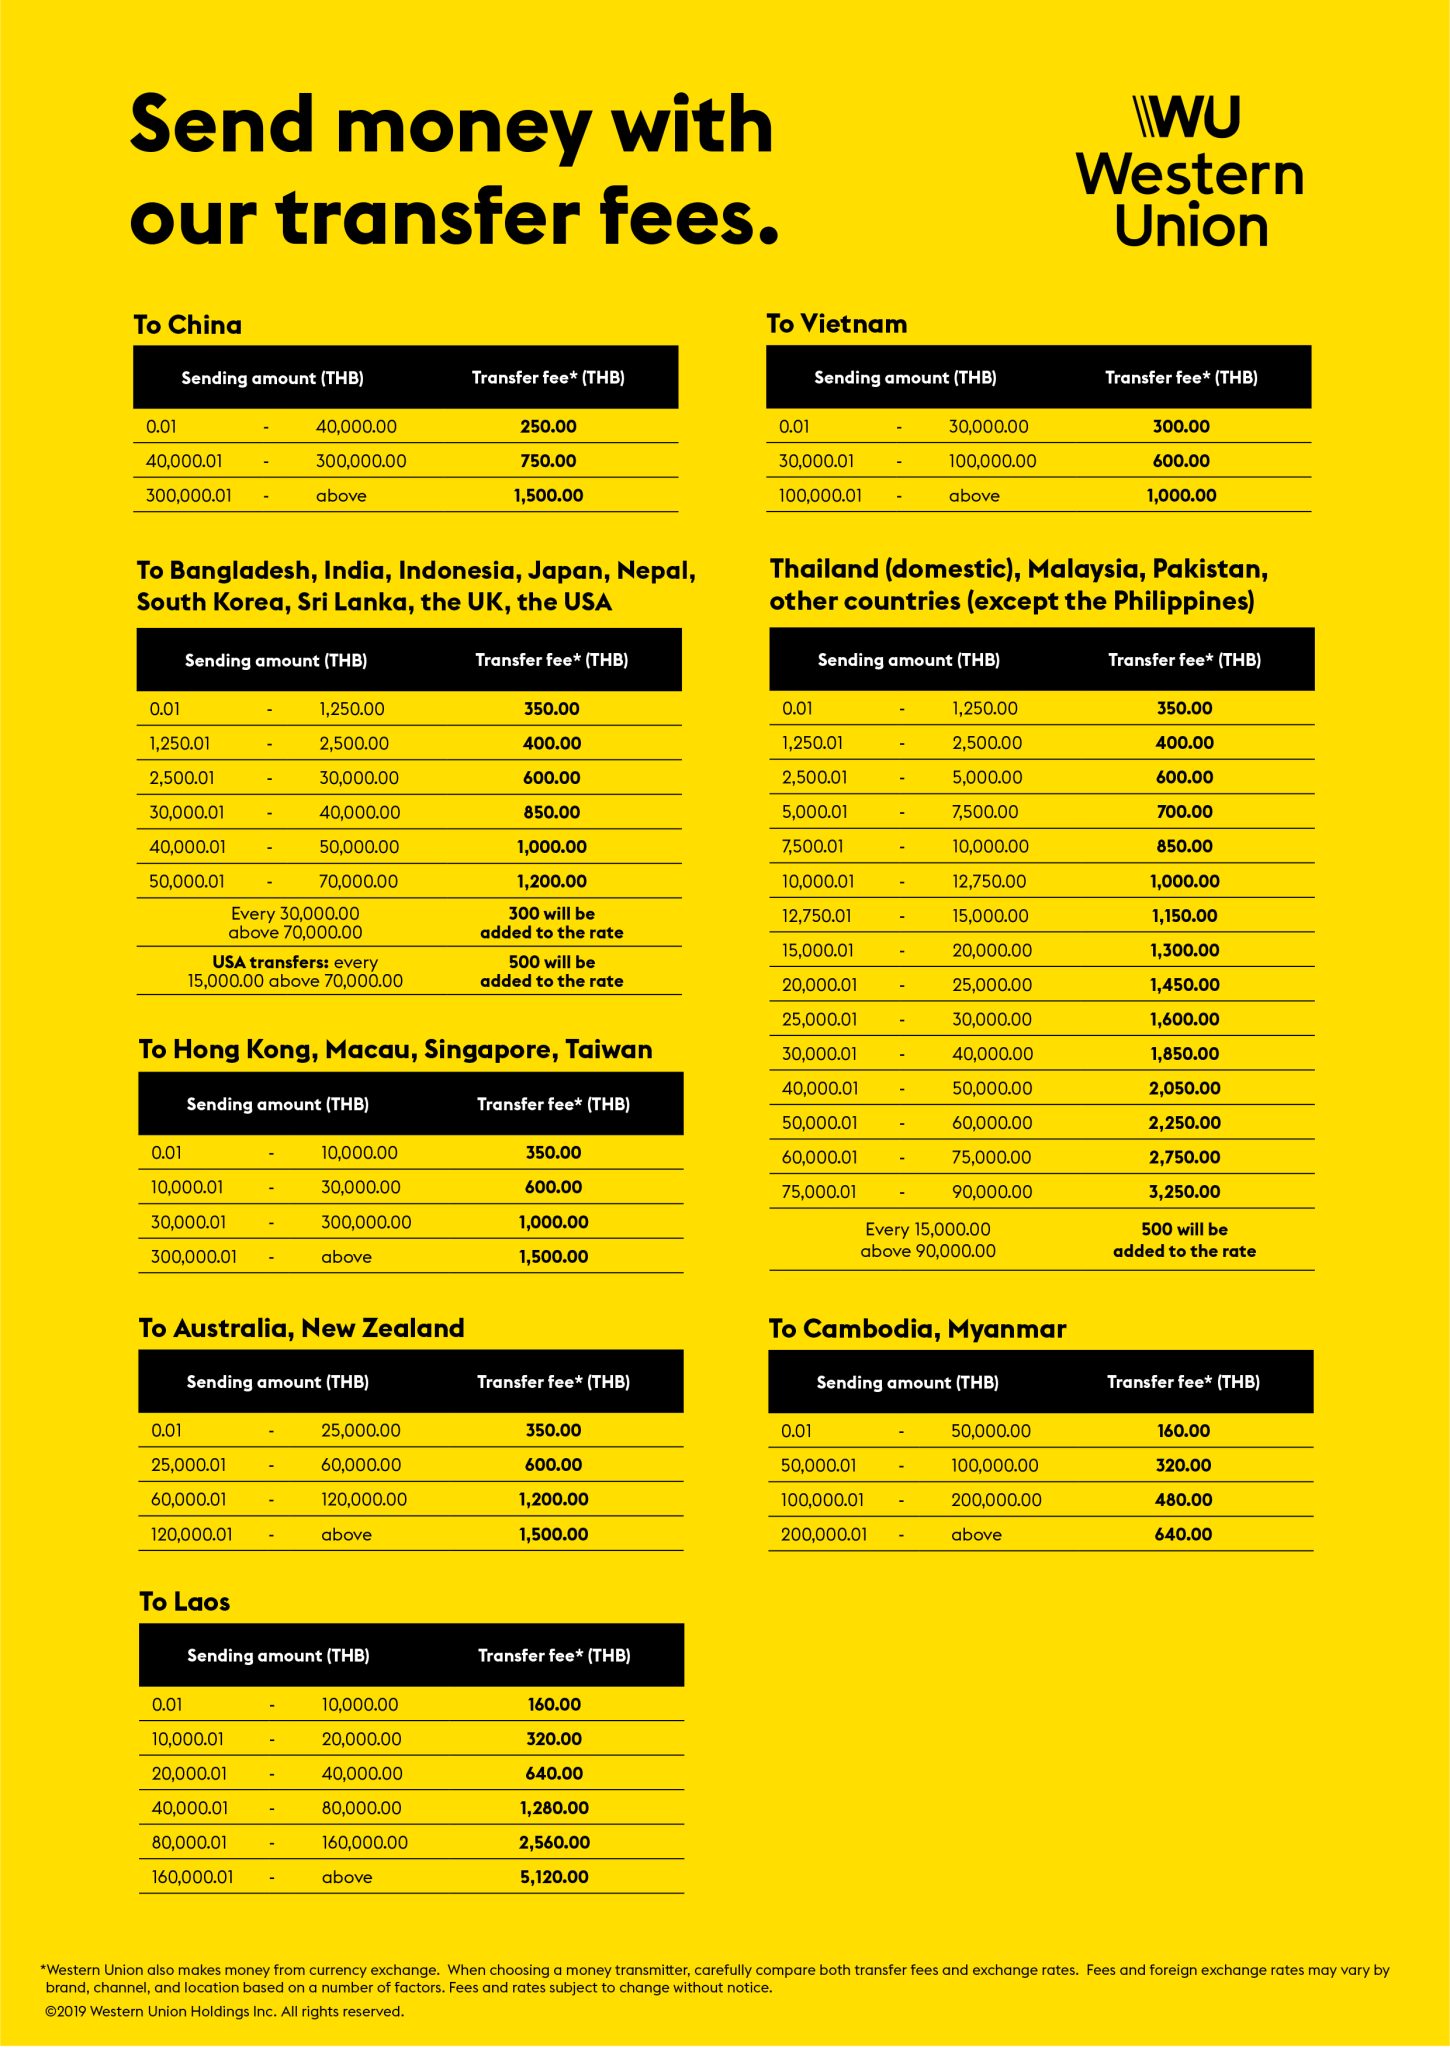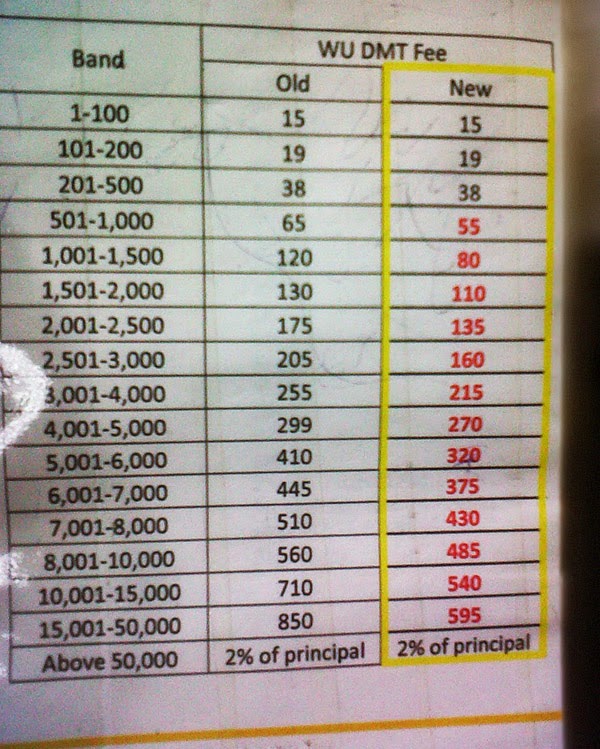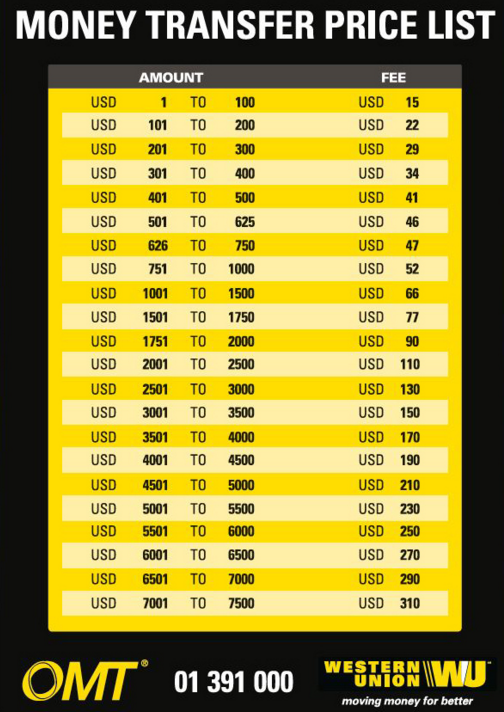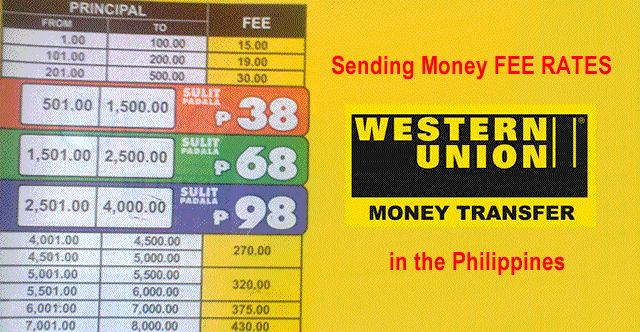
Western Union Rates and Fees Are Not What Most People Think
The exchange rate you see on the Western Union website is rarely the rate you actually get. There is a spread built into every transfer, and it can vary depending on how much you send, where you send it, and whether you are using their app or walking into a physical agent location. I learned this the hard way a few years ago when I sent $500 to the Philippines and the recipient reported getting about 8 percent less pesos than the mid-market rate at the time. The gap wasn't a mistake. It was the margin. Western Union publishes competitive-looking rates online to attract clicks, but the final rate is locked in at payment. That means the rate shown when you first open the converter is a snapshot, not a guarantee. If you check back five minutes later after making a small change to the amount, the rate might shift slightly. This is normal market movement, not manipulation, but most people interpret it as a bad sign when it is just volatility.
Western Union Currency Converter Rates Easy Ways To Save Money On Every Transfer
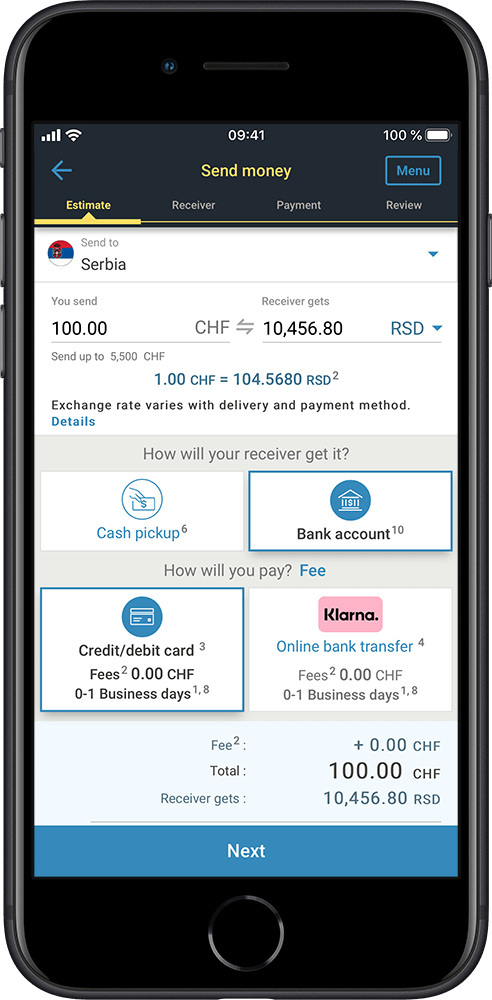
Here is how I actually minimize what I pay when using Western Union, not some theoretical advice from a comparison site. Always check the total amount the receiver gets before confirming. The converter shows a rate and a fee separately, but the fee is sometimes baked into a worse exchange rate. I always calculate what matters: receiver amount divided by your send amount equals your effective rate. If that effective rate is worse than whatXE.com or OANDA shows for the same currency pair, you are overpaying. I do this every single time now. Choose bank deposit over cash pickup when possible. Bank delivery typically carries lower fees for the same send amount compared to cash pickup. I switched to bank deposits for my regular remittances and dropped my average cost per transfer by roughly 30 to 40 dollars on a five hundred dollar send. The tradeoff is that the recipient needs a bank account and it takes one to two business days instead of minutes. For family support transfers where speed isn't critical, this switch alone pays for itself.
Promotional rates only work if you qualify. Western Union occasionally offers zero fee or bonus rate promos, usually capped at a certain send amount. The promo is real, but the fine print restricts it to new customers or first-time users of a specific product tier. I wasted time trying to stack a promo code on a repeat transfer last year. It didn't apply. The system rejected it outright. Promo rates are worth checking if you are doing a one-off transfer, but they are not a recurring discount strategy. Avoid airport and convenience store pickups. Agent locations near travel hubs charge higher fees because they cater to urgent transfers from people who need cash immediately. I compared fees between a Western Union inside a grocery store and one across town near a bus terminal for an identical send. The difference was 12 dollars on a three hundred dollar transfer. Over a year of monthly sends, that adds up to meaningful money I no longer throw away. Use the app and schedule ahead. The mobile app sometimes shows different rates than the website because it is pushing customers toward digital channels. I noticed this discrepancy on a euro to dollar transfer last spring. The app rate was about 0.4 percent better than the web version for the same amount. Scheduling the transfer during off-peak hours also seems to trigger slightly better rates, though I cannot explain why. Market liquidity varies, and maybe the internal pricing engine adjusts accordingly.
Get the Full Details
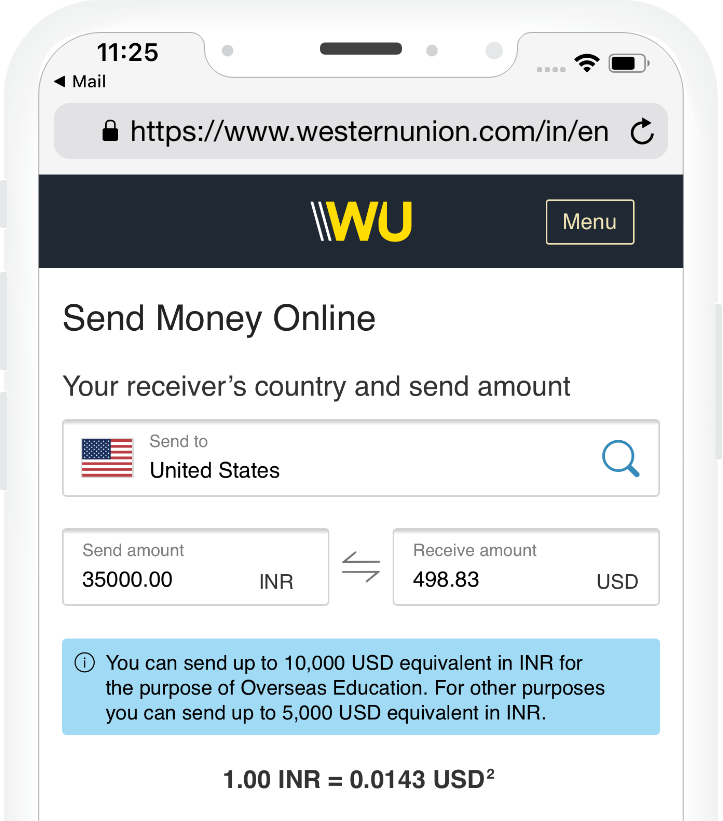
When Western Union Is the Wrong Tool
Western Union works well for urgent cash pickups and destinations where banking infrastructure is weak. It does not work well for large recurring transfers above two thousand dollars, or for currencies with high volatility like Turkish lira or Argentine peso. In those cases, the spread can widen to 5 to 8 percent during turbulent periods, and no amount of fee comparison fixes that. For steady monthly transfers to stable currencies like Mexican peso or Indian rupee, I recommend checking alternatives like Wise or Remitly. These services publish mid-market rates with a transparent markup and often come out cheaper for amounts above four hundred dollars. I run a quick check on both sides before committing. If Western Union is under ten dollars cheaper including the rate difference, I stick with them. Otherwise, I move the transfer.
One Edge Case That Cost Me Money
Once I sent money to Nigeria using Western Union with bank deposit. The rate looked fine. The fee looked reasonable. The receiver waited three business days and never got the funds. I called support and discovered the bank had rejected the deposit because the account name did not match the sender name exactly. Western Union had merged two parts of the recipient name into one string during data entry, and the bank flagged it as a mismatch. No money lost, but the transfer stalled for another week while we sorted out the paperwork. The workaround was simple: always double check the recipient name spelling character by character before hitting confirm, and prefer names that match official ID documents exactly. I have not made that mistake since. Bottom line: treat every Western Union quote as a starting point, not a final answer. Compare the effective rate, avoid high fee locations, use digital channels, and move to an alternative service when the math clearly favors it. Saving money on transfers is not about finding a hidden hack. It is about paying attention to what actually gets delivered versus what the converter displays.