The Real Exchange Rate on Western Union Is Not What You Think
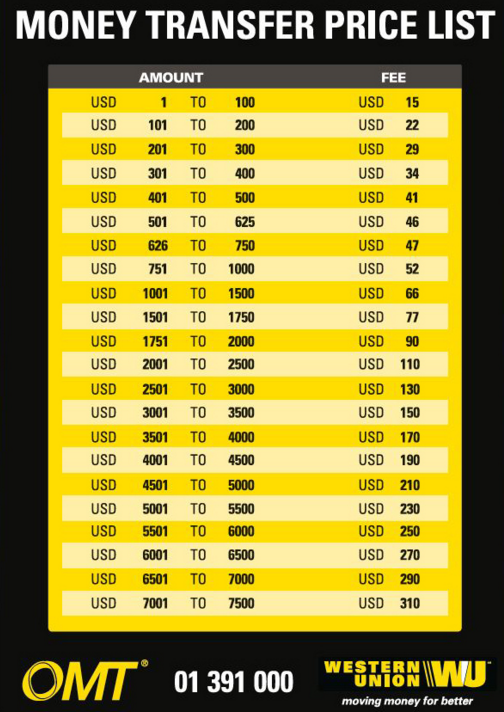
I have sent money through Western Union more times than I can count, mostly for family abroad and a few business payments that needed to arrive fast. The first thing I learned the hard way is that the rate displayed on their converter is not the rate they actually use once you hit send. The converter pulls from interbank wholesale rates and then adds their markup on top, which is rarely shown as a separate line item. It is hidden inside the exchange rate itself, usually between 3 and 7 percent depending on the corridor. The report most people circulate online breaks down exactly how that markup works across different currency pairs and countries. It is not a secret, but it is buried deep enough that the average sender never bothers looking. I went through it carefully because I needed a clearer picture of where the money was going on a Mexico to US dollar corridor I use regularly. The numbers were predictable but not pleasant. For a $500 transfer, the effective rate difference between the mid-market rate and Western Union's posted rate worked out to about $21 to $35 in hidden costs, on top of the flat transaction fee that shows up at checkout. Here is how I approach checking rates now before I commit to any send. First, I pull the mid-market rate from OANDA or XE, not from Google. Google shows a blended rate that averages buy and sell spreads, which makes it look better than it actually is. Then I enter the same amount and currency pair into Western Union's converter and note the rate they give me. The gap between those two numbers is your real cost, excluding the transaction fee. I repeat this for at least three other providers in the same corridor, usually Wise, Remitly, and sometimes WorldRemit, depending on availability. That five minute comparison routine has saved me enough over the years that it is automatic now.
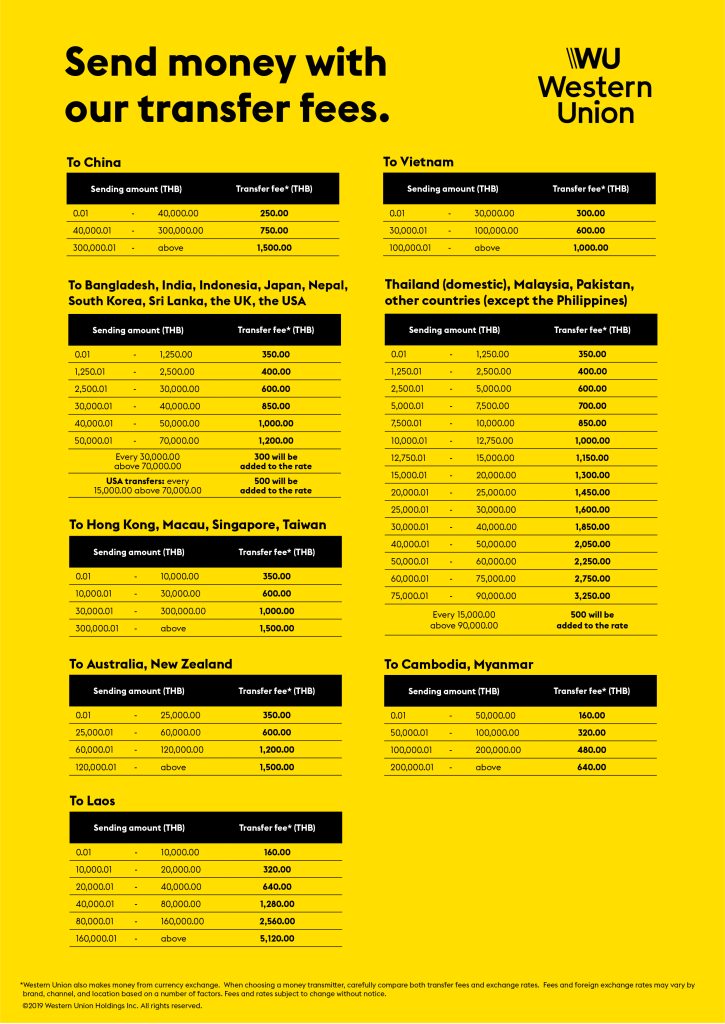
The trick nobody talks about is that the converter rate changes by transaction type. Cash pickup rates are typically worse than bank deposit rates for the same currency pair. I found this out when I sent money to the Philippines and the online quote looked reasonable until I selected cash pickup instead of bank transfer, at which point the rate shifted by nearly a full percent. The same thing happens with home delivery versus agent location pickup in some markets. The interface makes it easy to miss the toggle that controls this, so I always verify the payout method before I treat the displayed rate as final. Another detail that matters but gets glossed over is timing. Western Union updates rates in real time during business hours in most regions, but during off hours the quoted rate can lock in at a worse level if the market moves while you are confirming payment. I learned this after a transfer to Kenya on a Friday evening where the rate I saw at 6 PM was noticeably different from the one executed Sunday morning when the funds cleared. The converter does not warn you about this explicitly, so if the amount is large and the timing is flexible, waiting for Monday morning liquidity usually produces a tighter spread. There are also corridor-specific quirks. Sending to Vietnam from the US through Western Union involves a VND rate that includes a significantly wider spread than EUR or GBP corridors. This is partly regulatory and partly because Western Union operates with fewer bank partners in that market, which reduces competition on the rate side. If you send to smaller economies regularly, the converter will still show a number, but that number will be structurally worse than what you would get on major pairs. I keep a spreadsheet tracking effective rates by corridor, and it consistently shows a 1 to 3 percent disadvantage on secondary currencies compared to primary ones.
If you are sending small amounts, under $200, the difference between Western Union and cheaper alternatives shrinks considerably. The fixed fees dominate the math at low values, so a 4 percent markup on $100 is only $4, which may not justify the time spent comparing options. But above $1,000, the markup becomes the primary cost driver, and Western Union is frequently the most expensive option in the corridor unless you qualify for a discount through a corporate account or a promotional rate event, which are rare and usually short lived. I also want to mention a limitation that most guides ignore: Western Union's converter does not reflect the actual amount the recipient gets in all cases. Local taxes, intermediary bank fees, and agent commission deductions can reduce the final payout independently of the exchange rate. I encountered this when sending to Ecuador, where a small local processing charge was deducted at the agent counter and the recipient received less than the converter promised. The converter shows a gross figure, not a net delivered figure, and there is no reliable way to predict the net amount without checking local fee structures for that specific payout city. The practical takeaway is straightforward. Use the Western Union Currency Converter Rates Before You Send Read This Eye Opening Report as a baseline, not as the final answer. Run the mid-market comparison, check payout method effects, avoid off hours for large transfers, and factor in corridor-specific spreads. If you do that, you will almost always find a better option for amounts above $500, and even for smaller amounts the process takes less than ten minutes and removes the guesswork.
Get the Full Details