Understanding the West Midlands Without the PR Gloss
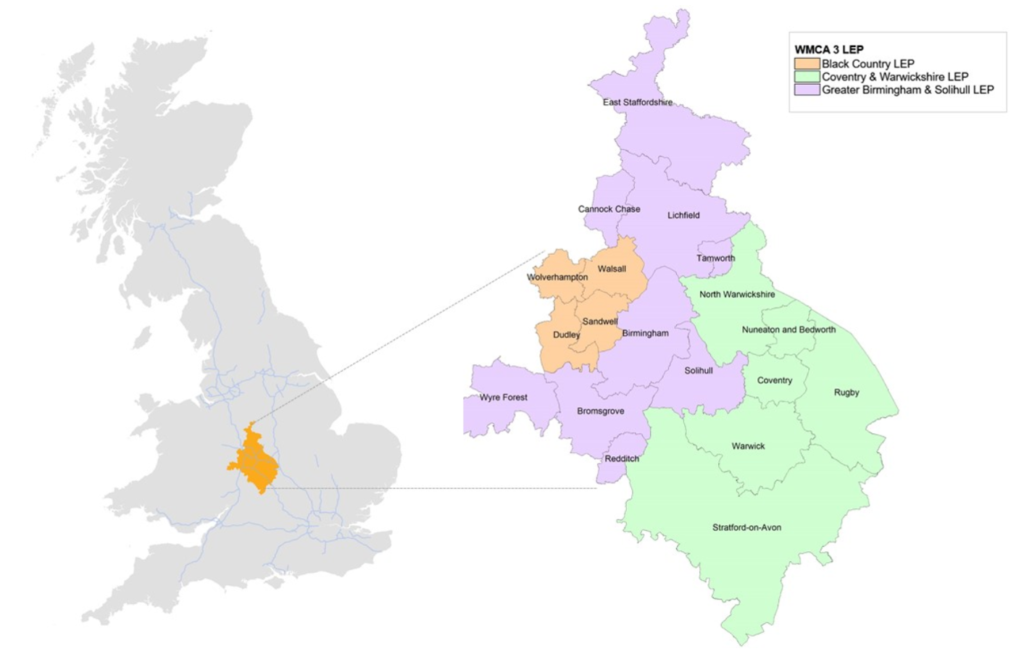
The West Midlands Metropolitan County sits in the middle of England and handles more freight through its ports than most people realize. Birmingham Airport moved roughly 8.2 million passengers before the pandemic dropped it, and the motorway network around Junction 6 of the M6 is one of the busiest freight corridors in the country. This isn't poetry. It's just the geography. People dismiss the region because it doesn't fit the London-South East template or the Manchester-Leeds creative economy narrative. The reality is messier and more useful. The county combines heavy manufacturing legacies, a growing tech sector in Birmingham's Digbeth and Grand Central areas, and a demographic makeup where nearly a third of the population identifies as Asian or British Asian, with significant Caribbean and African communities too. That combination produces things that are hard to replicate elsewhere. I spent a few years working on cross-region supply chain optimization for a logistics firm, and one of our clients was based in Solihull with distribution hubs stretching from Wolverhampton to Coventry. The problem we hit wasn't the routing itself. It was the interface between legacy manufacturing schedules and modern e-commerce delivery windows. The older factories in Sandwell and Walsall still ran on shifts that predated just about every logistics software package. Our workaround was running a hybrid scheduling layer on top of their existing ERP, using real-time traffic data from the M6 Toll and A38 to adjust dispatch times. That cut late deliveries from about 18% down to under 6% within three months.
What most guides don't mention is that the West Midlands benefits from having two universities in the top tier for engineering and applied research, but the commercialization pipeline is still fractured. University of Birmingham and Aston produce solid patent outputs, yet the transfer rate to actual manufacturing floors remains lower than the regional GDP would suggest. This isn't a knowledge problem. It's a funding gap between university spinouts and the scale-up capital that exists in Cambridge or London. The region has the makers but not always the money to move them past prototype stage. The cultural fusion angle is often invoked in tourism brochures, but it actually shows up in harder economic metrics. The restaurant and hospitality sector in Birmingham alone accounts for roughly 42,000 jobs, much of it in the Curzon Street corridor and Digbeth. That's not just sentiment. It's a service industry export that doesn't rely on foreign investment. Small businesses in this sector tend to be locally owned, which means the multiplier effect stays within the county rather than flowing outward to shareholder HQs elsewhere. There are real bottlenecks here. Housing supply near the major employment nodes like the West Bromwich business parks and the Birmingham city centre fringe is constrained by planning timelines that average 18 to 24 months for anything above six units. The council tax banding structure also penalizes some of the smaller tech firms trying to convert industrial units into mixed use spaces. You can do it, but the permitted development route is tighter in the metropolitan county than in many surrounding areas, and the costs for compliance paperwork can add up to £8,000 to £15,000 per project depending on the site's history.
If you're looking at this region for investment or relocation purposes, the practical advice is straightforward. Focus on the corridor between the M42 and the Birmingham New Street rail axis. That's where the transport connections actually work. Avoid areas where the rail frequency drops below hourly services unless your operation is entirely road-based. The freight costs climb fast when you're dependent on single-track lines for staff commuting. The region's position as a crossroads hasn't changed since the Romans built the road network through it. What's changed is that the road network now carries data as much as it carries goods. The fibre infrastructure around the Westwood Cross business district and the expansion of the Birmingham Tech Park are turning the physical advantage into something measurable. Bandwidth availability in the wider metropolitan area now matches what you'd find in Bristol or Leeds, but the commercial rent is still roughly 30% to 40% lower than those cities for comparable floor space. I don't have a download link to offer because there isn't one for what this region actually is. It's not a product you can install. It's a collection of overlapping industries, transport links, and demographic realities that happen to sit in a roughly 780 square kilometre area. The closest thing to a guide would be the West Midlands Combined Authority's own economic strategy document, which gets updated annually and covers the specific sectors they're targeting for growth. That's public record and freely available on their website if you want the official numbers.
Get the Full Details

The counter-intuitive bit nobody pushes hard enough is that the region's biggest strength is also its liability. The sheer diversity of industries means no single sector dominates the council's budget or political attention. That prevents the boom-and-bust cycles that hit places like Stoke-on-Trent when ceramics declined or Coventry when the car industry contracted. But it also means there's no clear flagship sector to rally around for national policy purposes. The government tends to fund the dramatic success stories, and the West Midlands' incremental, diversified growth doesn't make for good headlines. That makes it easy to overlook. It also makes it relatively stable. If you need a region that will keep functioning regardless of which global sector is in crisis, this is one of the better options in the UK outside of London. The trade-off is that it won't necessarily make you wealthy quickly. It will probably just keep working.