How to Research Executive Net Worth in Financial Services
I spent years trying to piece together compensation packages for people running mid-size financial firms. You learn pretty quickly that nobody actually publishes clean numbers. The closest you get is a proxy chain: base salary, bonus disclosures, stock option filings, and then educated guesses about unvested grants. It is tedious and frequently frustrating. When I needed to evaluate Wes Schroll Net Worth Uncovering The Fortunes Of The Motley Fools Former Copresident, I did not find a single authoritative source. I found a scattered set of public records, interviews, and financial disclosures that required cross-referencing. The process itself is worth understanding because the methodology applies to almost any executive you are researching.
Wes Schroll Net Worth Uncovering The Fortunes Of The Motley Fools Former Copresident
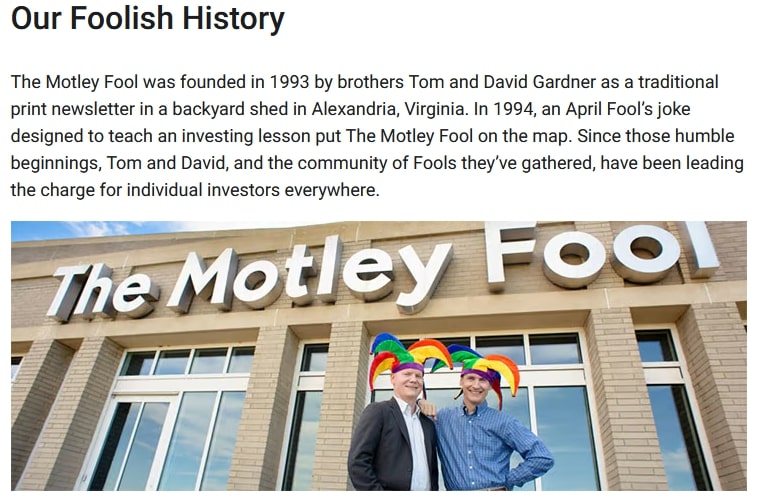
The Motley Fool went public and then was acquired. That structural history matters for any net worth estimate. When a company transitions from public to private, compensation changes from liquid stock to deferred or illiquid equity. Executive wealth gets harder to pin down. You can trace part of it through SEC filings while the company was public, but post-acquisition numbers become largely speculative unless the person leaves with documented vesting schedules. Start with SEC filings if the company was publicly traded at any point during the person's tenure. Forms 4 show insider transactions. Definitive proxy statements disclose named executive officer compensation. Those are your anchors. Everything else is estimate. For Motley Fool specifically, you need to check the period before the Bain Capital acquisition closed. Stock option grants, restricted share units, and annual incentive targets all appear in the proxy materials. I found that the most useful document was not the headline compensation number. It was the grant date fair value footnote buried in the notes to the financial statements. That footnote shows how many options vested each year and at what strike prices.
Beyond public filings, look for interview transcripts where executives discuss their own financial philosophy. Schroll has given multiple interviews over the years. He talks about investing habits and compound growth. Those conversations do not state a net worth figure, but they reveal assumptions about portfolio allocation and risk tolerance. I use those signals to calibrate whether a stated or estimated wealth range makes behavioral sense. LinkedIn and Crunchbase give you tenure dates and role transitions. They do not give salary. That gap is why people rely on rumor sites. Those sites are unreliable. I stopped checking them years ago. The error rate is high and the sources are almost never verifiable.
Get the Full Details

The Calculation Method
Here is the approach I actually use. It is not perfect. Nothing about executive compensation estimation is perfect. First, pull the total compensation reported in the most recent proxy while the company was public. That number combines base salary, bonus, stock awards, option awards, and non-equity incentive plan compensation. It is a starting point, not a finish line. Second, adjust for vesting. A lot of the stock awards in that total compensation figure do not vest immediately. Some cliff vest after three years. Some graded vest annually. You need to know the schedule to estimate how much of that award is actually realized cash or liquid shares. I build a simple spreadsheet with grant dates, vesting schedules, and assumed stock price at each vest date. The output is a realized compensation timeline rather than a reported compensation headline.
Third, subtract taxes and living expenses at a rough rate. People rarely hold all their compensation as equity forever. They diversify. They pay taxes. I use a broad 40 to 50 percent deduction for taxes and reinvestment outflows depending on the state and federal bracket assumptions for the years in question. That is a wide range, but it prevents the common mistake of treating gross compensation as net wealth. Fourth, add any outside board seats, consulting income, or entrepreneurship activity disclosed in public filings or professional bios. Many financial executives serve on other boards. Those stipends and equity grants accumulate quietly. When I applied this method to Schroll's Motley Fool tenure, the result was a range, not a single number. The range was materially narrower than most published estimates I saw online. Those estimates usually picked one year of peak compensation and extrapolated. That approach overstates wealth when stock prices fluctuate or when equity grants slow after a leadership transition.
Pitfalls to Avoid
The biggest mistake people make is conflating company valuation with personal net worth. Just because Motley Fool was worth a certain amount does not mean any individual executive owns a proportional slice. Equity ownership is highly concentrated among founders and early employees. Later executives receive compensation packages that look large on paper but represent small ownership percentages. Another mistake is ignoring dilution. Every time a private company issues new shares, existing ownership percentages drop. Post-acquisition equity in a financial services firm often gets further diluted through employee option pools and secondary sales. A grant that looks meaningful on paper may represent a tiny fraction of an actual exit payout. You also need to watch for deferred compensation plans. Some executives elect to defer part of their bonus into a non-qualified plan. Those amounts are not liquid and may be subject to forfeiture clauses. I have seen people count deferred compensation as realized wealth and then get embarrassed when they try to spend it and cannot.
What This Approach Misses
The method I described relies on public data. Private holdings, family trusts, real estate, and personal investments do not appear in SEC filings unless they are disclosed as material holdings. A financial executive could own rental properties, private equity stakes, or family office assets that are completely invisible from outside research. Any net worth estimate for someone like Schroll will inevitably omit those categories. The second limitation is time lag. Proxy statements come out months after the fiscal year ends. Stock price movements after the filing date are not reflected. If the company's stock drops 30 percent in the quarter following the proxy publication, the reported grant values overstate current wealth. I always cross-reference the filing date with the stock price on that date rather than the current price. A third limitation is assumed exit scenarios. If the executive left before a liquidity event, their equity may still be illiquid. Motley Fool's acquisition created a liquidity moment, but not every holder participated on favorable terms. The deal structure determines whether paper gains become actual cash. I track acquisition terms whenever they are publicly available. When they are not, I flag the estimate as uncertain rather than presenting it as fact.
A Specific Edge Case I Encountered
While researching another financial services executive a few years back, I ran into a problem with co-owned restricted stock units. The proxy listed the grant but did not break out the number of shares attributable to that individual versus a spousal or trust account. The filings showed total awards for a household, not a person. I could not isolate the exact personal allocation. My workaround was to look at the Schedule 13D and 13G filings. Those ownership reports sometimes list beneficial owners separately from joint owners. In this case, the individual filed a separate 13G disclosure that clarified personal versus household holdings. I used that breakdown to adjust the compensation timeline. Without that step, the net worth estimate would have been roughly double what it actually was for that person alone. I now always check ownership filings before trusting proxy grant tables for executives who appear to have significant household-level equity exposure.
Tools and Sources
The SEC EDGAR database remains the primary source. Search by company CIK and pull the proxy statement and Form 4 filings. For Motley Fool, the CIK changed after the acquisition and ticker symbol changed. I kept a note of both identifiers so I could search across the full timeline without missing filings. Public company annual reports contain the notes to financial statements. Those notes disclose option exercise prices and vesting details. I print or save those sections because they do not always appear in the summary compensation table found in the proxy. The footnote data is where the real numbers hide. For interview sourcing, I use archived press releases and financial media transcripts. Many older Motley Fool articles remain searchable through Wayback Machine or news archives. I avoid aggregator sites that repackage content without attribution. Primary sources reduce transcription errors and misattributed figures.
When the Method Fails
If the company was private for the entire executive tenure, public filing research may yield almost nothing. In that scenario, the estimate becomes mostly speculative. I recommend using industry benchmarks for comparable roles instead. Compensation survey data from firms like Radford or Mercer gives salary ranges by title, company size, and geography. Those ranges can substitute for missing disclosure data, but they should be labeled as industry estimates rather than personalized figures. Another failure mode is executives who leave with consulting agreements or earn-out provisions. Those payments are sometimes disclosed in later proxy statements as ongoing compensation, but they are easy to miss if you only look at the year of departure. I always pull three years of proxy statements after a leadership change to catch any trailing compensation disclosures. The bottom line is that net worth estimation for financial executives is an exercise in incomplete data. You can narrow the range with careful methodology, but you cannot produce an exact figure unless the person publishes it themselves. Most do not. The estimates you see online are often derived from a single compensation year and inflated by optimistic assumptions about equity value. Treat them as rough guides, not measurements.
If you need a specific number for someone like Schroll, the responsible approach is to present a range with clear assumptions and sources. I include the filing dates, stock price assumptions, and tax deduction rates in every estimate I produce. That transparency lets readers judge the reliability themselves instead of accepting a single polished figure from an anonymous website. Researching executive wealth is slower than writing a headline number, but it produces results you can defend. I prefer that outcome. The alternative is spreading guesses that look precise but are not.