Setting Up Your Wells Fargo Online Banking Account
Most people sign up for Wells Fargo online banking through the mobile app or at a local branch. The app flow is straightforward, but there are a few settings you should configure right away before you get comfortable. The biggest one is logging into your account and enabling two-factor authentication if it isn't already active. Wells Fargo defaults to multi-channel protection, which means your account gets extra verification steps when you log in from a new device or unusual location. I ran into a specific problem last year when my account got flagged after a software update changed my phone's fingerprint sensor sensitivity. The system kept triggering additional verification requests that basically locked me out of making transfers for about twenty minutes. The workaround was simpler than the panic suggested — I just used the backup one-time code Wells Fargo had sent to my registered phone number instead of relying on biometric login. Going forward, I make sure to save those backup codes in a password manager rather than trusting any single authentication method.
Wells Fargo Online Banking A Comprehensive Guide To Digital Management And Security
Digital Banking Management Features
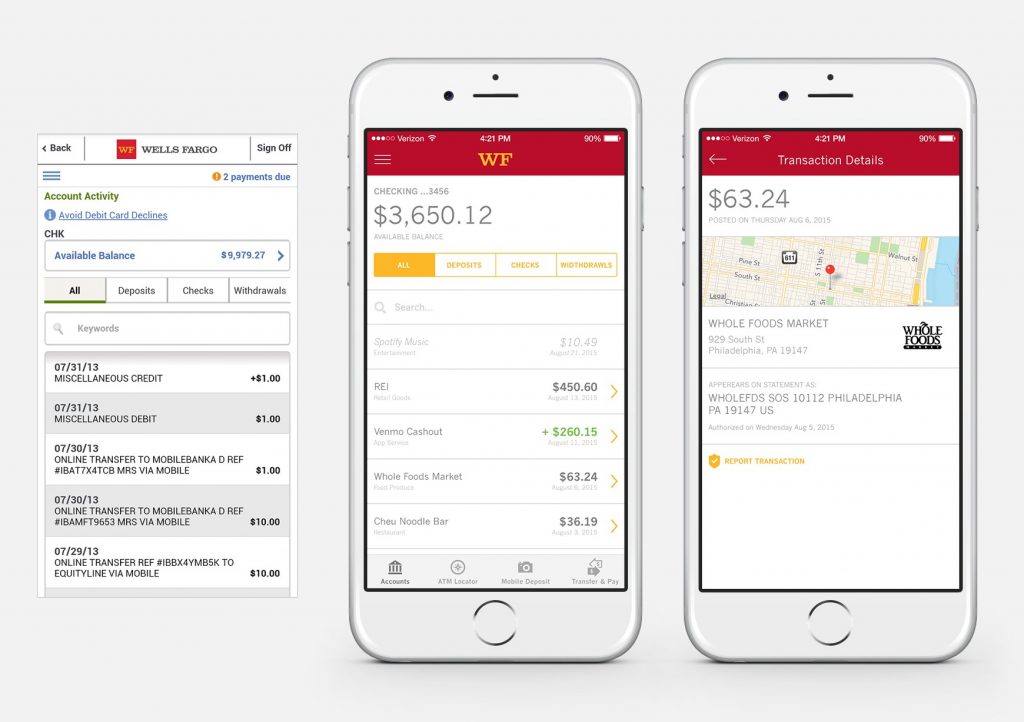
Once your account is set up, the dashboard gives you access to checking, savings, credit cards, loans, and investment accounts all in one view. The transaction history search is actually decent if you know how to use the filters. You can pull transactions by date range, amount, merchant name, or transaction type. The export feature lets you download statements as CSV files, which is useful for personal accounting software like Quicken or direct import into spreadsheet tools. The bill pay system works, but it has limitations that aren't obvious until you hit them. Wells Fargo bills pay doesn't support recurring payments to every merchant. Some utilities and service providers require manual payments each month. If you rely on automated bill pay for everything, check whether your specific vendors are actually supported before you set up recurring schedules. I learned this the hard way when a recurring payment to my homeowner's insurance didn't go through because the company had changed their payment processing system without updating Wells Fargo's vendor directory. Mobile check deposit is available through the app. You can deposit checks up to a certain limit per day, which varies based on your account history and verification status. New accounts typically start with a lower limit around five hundred dollars per day until Wells Fargo builds enough transaction history to raise it. The image quality matters more than most people realize. If your photo is blurry or the check edges are cut off, the deposit gets rejected and you have to resubmit or visit a branch.
Security Features and How They Work
Wells Fargo uses several layers of security that most customers never fully engage with. Multi-channel protection adds verification beyond just your username and password. It checks factors like your device history, location patterns, and behavior anomalies. When something triggers the system, you might get a text message, a phone call, or an email asking you to confirm the activity. Account activity alerts are configurable through the online banking portal. You can set up notifications for purchases over a certain amount, new payees added to your account, large deposits, or failed login attempts. I recommend setting a low threshold for purchase alerts, especially on credit cards. Ten dollars works well if you want to catch fraudulent charges early rather than discovering them at the end of the billing cycle. Password requirements are strict but reasonable. Wells Fargo requires a minimum of eight characters with a mix of uppercase, lowercase, numbers, and special characters. They also flag common passwords and recently used ones. If you reuse passwords across multiple banking platforms, change them all at once rather than individually. The system will eventually catch the overlap through breach monitoring.
Get the Full Details

Fraud protection covers unauthorized transactions on checking and savings accounts. Wells Fargo's zero liability policy means you aren't responsible for fraudulent charges if you report them promptly. The reporting window matters. Most banks give you up to sixty days from your statement date, but filing immediately is always better. I filed a claim once after a chip emulation card skimmer hit an ATM I used at a grocery store. The fraud department resolved it within three business days after I submitted the claim online with the specific transaction details.
Common Pitfalls and Limitations
The mobile app occasionally experiences sync delays between online and mobile platforms. If you make a change in one place, the other might not reflect it immediately. This usually resolves itself within a few hours, but it can be frustrating when you're trying to reconcile your accounts right after making a transfer. Customer service access through online banking has gotten more restricted over the years. Direct chat with a live representative is harder to find than it used to be. The automated systems can handle basic questions, but for account-specific issues, you often end up on hold or redirected to the general hotline. There isn't a reliable way to schedule callbacks from the online portal anymore. The call back feature works intermittently depending on your region and current queue load. Wire transfer limits can trip people up. Wells Fargo imposes daily and per-transaction limits on outgoing wires that vary by account type and relationship level. If you need to move more money than your limit allows, you'll need to wait until the next business day or contact your branch to request a temporary increase. Processing times for wires depend heavily on whether you're sending domestically or internationally. Domestic wires usually complete the same business day if submitted before the cutoff time, which is typically around 2:30 PM Pacific Time for outgoing wires. International wires take longer and require additional beneficiary information that can cause processing delays if anything is missing or incorrect.
Foreign transaction fees apply to purchases and withdrawals made outside the United States on Wells Fargo cards. The standard rate is three percent of the transaction amount. Some premium accounts and certain card products waive this fee, so it's worth checking your specific cardholder agreement rather than assuming the default rate applies to you.
Accessing Your Account
You can access Wells Fargo online banking through any modern web browser at wf.com or through the mobile app available for iOS and Android devices. The website works on desktop and tablet browsers, though some features may behave differently on older browsers. Mobile banking requires a compatible smartphone and the latest version of the app for full functionality. If you lose access to your registered device or phone number, account recovery involves identity verification that can take anywhere from a few hours to a couple of days depending on the complexity of your case. Having multiple forms of identification ready speeds this up significantly. Wells Fargo will ask for details like your social security number, date of birth, and recent transaction history to confirm your identity before restoring access.