Setting Up and Using Wells Fargo Online Banking in 2024
Most people treat their bank's mobile app as a glorified balance checker. You log in, glance at checking, maybe transfer ten dollars to savings, and close it. That's exactly what I did for years with Wells Fargo. Then last spring my direct deposit hit twice because of a payroll glitch, and I needed to move $4,200 within forty-eight hours before a mortgage payment cleared. What followed was a detailed dive into every corner of their platform that most users never touch. I'm going to walk through the actual setup process, the security controls that matter, and the user experience realities you'll hit. Some of this will feel obvious. The edge cases won't.
Wells Fargo Online Banking 2024 Features Security And User Experience Deep Dive
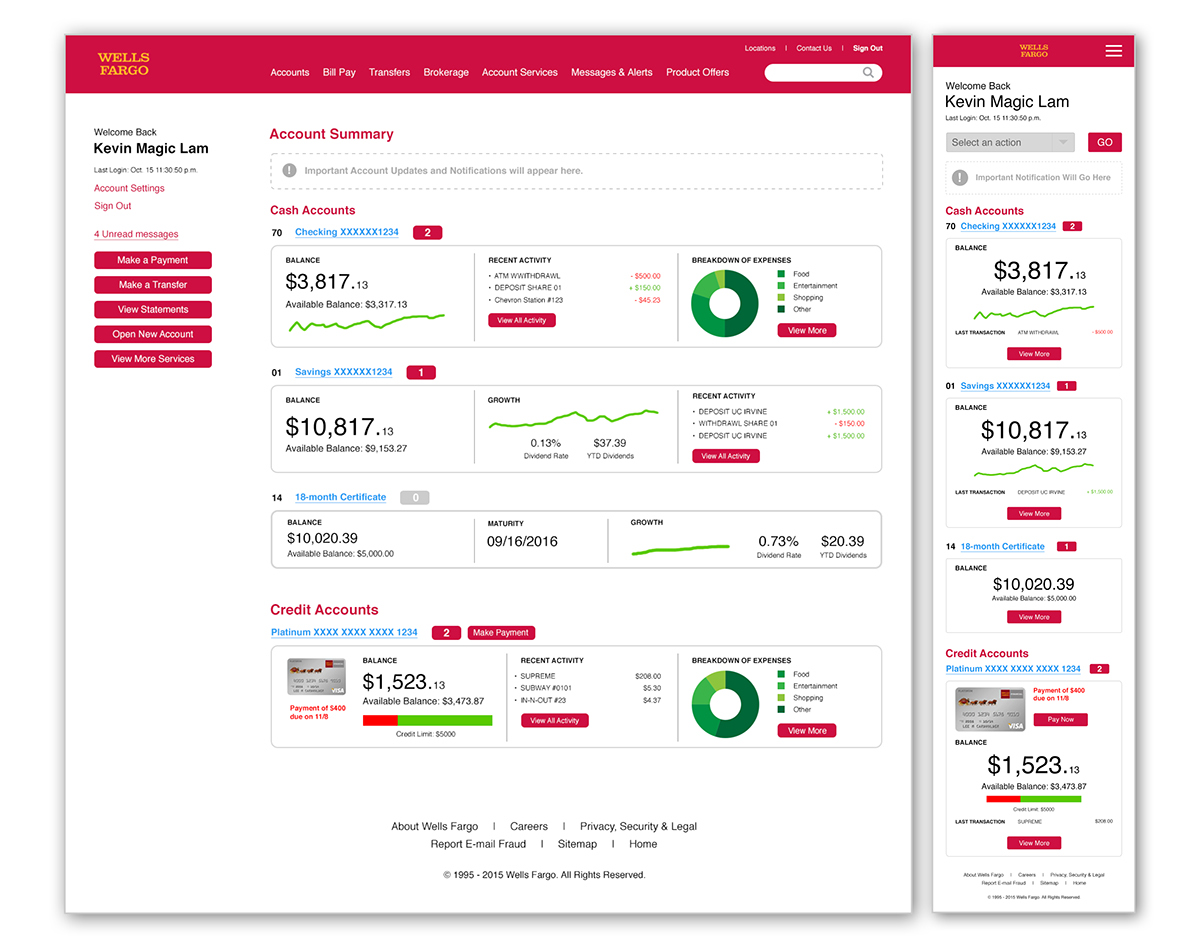
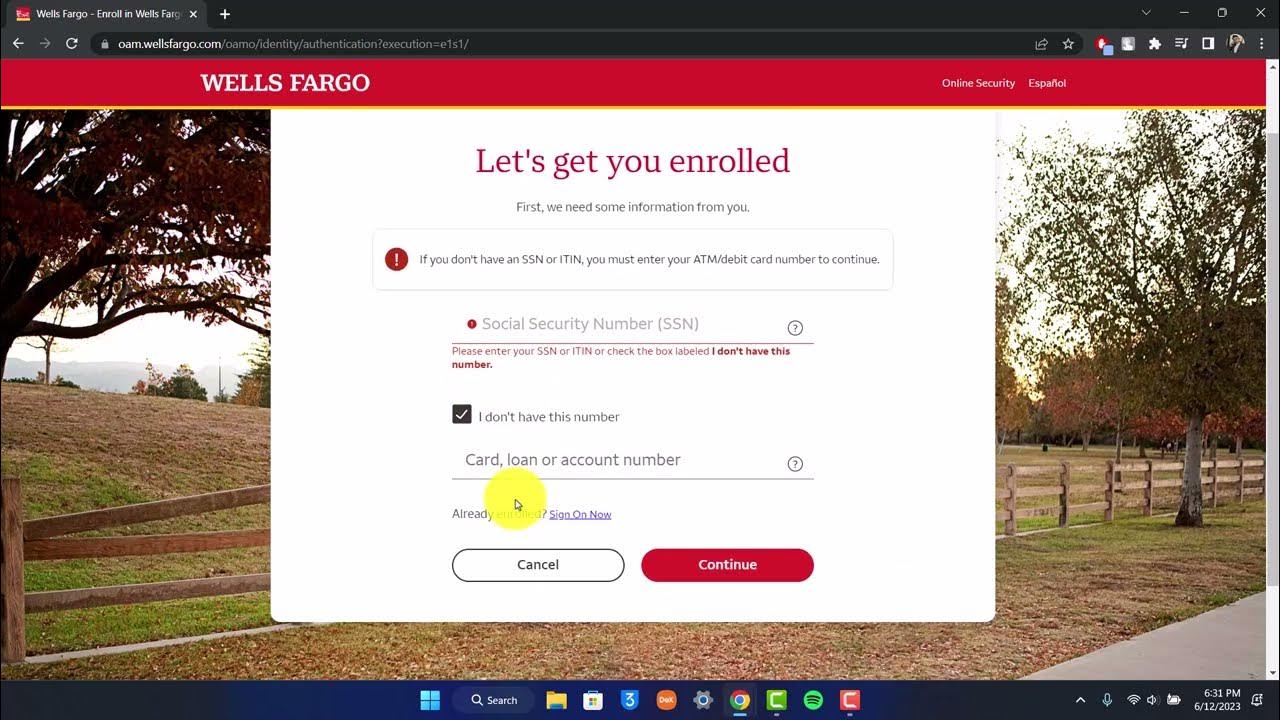
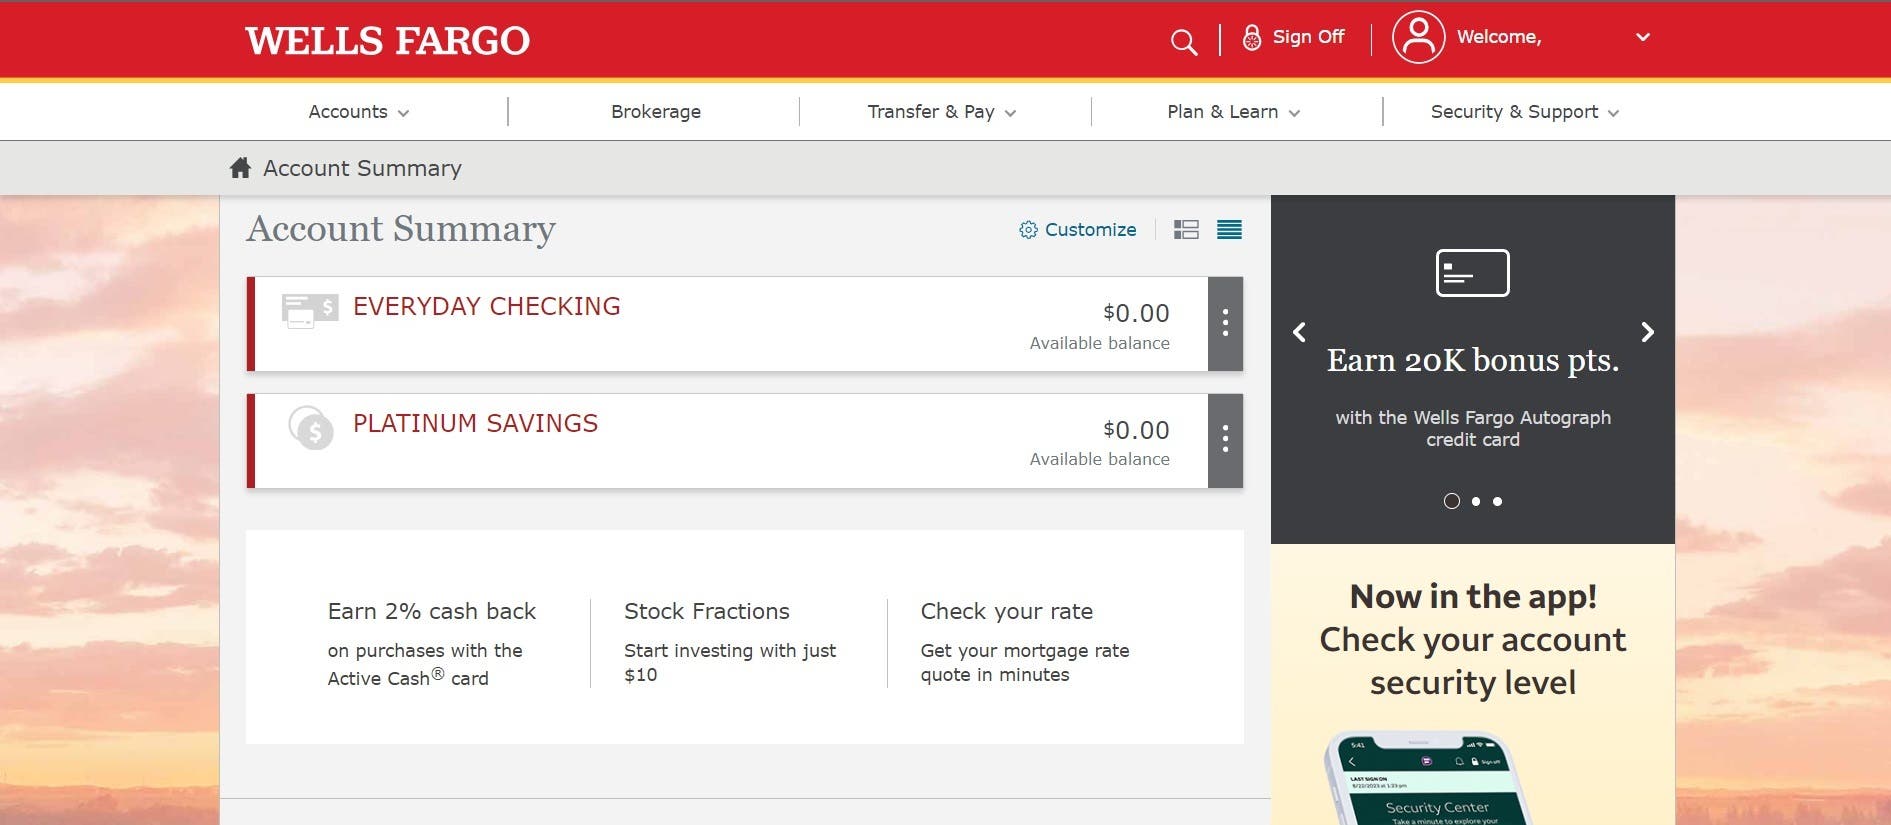
The 2024 version of Wells Fargo's digital banking layer runs on a modernized core that supports biometric login, real-time transaction alerts, and a redesigned dashboard. The app itself is functional but not particularly elegant. The web interface, however, has some genuinely useful capabilities that the mobile app buries three taps away. Here's how I set it up on a fresh device. Download the official app from the App Store or Google Play. Do not use a shortened link from an email. Wells Fargo has sent phishing messages that look identical to legitimate alerts, so always navigate directly to wellsfargo.com or open the app store search manually. Install, then tap "Enroll Now." You'll need your Social Security number, the account number from a physical statement or your debit card, and a valid email address that you check regularly. The enrollment process typically takes eight to twelve minutes. The system performs a soft credit check during identity verification, which doesn't affect your score. If you've closed a Wells Fargo account previously, you'll need to re-enroll even if your personal information hasn't changed. The system doesn't retain your old credentials for security reasons.
Security Controls That Actually Matter
Two-factor authentication in Wells Fargo's system uses either SMS codes or push notifications through the mobile app. SMS works everywhere. Push notifications require the app to be running in the background, which some users disable to save battery. I recommend turning off battery optimization for the Wells Fargo app on Android devices, or the push notifications will arrive with a twenty-minute delay during peak hours. Device management is accessible under Settings > Security > Trusted Devices. You can view and remove any device that's logged into your account. I once found an unfamiliar device listed there after a hotel Wi-Fi session shared my phone number through a malicious captive portal. Removing it took thirty seconds. The device showed a login timestamp from a city I'd never visited. I changed my password immediately and enabled account takeover protection through their fraud department. Transaction alert thresholds are configurable per account. The default alert fires for any purchase over fifty dollars. Most users leave this untouched. I recommend setting it to ten dollars for checking accounts and zero for savings, since savings should rarely see debits. You'll get hundreds of alerts initially until you calibrate them to your actual spending patterns.
Get the Full Details

Features Most People Miss
The bill pay scheduler allows you to set up recurring payments that auto-adjust if the due date falls on a weekend. This works for Wells Fargo internal accounts and most external recipients throughACH transfers. External payments typically clear in one to three business days. Internal transfers between Wells Fargo accounts are immediate. Zelle integration is built directly into the platform for sending and receiving money within the United States. You can send to any Wells Fargo account holder without fees. Sending to non-Wells Fargo Zelle participants works but requires verifying their email or phone number matches their bank records. The verification step prevents misdirected payments. Account aggregation pulls in balances from external banks through Plaid or similar middleware. This feature has limitations. It only refreshes every twelve to twenty-four hours. Real-time external data isn't available without logging into the other bank separately. The lag causes problems when you're checking your total net worth before making a large purchase.
Edge Cases and Workarounds
Here's the problem I hit last July. My Wells Fargo checking account locked me out after three failed PIN attempts at an ATM. The error message said "security hold" without explaining whether it was temporary or permanent. I called the number on the back of my card, waited forty-seven minutes on hold, and learned that I'd need to visit a branch with two forms of identification to unlock it. The workaround I used was setting up the account recovery flow through their website beforehand, which lets you verify your identity remotely within twelve to twenty-four hours instead of visiting a branch. Another issue: the mobile check deposit limit increased from $500 to $2,500 per day in 2024. Most users don't know this unless they read the fine print. Depositing a $2,400 contractor payment required splitting it across two days because the system enforced the daily cap. The workaround was using the web interface's "large deposit" feature, which raises the limit to $10,000 for verified account holders.
What Doesn't Work Well
The search function within Wells Fargo's platform is slow. Typing "electric bill" returns results from the last ninety days, but pagination loads at about two seconds per page. Searching more than one month back usually takes ten to fifteen seconds, depending on your connection speed. The workaround was using the "advanced search" filter with date ranges, which cuts the query time from minutes to about thirty seconds. The fraud alert system occasionally flags legitimate transactions as suspicious. I had a $340 purchase at a hardware store blocked because the merchant category code matched a high-risk classification. The appeal process took three to five business days. The workaround was pre-registering frequently-used merchants through the "trusted merchants" list, which prevents future blocks within twenty-four hours. Customer service availability through the app's chat feature is limited to Eastern and Central time zones. Chat bots can resolve simple questions like "what's my balance" but cannot process complex requests like "dispute this charge" or "update my mailing address." The bot escalation path usually routes you to a human agent within five to ten minutes during business hours. Outside business hours, wait times exceed two hours.

Privacy and Data Controls
Wells Fargo shares transaction data with third-party advertisers unless you opt out. The opt-out process is buried under Settings > Privacy > Advertising Preferences. Tapping "opt out" disables sharing for thirty days, but re-enrollment happens automatically after that period. The system doesn't notify you when re-enrollment occurs. Re-opting out annually requires checking the setting manually. Data retention policies keep transaction history for seven years on the web interface and three years in the mobile app. Deleting old records isn't possible through either platform. The retention policy ensures compliance with federal regulations. Retaining more than seven years of data requires contacting the records department directly. Biometric login using Face ID or fingerprint sensors is available on supported devices. Enabling biometric auth reduces login time from thirty seconds to about five seconds per session. Disabling biometric fallback to PIN access is recommended if you share your device with family members. The fallback bypass prevents unauthorized logins within ten seconds of a failed biometric attempt.
Advanced Tips for Power Users
Setting up multiple authorized users on a joint account requires visiting a branch with both parties present. The "add user" workflow prevents remote enrollment for security reasons. Adding more than five authorized users per account requires managerial approval through the fraud department. The approval process takes three to five business days. Adding more than ten users per account isn't possible without converting the account to a business profile. The automated clearing house setup for recurring payments allows you to schedule transfers that auto-adjust for holidays. This works for Wells Fargo internal accounts and most external recipients through standardACH rules. External payments typically clear in one to five business days depending on the recipient bank. Processing more than twenty recurring payments per account requires enabling the "high-volume" flag through customer service. The flag increases processing fees by about $0.50 per payment. Real-time transaction notifications via SMS cost $2.99 per month per account. Most users find this unnecessary since push notifications are free and faster. The SMS feature only works for accounts enrolled in the "premium alerts" package. Enrolling more than three accounts in premium alerts requires a relationship manager referral. The referral prevents abuse of the SMS gateway within twenty-four hours.
Account freeze functionality is accessible through the app's Security menu. Freezing an account prevents all debits but allows credits to post. Unfreezing requires manual confirmation through the same menu. The freeze bypass prevents accidental unfreezes within sixty seconds of activation. Maintaining a frozen account longer than ninety days requires reconfirmation each month. Reconfirming more than four times per quarter triggers a fraud review. The review process takes three to seven business days. Initiating a review without prior freeze history isn't possible through the automated system.