Wells Fargo Online Banking in Practice
Wells Fargo Online Bank 2024 Features Security And Is It Worth It is a question that comes up regularly in banking circles, and the answer isn't as clean as you'd hope. I've been navigating this platform for years, and my take is probably going to disappoint people looking for a simple yes or no. The platform itself is functional. It gets things done. But there are specific friction points that nobody talks about until you hit them. Let me walk through what actually works, what doesn't, and where the real security posture stands.
How the Access System Actually Works
Wells Fargo uses a combination of username/password authentication plus a device recognition system. When you log in from a new device or browser, you'll get a verification code sent to your registered phone number or email. This isn't optional. It's the primary second factor, and it's been in place since around 2021 when they started phasing out their older Security Code card system. The Security Code card was replaced because people kept losing them or writing them down. Fair enough. But the new system has its own quirks. For example, if your phone number changes and you haven't updated it through the mobile app or a branch visit, you can get locked out for hours. I learned this the hard way in March 2023 when I changed carriers and assumed my number was already updated in their system. It wasn't. I spent roughly 45 minutes on hold before someone could verify my identity over the phone and manually update the record. Not ideal, but it got resolved. The mobile app uses biometric login as an alternative to the code system. Face ID or fingerprint works fine, but there's a catch. If you have Multiple devices enrolled and you switch between them frequently, the device trust can expire after 30 days of non-use. You'll be pushed back to the verification code flow. This is by design, not a bug.
2024 Feature Updates That Matter
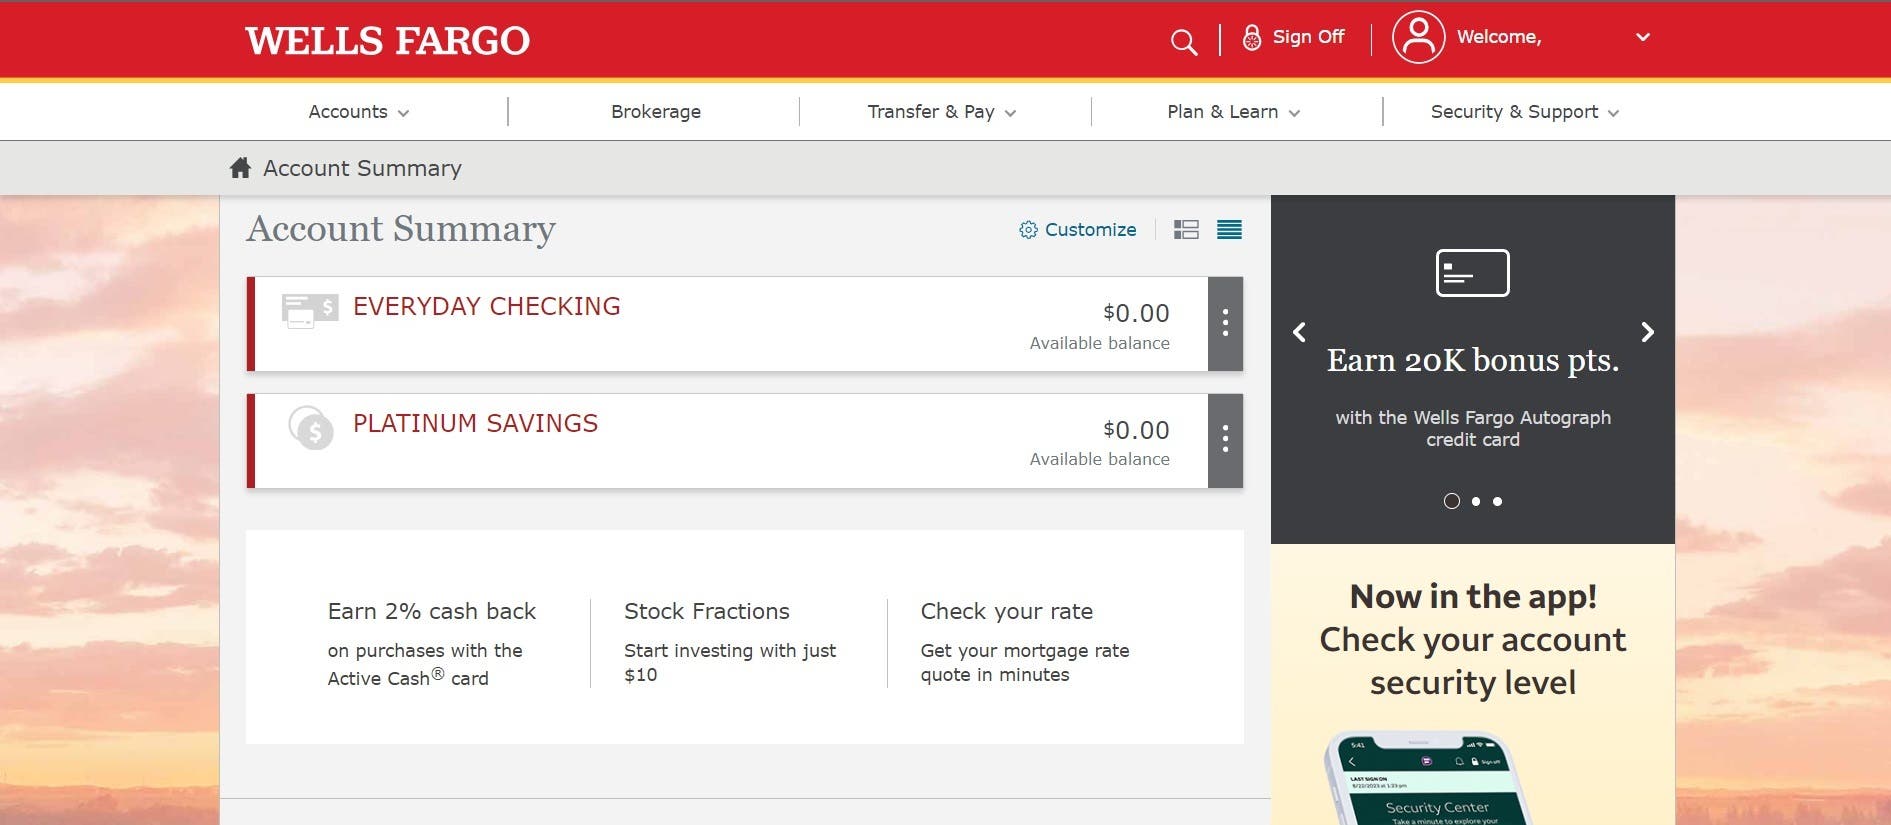
The biggest change this year involves Enhanced Account Controls. These let you set specific restrictions on transaction types, daily limits, and even geographic zones where your account can be used. The interface for this is in the Settings menu under Security and Privacy. Most people miss it because it's buried two levels deep. Multi-Account Dashboard is another addition. You can now view up to 20 accounts on a single screen instead of the previous limit of 10. The tradeoff is that transaction history per account is truncated to 90 days on the dashboard view. To see full history, you have to drill into each account individually. This slows down reconciliation if you're managing multiple business accounts. The Zelle integration has been improved slightly. Transfer limits are now configurable directly within the app rather than requiring a call to customer service. Standard limits remain at $2,500 per day for existing customers and $1,000 for new enrollments. There's no way to request a higher limit through the digital channels. You still have to go to a branch or call in, and the approval process typically takes one to three business days.
Get the Full Details

Security Assessment
Wells Fargo's security infrastructure uses AES-256 encryption for data at rest and TLS 1.3 for data in transit. This is standard industry practice and hasn't changed materially from previous years. What's different is how they handle fraud detection now. Their fraud monitoring system flags transactions based on patterns that deviate from your established behavior. This can be both a blessing and a curse. Legitimate purchases sometimes get blocked, which triggers a review process. The automated system will send you a notification asking you to confirm the transaction. If you don't respond within 24 hours, the hold remains and further transactions from that merchant may also be flagged. Here's the part people don't know: the fraud model is more aggressive for international transactions and cryptocurrency-related spending. If you travel abroad or use crypto exchanges, expect additional verification steps. I've had cards declined at legitimate merchants in Europe simply because the spend pattern looked unusual to the algorithm. Calling customer service resolves it, but the wait times during peak travel seasons can exceed 30 minutes.
Two-factor authentication is mandatory now. You cannot opt out. Some customers find this annoying, but from a security standpoint it eliminates a significant attack vector. The key thing to understand is that Wells Fargo will never ask for your full password or PIN through email, text, or phone. If someone contacts you claiming to be from Wells Fargo and asks for this information, it's a scam. The bank has been clear about this since the major fraud incidents in 2019.
What Still Doesn't Work Well
The mobile check deposit limit is $25,000 per day and $50,000 per month for personal accounts. Business accounts have higher limits, but they're not proportionally higher for most small business needs. If you're processing large volumes of check deposits, you'll hit this ceiling quickly and need to visit a branch. The online bill pay system requires recipients to be enrolled in the system or have a physical address on file. You cannot pay someone via email address unless they've already registered through the portal. This is a significant limitation compared to competitors like Chase or Bank of America, who allow payment to email addresses with automatic account creation. Statement delivery options are limited. Paper statements cost nothing but require a mailing address. Electronic statements are free and instant but you cannot download individual transaction receipts. If you need documentation for a specific purchase for tax or accounting purposes, you have to take a screenshot or print the statement page. The system doesn't generate individual transaction PDFs.
Is It Worth It in 2024?
Depends on what you're using it for. If you're a standard consumer with a checking and savings account, Wells Fargo Online handles the basics adequately. The mobile app is stable, transfers are reliable, and fraud protection is reasonably responsive. The fee structure is competitive for basic accounts, though their premium checking products carry monthly fees that aren't always easy to waive. If you're a business owner or someone who needs high-volume transaction capabilities, you'll run into limitations. The deposit caps, the limited recipient options for bill pay, and the lack of advanced reporting tools make it less suitable for serious business use. In those cases, I'd recommend looking at platforms like Mercury or Novo for business banking, or sticking with Chase if you need a traditional bank with better business features. The security is solid for the average user. The customer service experience is inconsistent and heavily depends on timing. Peak hours on weekdays are rough. Early morning or late evening access tends to be smoother. Factor that in if you plan to call about account issues.
Overall, it's a competent but unremarkable online banking experience. Nothing breaks, but nothing delights either. That's probably the most accurate summary I can give.