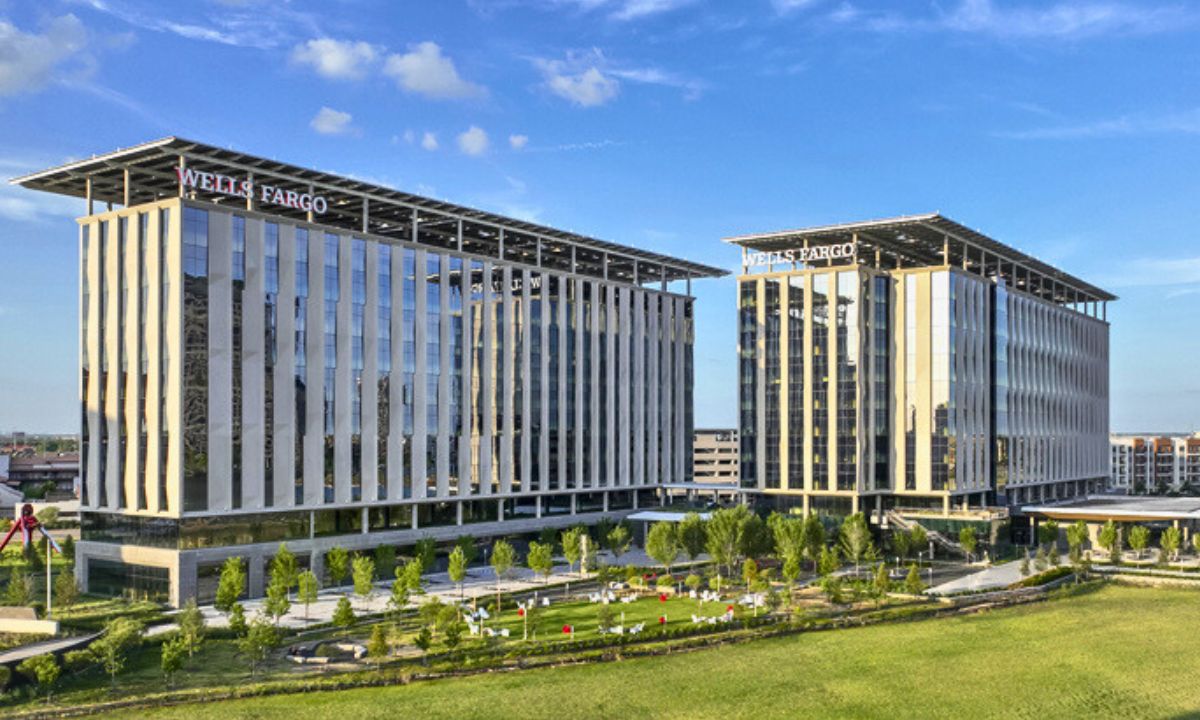
Wells Fargo HQ A Hub Of Innovation And Progress
The Wells Fargo headquarters building in San Francisco has been through some changes over the years. Not the dramatic kind you see in business magazines, just the slow, grinding sort that happens when a massive bank tries to modernize while still running one of the largest retail banking networks in the country. I spent about three years working with their commercial banking division's technology migration project, so I have a somewhat grounded view of what actually goes on there beyond the press releases. Wells Fargo is currently pushing several initiatives through its HQ that are meant to modernize how they operate. The main ones include digitizing legacy paper-based processes, updating their customer-facing mobile and online platforms, and integrating more AI-driven tools into their compliance and fraud detection systems. There is also work being done on their data infrastructure, which is still a mix of old mainframe systems and newer cloud-based services. This isn't unusual for a bank of that size, but it does create a lot of friction when you are trying to make anything actually move. The innovation hub aspect is real enough. They have a dedicated facility in San Mateo that handles a lot of the fintech partnerships and internal product development work. It is not as flashy as some of the tech campus setups you might picture, but it does get things done. I know because my team had to interface with them on a regular basis during our migration project.
One thing that catches people off guard is how much the innovation work at Wells Fargo HQ depends on coordination with their legacy systems team. You cannot simply deploy a new API or service without it going through several approval layers. This is not because the people at HQ are being difficult. It is because a bank this size has thousands of interconnected systems, and moving one piece can break something else entirely. I learned this the hard way when we tried to integrate a new loan servicing tool and ended up spending six weeks untangling permissions that had been set up in 2014 by someone who was no longer employed there. Here is how the process actually works if you are on the outside trying to partner with them or integrate with their platform. You start with a vendor registration and security review, which alone can take anywhere from six to fourteen weeks depending on the sensitivity of the data involved. After that, you get assigned a liaison from their technology team who will guide you through their integration requirements. These requirements include things like SOC 2 compliance, data encryption standards, and API specifications that match their internal architecture. Most third-party vendors fumble at least one of these on their first attempt, and it adds months to the timeline. The mobile banking app improvements and the online platform upgrades are probably the most visible outputs of this work. They rolled out a redesigned interface last year that removed a lot of the clutter from the previous version. It was not a revolutionary change, but it was noticeable. Customer support volume dropped slightly after the rollout, which suggests people were actually struggling with the old layout.
On the AI and machine learning side, Wells Fargo has been using these tools primarily for fraud detection and credit risk assessment. Their system flags suspicious transactions and assigns them to human reviewers, which is the standard approach in the industry. What is less talked about is how much manual override happens in practice. The algorithms are not perfect, and sometimes legitimate activity gets blocked or flagged incorrectly. I saw this firsthand when a client of ours had their account frozen for three days because the fraud model misclassified a large transfer as potentially fraudulent. It was eventually resolved, but the process for getting it unstuck was tedious. If you are looking at this from a competitor or partner angle, the main takeaway is that progress at Wells Fargo HQ is incremental rather than explosive. They move carefully because they have to. The upside of that caution is that once something ships, it tends to be relatively stable. The downside is that things take a long time to get there in the first place. There is a certain irony in calling the headquarters of a bank that has faced so many regulatory issues a hub of innovation and progress, but the work being done there is genuine even if the marketing language around it is polished. The innovation pieces are real. The progress is measured in small steps rather than giant leaps, and that is probably the most accurate description of what large-scale institutional change looks like.
Get the Full Details
One practical tip if you are working with them: do not underestimate the onboarding and compliance paperwork. Having your security documentation ready before you even start the conversation with their partnership team can cut weeks off the process. I have seen companies waste time going back and forth on things like business continuity plans and incident response procedures simply because they assumed those would be straightforward. They are not, not at this scale. The physical HQ itself is a large complex in downtown San Francisco, and much of the day-to-day innovation work happens there alongside the traditional banking operations. It is not a sterile corporate environment, but it is not a startup campus either. It is what you would expect from a 160-year-old financial institution trying to stay relevant in a digital world. The people working there generally know what they are doing, and the systems they are dealing with are genuinely complicated. That is the honest assessment without the hype.