Getting Cash Abroad Without Getting Ripped Off
I've spent enough time at foreign airport kiosks and bank branches to know how the currency exchange business actually works. Most people have no idea they're losing money until they're already standing in line in Tokyo or Rome. Let me walk you through what Wells Fargo offers for currency exchange, what the actual costs are, and where you might be better off going instead. Wells Fargo lets you order foreign currency online for pickup at a branch, but they don't give you the interbank rate. Their spread is roughly 5-7% above the mid-market rate, which is worse than most alternatives. For a $1,000 exchange, you're looking at about $50-$70 in hidden fees built into the rate itself. There's also a small transaction fee depending on your account type, usually between $3 and $5 for Premier clients, higher for standard checking accounts. The convenience factor is real though. You can order online, pick up at a branch, and not worry about finding an ATM abroad. But that convenience has a price tag that adds up fast if you're traveling for more than a few days.
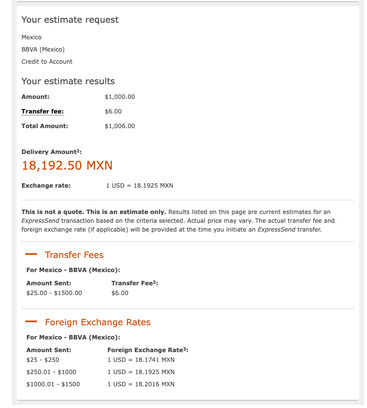
Here's something most people don't know: Wells Fargo only pre-orders a limited selection of currencies. If you need Brazilian real, Thai baht, or South African rand, you might not be able to get it at all through their pre-order system. I ran into this exact problem last year when I needed Mexican pesos for a layover in Cancun. The local branch had about $200 in stock and couldn't fulfill my request for more without a two-week lead time. I ended up using a debit card at the airport ATM instead, which cost me about 4% in total fees but got me cash the same day.
How The Exchange Rate Actually Works
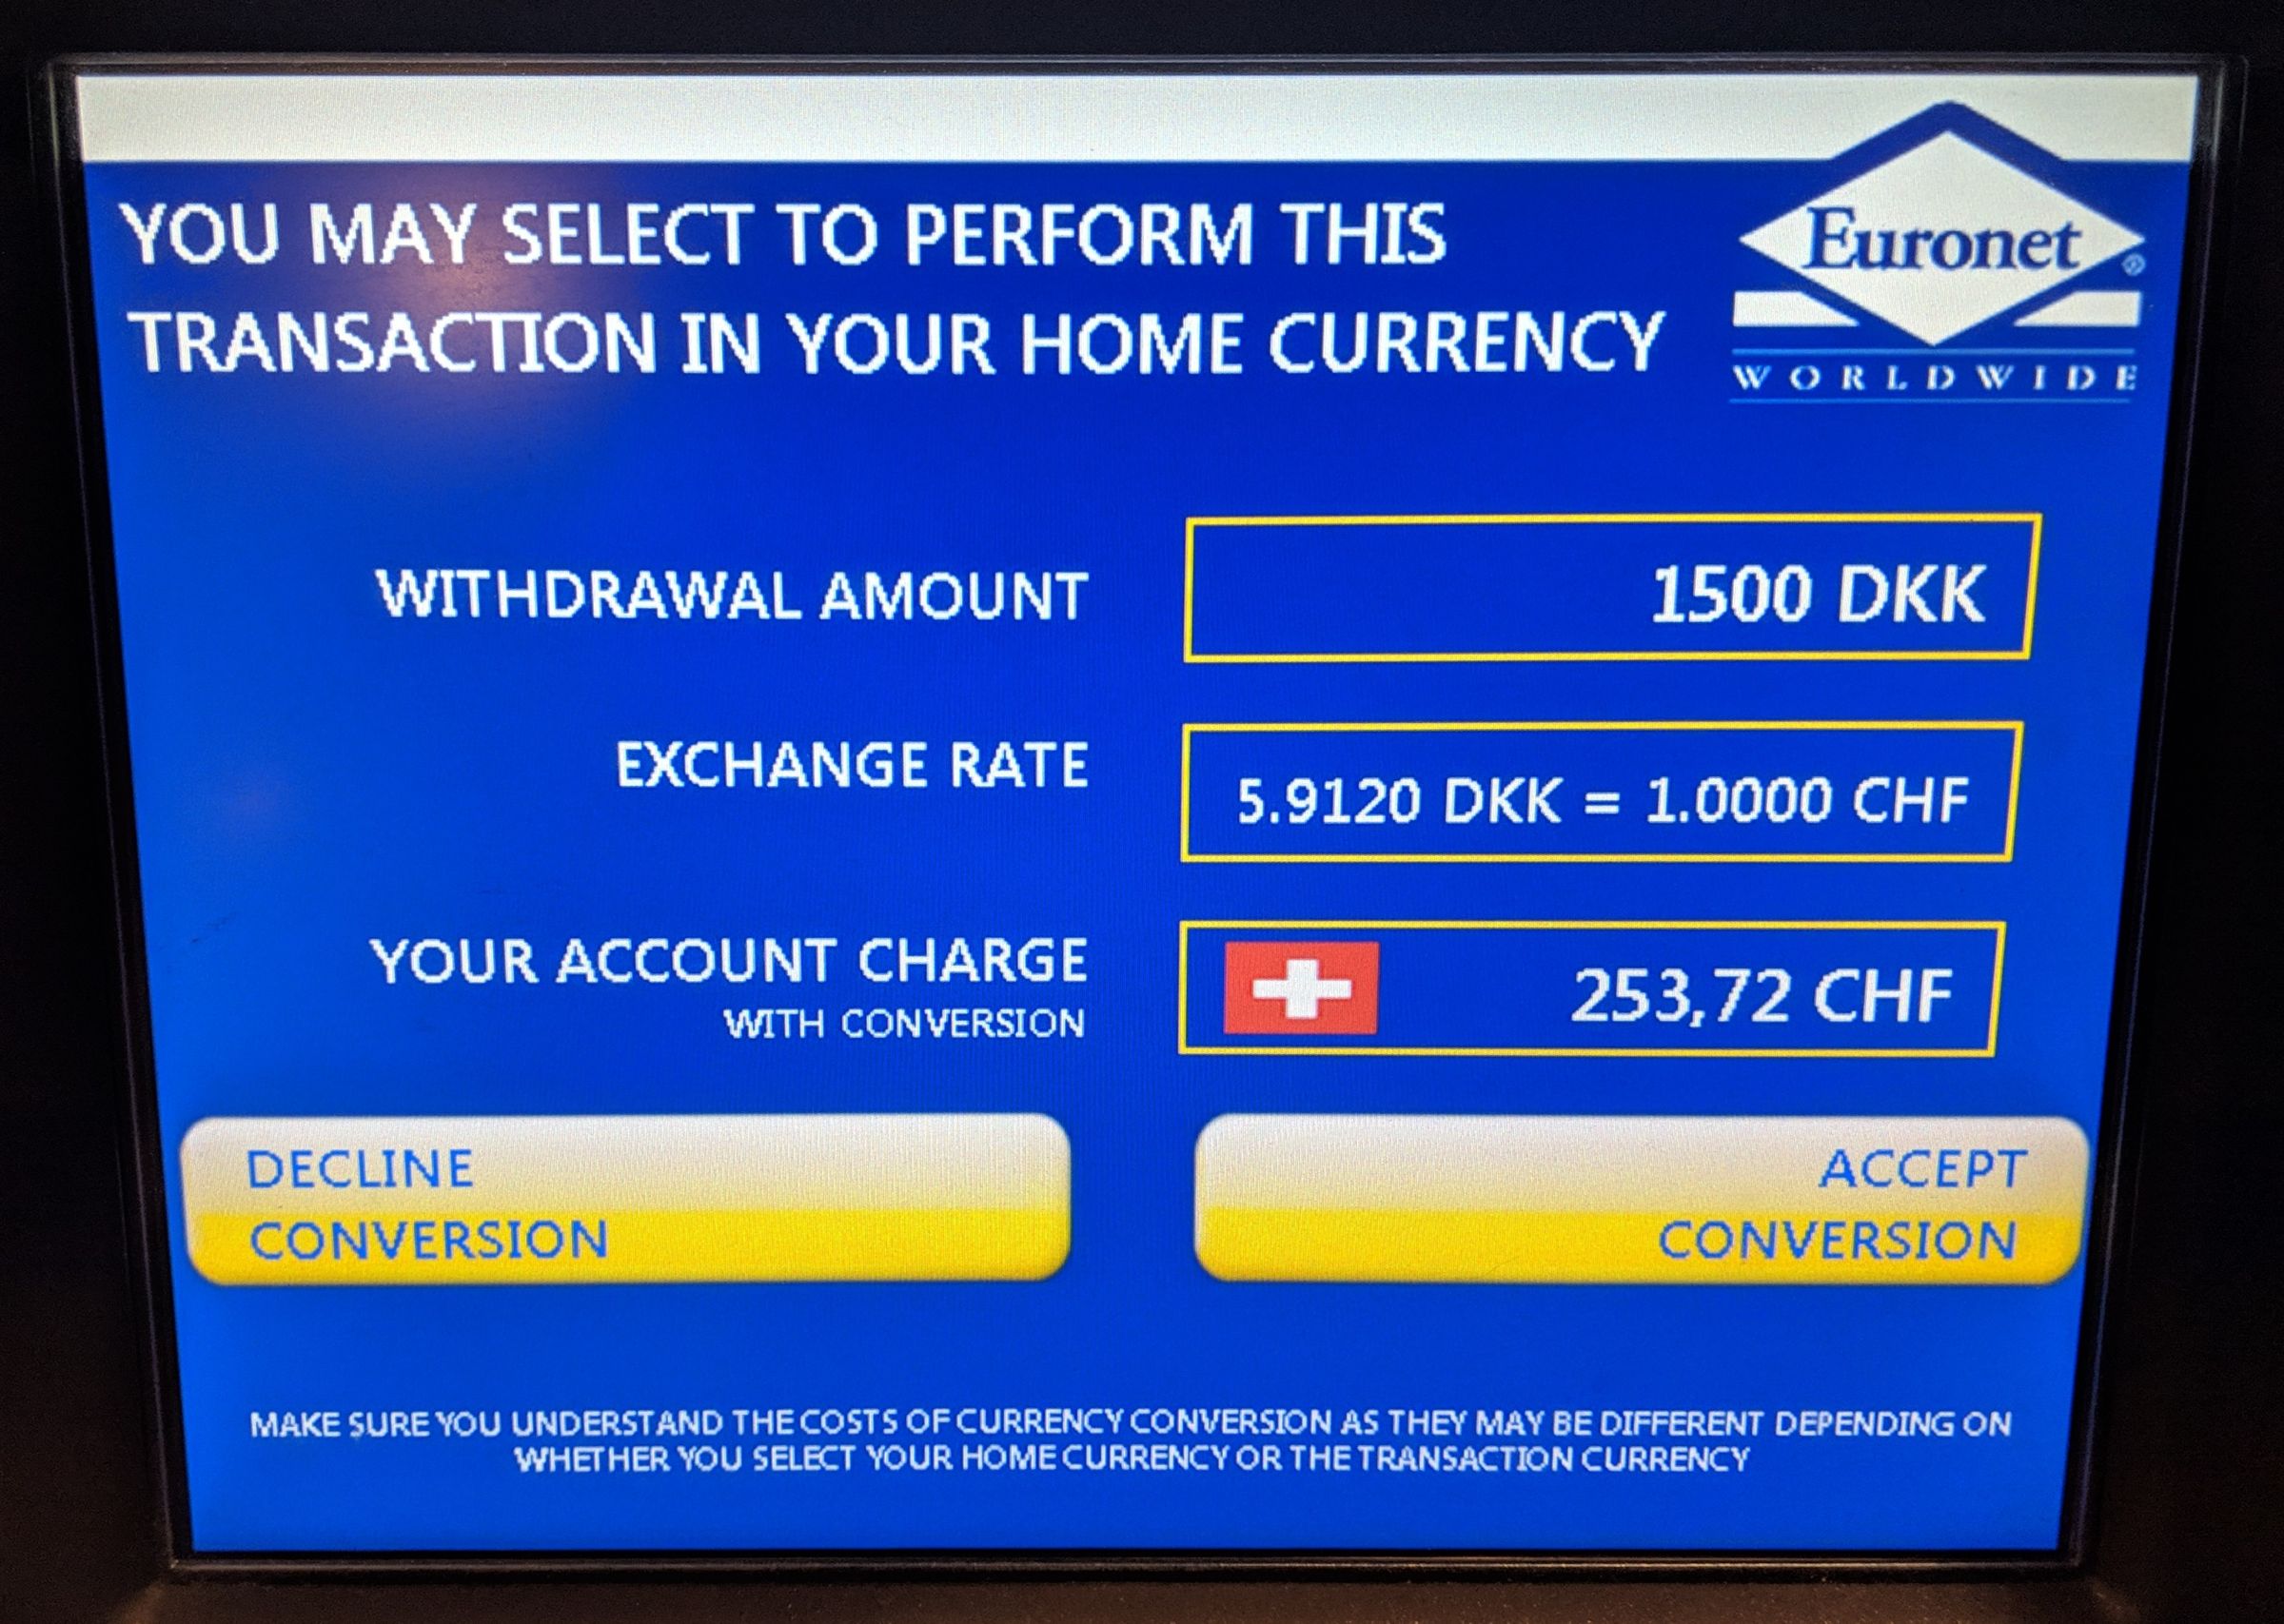
When Wells Fargo posts their buy and sell rates, they're adding their margin on top of the interbank rate you see on Google orXE.com. This is called the bid-ask spread and it's where they make most of their money. Here's the breakdown: they show you a rate that's already priced with their profit built in. You won't see a separate "commission" charge on most transactions because the markup is hidden inside the exchange rate itself. For major currencies like euros, British pounds, and Japanese yen, the spread is tighter because those are high-volume trades. For exotic currencies, the spread can be 10% or more. I once calculated the difference when exchanging Singapore dollars through Wells Fargo versus using a Charles Schwab debit card at a local ATM. The Wells Fargo route cost me about 6.2% more than the ATM method, and that was using their "competitive" online rate.
Get the Full Details
What You Actually Pay
Beyond the spread, there are a few other costs to consider. Account holders with premium checking accounts might get reduced or waived transaction fees, but the spread remains the same. If you need currency you didn't order in advance, walk-in rates are significantly worse than pre-order rates. I walked into a branch one time needing euros on short notice and the rate was roughly 8% above the mid-market rate compared to about 6% for pre-ordered currency. There's also the issue of partial fills. Wells Fargo sometimes only gives you part of your order and tells you the rest will arrive in a few days. This happened to me when I needed $800 in euros for a business trip. They gave me $400 and said the rest would be ready the next business day. I had to find alternative cash for the first day anyway, which meant paying ATM fees twice.
Better Alternatives To Consider
Travel-focused debit cards from companies like Charles Schwab and Capital One charge no foreign transaction fees and give you near-interbank rates when you withdraw from ATMs abroad. The Schwab Platinum Rewards debit card refunds all ATM fees worldwide, so you're really only paying the local ATM operator's fee if they charge one. Most of the time you'll save between 3% and 5% compared to Wells Fargo's rates on the same amount. Credit cards with no foreign transaction fees are another option for purchases. Chase Sapphire Preferred, Capital One Venture, and many others handle currency conversion at the Visa or Mastercard network rate, which is much closer to the interbank rate than any bank's cash exchange rate. The key difference is you're getting the wholesale rate rather than the retail rate. If you absolutely need physical cash before you leave, consider using a service like Revolut or Wise. These platforms offer competitive rates with minimal spreads and let you lock in rates ahead of time. I switched to Wise for my regular currency exchanges after comparing costs across three trips. For a $2,000 exchange, I saved roughly $40 compared to Wells Fargo's pre-order rate.
When Wells Fargo Might Still Make Sense
There are specific situations where sticking with Wells Fargo is reasonable. If you're already a Premier client with waived fees and need a small amount of common currency on very short notice, the branch pickup is convenient. If you're traveling to a destination where ATMs are unreliable or scarce, having cash on hand before departure removes one variable. I know travelers who went to rural parts of Italy and Greece where card acceptance dropped significantly, and the pre-ordered cash made a real difference. But for the average traveler visiting major cities with good banking infrastructure, the extra cost isn't justified. The combination of a no-foreign-transaction-fee card for purchases and a fee-refunding debit card for ATM withdrawals will almost always beat Wells Fargo's exchange rates. The math is straightforward and consistent across multiple currencies and trip lengths I've tracked.
The Bottom Line On Practical Costs
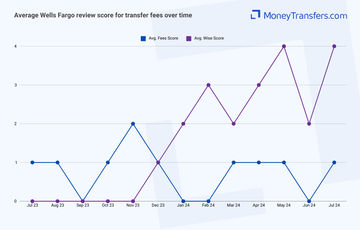
For a typical two-week European trip spending about $3,000 on exchanges and withdrawals, Wells Fargo will cost you roughly $150-$210 in combined fees and spread. Using a fee-free card strategy with ATM withdrawals instead, that drops to about $30-$60 total. The difference is substantial enough that it matters on any moderate trip budget. If you're exchanging larger amounts for extended stays or multiple destinations, the gap widens further. The process of switching strategies is simple. Cancel your Wells Fargo currency order if you haven't picked it up yet, open a no-foreign-transaction-fee credit card, and get a debit card from a bank that refunds ATM fees. Then order just enough cash from Wells Fargo or a local ATM for your first day and rely on cards for everything else. That's how I've been handling it for the past two years and it's consistently cheaper without adding meaningful complexity to the trip.