Getting a cashier's check at Wells Fargo
Cashier's checks are one of those things banks make you jump through hoops for, and Wells Fargo is no different. You show up, you prove the money is actually yours, and you wait. That's the short version. Here's what actually happens when you go through the process, plus some things the teller won't volunteer. You need to have the full amount of funds available in a Wells Fargo account before they'll print one. Personal checks don't count as proof of funds. They won't hold the money and then give you a cashier's check three days later. You hand them the money or authorize an immediate transfer from your checking or savings account, and then they issue the check. The fee is typically around $10 to $15 depending on your account tier. Some premium accounts get it waived entirely. If you're not sure about your account type, check your monthly statement or call the number on the back of your debit card before you drive to the branch. I learned this the hard way once. I had a client who needed a cashier's check for a real estate closing and he'd transferred the money from an external account that morning. The transfer was pending. The branch held him for two business days while they verified the funds actually cleared into his Wells Fargo account. He missed the original closing date by forty-eight hours because he assumed the transfer was instant. External ACH transfers usually take one to three business days. If you need the check urgently, wire the funds from your other bank instead, or transfer through a same-day Fed wire if your bank offers that. It costs extra but it clears the same day.
The actual process at the branch
Walk into a branch during business hours. Not every Wells Fargo location offers cashier's checks at all branches. Some smaller offices route you to a larger branch. Call ahead if you can, especially if you're going to a neighborhood office rather than a flagship location. Bring a government-issued photo ID. A driver's license or passport works. They need to verify your identity against their records. The teller will ask for the payee name, the dollar amount, and which account to draw from. Double-check the payee name before they print it. If you misspell "Smith" as "Smyth," the receiving institution may refuse the check, and then you're back to square one trying to get it reissued. Wells Fargo charges a reissue fee on top of the original fee. You're looking at another $10 to $15 out of pocket for a typo you could have caught in ten seconds. If you're signing up for new online banking at the same time, the teller might try to upsell you on that. It's optional. You don't need it to get the check. Just say no and move on.
What most people get wrong about timing
Cashier's checks are supposed to be available immediately once the funds are verified. In practice, there's a good chance you'll walk out with it the same day, but not always. Wells Fargo places holds on checks under certain conditions. If this is your first time opening a new account and depositing a large amount, they may place a hold that stretches the availability. New accounts with large deposits are exactly the scenario that triggers extended holds under Regulation CC. The hold rules are technical. Generally, the first $225 of a check must be available the next business day. Beyond that, the rest of the funds can be held for up to five business days for local checks and up to seven for non-local checks. This applies to deposited checks, not necessarily to withdrawing your own money to write a cashier's check, but the policies overlap in confusing ways. If you're pulling funds from an account you've had for years with a solid history, you'll probably walk out with the check in twenty minutes. If you just opened the account last week and deposited a $15,000 check that morning, expect to wait.
Get the Full Details

Fees and cost structure
Standard cashier's check fee at Wells Fargo runs $10 for existing checking customers and can go up to $15 for basic accounts. Premium accounts like Performance Checking or Privilege Checking often have the fee waived. Rewards Checking may also include free cashier's checks as a benefit. Check your account disclosure documents or log into online banking and search for "fee schedule" to confirm what applies to your specific account. There's no percentage-based fee. It's a flat amount regardless of whether the check is for $500 or $50,000. That's one advantage over money orders, which cap out at lower amounts and sometimes carry higher relative fees for small purchases. A $15 fee on a $50,000 check is negligible. A $15 fee on a $200 check stings more, but that's the reality of flat-fee banking products.
When a cashier's check isn't the right tool
Cashier's checks are often treated as the gold standard for secure payments, and they're better than personal checks in most situations. But they're not universally the best option. If you're paying for something online, a cashier's check is useless. The recipient can't deposit it through an app. You'd have to mail it, which introduces delay and risk of loss in the mail. For online transactions, a wire transfer or a trusted payment platform is faster and more trackable. Wire transfers from Wells Fargo cost more — typically $15 to $30 for outgoing domestic wires — but they clear faster and leave a digital trail. If you're buying something from a private seller who accepts Zelle or Venmo, a cashier's check is overkill. You're paying a fee for security you don't need. Cashier's checks do have real drawbacks. They're not traceable in the same way a wire is. Once you hand the check to someone, you lose visibility into where it goes. If the recipient deposits it and then disputes the underlying transaction, your money is already gone from your account. There's no chargeback mechanism like there is with credit cards. You'd have to pursue the recipient directly or through small claims court if something goes wrong.
Another issue: if you lose a cashier's check, getting a replacement is expensive and slow. Wells Fargo charges a stop payment fee, which is usually $15 to $30, and then they issue a reissued check after a waiting period that can span several business days. You need the receipt they give you when you pick up the check. Lose that receipt and the process gets harder. Photograph it or scan it immediately. Store the image in your cloud storage or email it to yourself. It takes two seconds and saves you hours of frustration later.
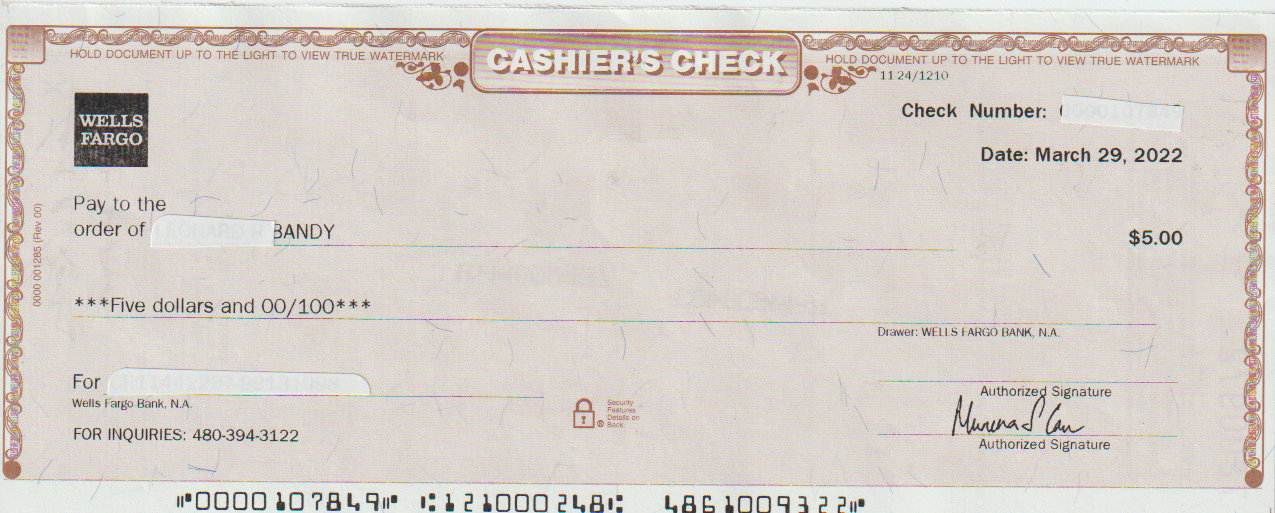
Practical tips that actually matter
Go to a branch you actually bank at. Some tellers are slower and less familiar with cashier's check procedures at branches where you don't have an account history. If you have a relationship with the branch manager or have been a customer for years, mention that when you arrive. It can speed things up because the staff already has your file pulled up and knows your typical transaction patterns. Write the exact payee name on a piece of paper before you go to the branch. Don't try to spell it out from memory when the teller is watching the clock. "Robert Q. Williams III" is easy to mangle if you're reciting it under pressure. Having it written down eliminates that risk entirely. If you need multiple cashier's checks, ask about bulk pricing. Wells Fargo doesn't advertise this, but some branches will reduce or waive the fee per check if you're ordering three or more at the same time. It doesn't happen everywhere, and the teller may not bring it up, so you have to ask. No harm in asking.
Be aware that Wells Fargo's mobile check deposit feature has limits. If you receive a cashier's check and try to deposit it through the app, your account may have a monthly deposit cap that varies by account type. Regular checking accounts typically have lower limits than premium accounts. Check your deposit limits in the app under account details before you rely on mobile deposit for a large cashier's check. Hitting the limit mid-process means the deposit gets rejected and you have to go to a branch anyway, wasting the time you were trying to save. The whole process from walking in to walking out with the check usually takes between fifteen and forty-five minutes at a typical Wells Fargo branch, assuming you have your ID, the correct funds, and the right payee information ready. It's longer if you have a new account, a complex transaction, or a busy branch during peak hours like Tuesday mornings around noon.


