So you want to make sense of how Wells Fargo actually works now
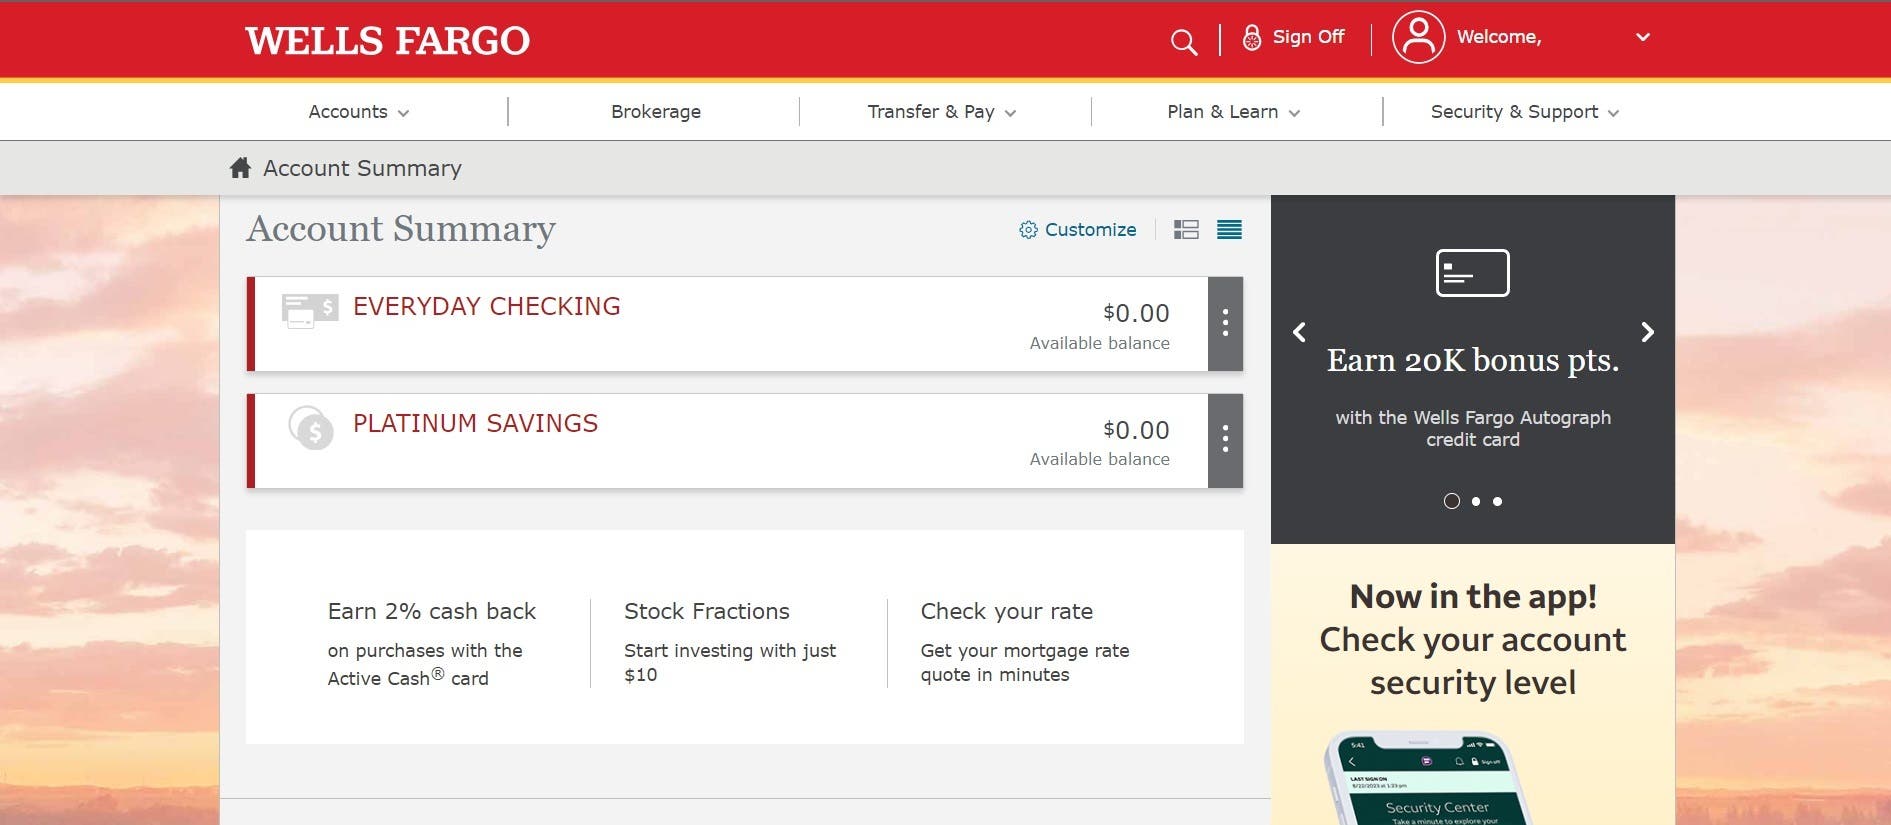
The whole landscape has shifted. Online banking used to be a chore you logged into once a month to check your balance. Now it's your primary financial hub, and a lot of people are just fumbling through it without understanding what half the features do. I've spent years watching this transition from the inside, dealing with customer complaints, compliance headaches, and the occasional system outage that leaves thousands of accounts temporarily locked. This is what I've learned. Let's start with what actually exists today. Wells Fargo offers a suite of digital tools — mobile check deposit, account linking through Plaid, automated savings routines, credit monitoring, Zelle, and their newer products like the ClearSavings account and active benefit checking. The issue is that most customers use maybe 15 percent of what's available because they don't know where to look. The app itself is cluttered. I've told people to use the search function inside the app instead of hunting through menus, and it cuts the navigation time significantly. Here's the thing that trips people up. Account aggregation. When you link external accounts or use Wells Fargo's smart budgeting tools, you're giving them permission to pull data from other financial institutions. That's convenient until your credit union goes offline for maintenance and your dashboard shows stale numbers for three days. I had a client this way back in early 2024 who panicked because his linked investment account showed a zero balance. It wasn't zero. The API endpoint had changed and the refresh token had expired. He needed to reauthorize the connection through the security settings, not call the branch. I walked him through the exact steps — Settings, Accounts & Payees, the external account, Edit, then Reauthorize. Took him five minutes. He'd been stressed for two days over a metadata issue.
The Zelle integration is another area where people make unnecessary mistakes. They send money to someone who isn't registered and then wonder why it bounces. Or they set up recurring payments to themselves and then can't cancel because the cancel button is buried under a menu that Wells Fargo moved in a recent update. My workaround for recurring Zelle payments — don't set them up through Zelle. Set them up as automatic transfers inside the account itself. They give you actual control over stopping them. Safety and fraud detection is where the bank gets complicated. Their fraud algorithm is aggressive. I've seen legitimate purchases — travel bookings, large medical bills, even grocery runs at expensive stores — get flagged and the card temporarily frozen. The hold times for reactivation vary. Sometimes it's two minutes through the app's fraud center. Sometimes it's a three-hour wait on the phone. There's no clear pattern. What helps is setting travel notices before you leave and using the app to report the fraud rather than calling. The in-app resolution path is almost always faster, though the options are narrower. If you need to dispute a charge formally, you'll eventually get transferred to the claims department anyway, so just do it over the phone from the start. Saves a round trip.
The things nobody warns you about
Direct deposit timing is one. Wells Fargo advertises early direct deposit, which typically means one to two days before the official pay date. That sounds great until your employer uses a processor that doesn't support same-day ACH origination. Then your "early" deposit comes on the same day as everyone else's, and you've budgeted around money you didn't actually have. Check with your payroll department about their ACH submission schedule before you rely on early deposit. Another counter-intuitive point. The overdraft protection transfer from savings sounds like a good safety net, but it costs $10 per transfer event if your checking balance hits zero. That's not cheap. A lot of people set it up automatically without realizing it, and then get hit with five or six transfer fees in a month because their checking account is a mess. It's cheaper to opt out entirely and just live within your balance. Or set up a low-balance alert at $50 instead. The alert costs nothing and actually prevents the problem. I also want to flag the mobile check deposit limits. They're not obvious in the app. Your first few months, you might be capped at $500 per deposit and $2,500 per day. After a verification period — usually 60 to 90 days of consistent activity — those limits can increase, sometimes to $5,000 per deposit and $15,000 per day. But there's no guaranteed timeline. I've seen some accounts stay capped indefinitely, especially if there was a prior discrepancy with a deposited check. If you regularly handle large checks, call ahead and request a limit increase. Don't try to work around it by splitting deposits across accounts — that's flagged and can trigger a review.
Get the Full Details
What doesn't work and when to walk away
The chat feature in the app is hit or miss. Simple questions — balance checks, recent transaction lookups, form requests — get answered instantly by the bot, which is fine. Complex issues like wire transfer disputes or account opening errors get routed to a human agent who often can't help without a callback from a specialist. Those callbacks can take 24 to 48 hours. If you have an urgent matter, skip the chat and go straight to the phone line. The hold times are worse but the first-line agent has more tools available. Branch appointments are another area where expectations need management. Most branches won't see you for anything beyond basic deposits and withdrawals without an appointment, and booking one through the app can mean waiting several days depending on your location. I recommend scheduling the appointment at the same time you schedule whatever meeting you need — don't assume you can just show up and get help with account changes or loan questions. One final thing. The credit score tool in the app pulls from VantageScore, not FICO. They correlate closely but can differ by 20 to 40 points depending on your credit history. If you're shopping for a mortgage or auto loan, lenders will use FICO. Don't treat the in-app score as gospel. Pull your actual FICO from a free source like Credit Karma or your card issuer's dashboard if you need the number that matters.