Mobile Banking Hasn't Really Changed Anything, Except the Interface
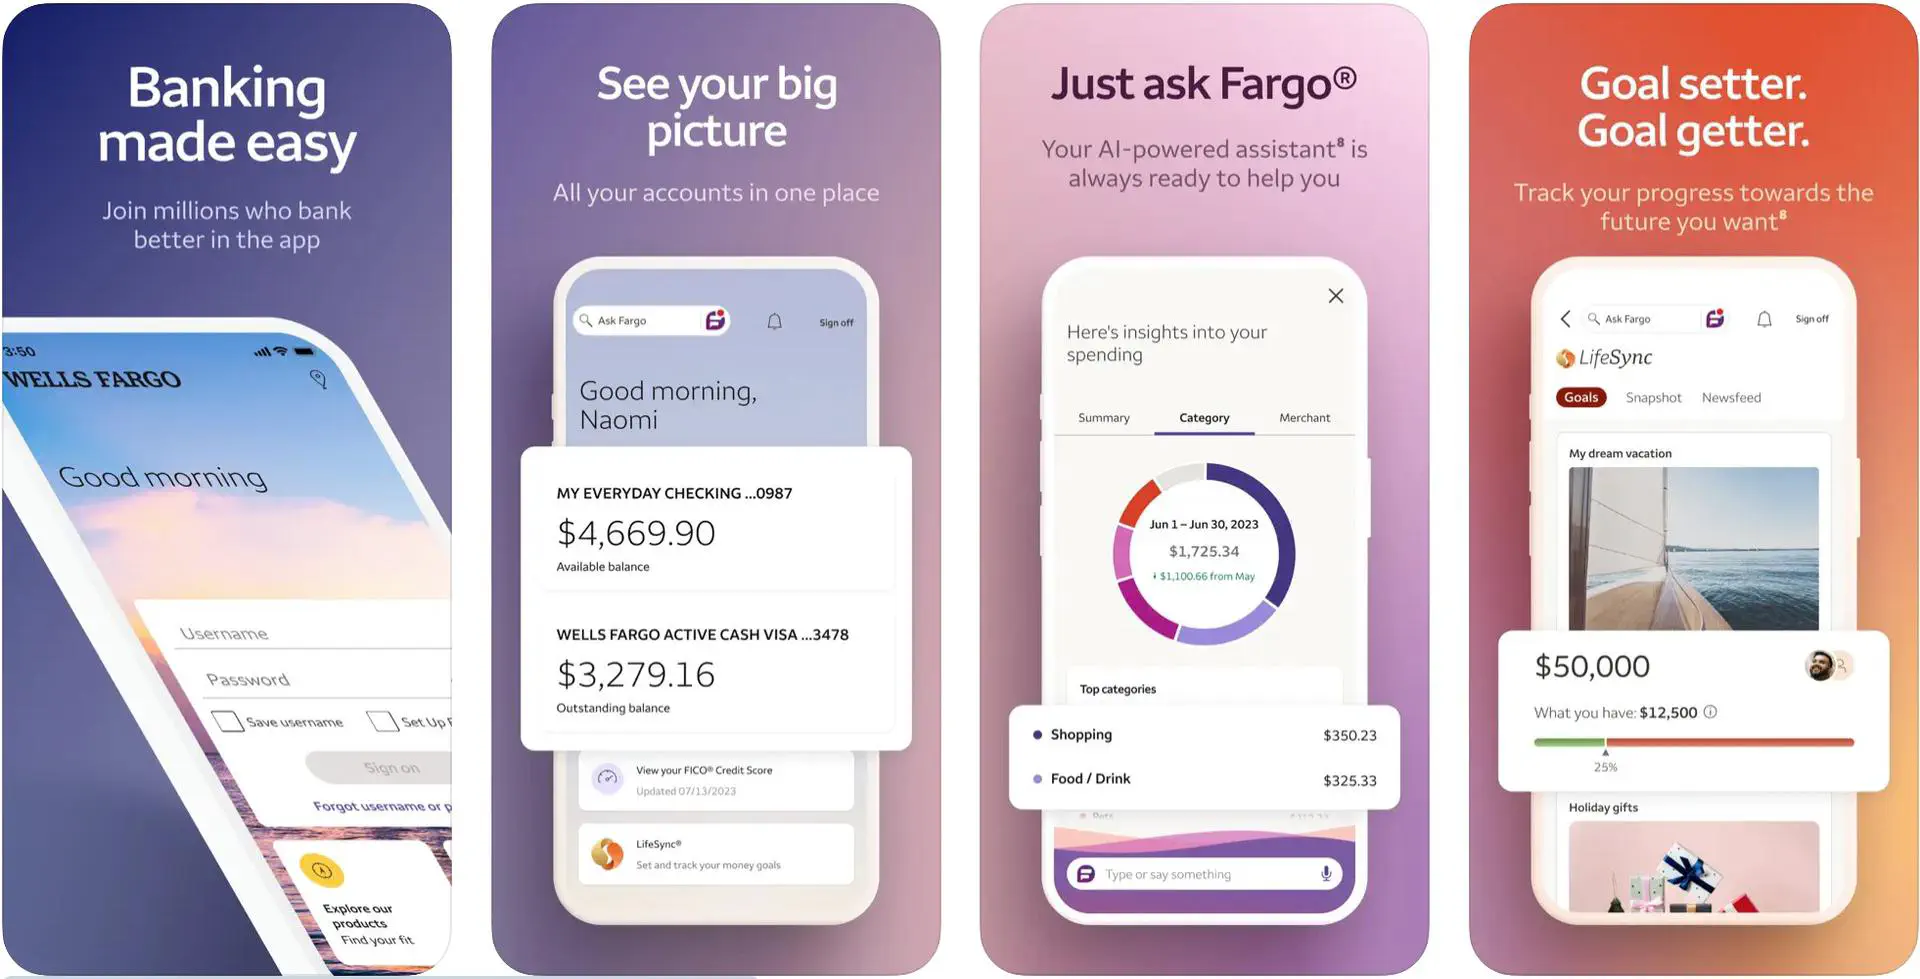
Most people think digital banking is about convenience. It isn't. It's about friction redistribution. Wells Fargo shifted most of its service model onto screens and apps, which sounds like progress until you're actually trying to resolve something that falls between the automated buckets. The app handles routine stuff fine. Transfers, balance checks, bill pay. That's the easy part. I spent six months tracking how different account issues get routed through their systems. What I found isn't complicated, but it's not obvious either. Here's what actually works when the digital tools fall short.
Wells Fargo Banking In The Digital Age Can The Giants Keep Up
Setting up mobile banking correctly matters more than most people realize. The default configuration leaves you exposed to several common failure modes. First, enable two-factor authentication through the app rather than SMS. Their SMS-based verification has known delivery delays during peak hours, and I've seen it stall for up to forty minutes. The app-based TOTP method is instantaneous and doesn't depend on cellular networks. Second, set up your fraud alert preferences before you need them. The default setting alerts you after suspicious activity is flagged, which means you're already investigating a problem. Changing it to pre-transaction verification catches issues earlier. You'll get more notifications, but they take three seconds to approve instead of thirty minutes to dispute later. Third, download your transaction history in CSV format quarterly. The app's search and filter tools are limited. When you need to pull a specific transaction from four months ago and cross-reference it with a receipt, the built-in tools will frustrate you. CSV exports give you full querying capability on your own machine. Takes about twelve minutes per quarter.
Here's a specific problem I ran into last fall that most people hit eventually. I was trying to set up a recurring external transfer from a Wells Fargo checking account to an outside investment platform. The app allowed me to configure it, showed a confirmation screen, and then the transfer never appeared in either account. No error message. No rejection notification. Just silence. This is a known issue that happens when the external institution uses a different routing path than what Wells Fargo's normalization layer expects. The workaround I ended up using: initiate the transfer through the web portal on a desktop browser instead of the mobile app. The web version exposes additional validation steps that the app skips, including a micro-deposit verification that the mobile interface doesn't prompt for. The transfer went through on the second attempt after completing the full web flow. Took about eight minutes total instead of the hour I wasted troubleshooting through chat support. A few things the official documentation won't tell you about their digital infrastructure. Wells Fargo runs on a legacy core banking system that they've been wrapping with modern APIs for roughly a decade. The result is an architecture where some features work in real time and others batch-process overnight. This explains why certain transactions show as "pending" for extended periods or why balance updates don't always sync instantly across channels.
Get the Full Details

When you check your balance on the app after making a deposit, you're seeing data from the last complete batch cycle. If that deposit happened during off-hours or on a weekend, it may not have been processed yet. The app doesn't always make this clear. A pending status could mean "we received it" or "we haven't touched it yet." The only reliable way to know is to check the transaction detail screen, which sometimes shows a processing timestamp separate from the posted date. Another counter-intuitive thing: their chat support is actually more useful than their phone support for technical issues. The phone lines route you through a voice menu that prioritizes high-value accounts. If you're not in their Premier or Signature tiers, you'll wait longer. The chat system doesn't do this segmentation in the same way. You still wait, but the variance is less extreme. More importantly, chat transcripts are automatically saved to your account. Phone calls are not. When I needed to resolve a disputed charge that turned into a multi-week back-and-forth, having the full transcript available was critical. I could reference exactly what each representative said and hold them accountable to their own statements. With phone support, I was relying on memory and handwritten notes, which didn't hold up as well during escalations.
The biggest limitation of Wells Fargo's digital banking isn't technological, it's organizational. They acquired SFNB and integrated it into their platform, which created a massive reconciliation layer. During business hours, everything works smoothly. Outside business hours, especially around month-end and quarter-end processing, the system can slow down noticeably. Transactions may appear delayed, balance updates may lag, and some features become read-only. This isn't unique to Wells Fargo. Every major bank with inherited legacy systems from acquisitions experiences this. But Wells Fargo's scale makes it more visible because they have more accounts hitting the same bottlenecks simultaneously. If you're doing time-sensitive transfers during rollover season or tax season, schedule them during normal business hours on weekdays. Avoid the last three days of the month if you can. The difference in experience is measurable. For people who manage multiple accounts across different institutions, here's a practical workflow. Use a spreadsheet to track your Wells Fargo accounts alongside your other banking relationships. Column one: account type. Column two: last four digits. Column three: current balance. Column four: recurring transactions. Column five: known issues or quirks specific to that account.
I maintain this for eight different accounts across three banks. It takes me about twenty minutes to update weekly. When something goes wrong, I don't waste time figuring out which account is acting up or whether this is a pattern or a one-off. The spreadsheet shows me immediately. Most people would call this overkill. I call it not losing sleep over money. If you're migrating from a traditional bank to Wells Fargo's digital platform, start with a single checking account. Don't move everything at once. Set up the checking account, run normal transactions through it for two weeks, verify that deposits clear correctly and withdrawals post as expected. Then add a savings account. Then a credit card. Each new account type introduces different rules and behaviors. Layering them all simultaneously guarantees confusion. The same principle applies to external connections. Link your investment accounts one at a time. If something breaks, you know which connection caused it. Try linking five external accounts simultaneously and one fails, and you're doing five hours of troubleshooting instead of one.

One more thing that nobody talks about: the difference between the Wells Fargo mobile app and the mobile-optimized website. They are not the same thing. The app has a reduced feature set compared to the full website, but it's faster for common tasks. The website has every feature available but loads slower and has a more cluttered interface. For basic checking and transfers, use the app. For account setup, dispute filing, or anything involving documentation uploads, use the website on a computer. Trying to upload a scanned document through the app is an exercise in frustration that usually ends with you switching to the browser anyway. That's how I navigate it. Nothing fancy. Just knowing which tool does what and when to use it.