Understanding Your Daily Withdrawal Ceiling
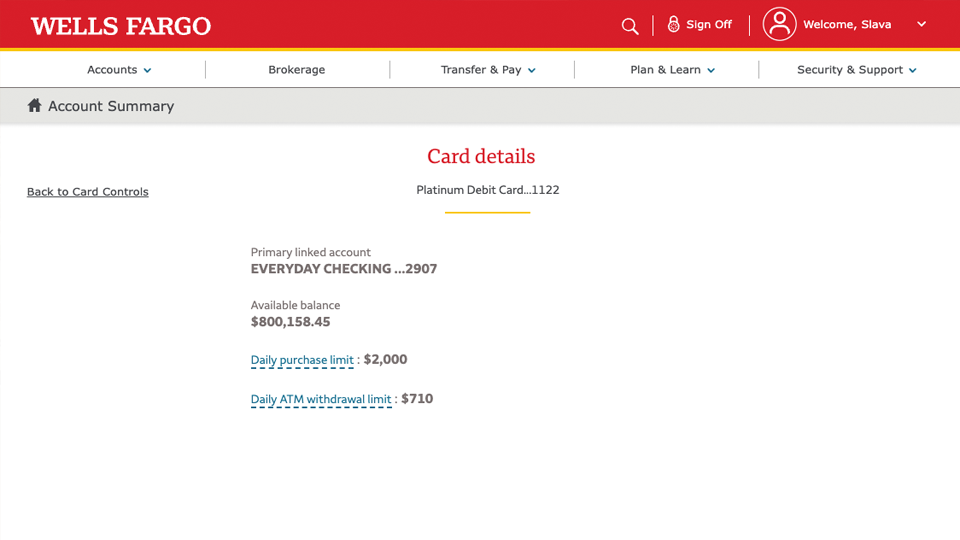
Most people treat their ATM limit like a suggestion until they're standing in front of a machine that won't let them pull out enough cash for something urgent. I learned this the hard way back in 2019 when I was traveling through rural Montana and needed about $800 in cash for a cabin rental that didn't accept cards. My default daily withdrawal limit was sitting at $700. The machine ate my card anyway before flashing the error code. I ended up spending forty-five minutes on hold with customer service, jumping through identity verification hoops, and still couldn't get a temporary limit increase approved fast enough. The place accepted checks as a backup but charged a two percent fee. That $800 trip wound up costing me roughly $16 extra just because I hadn't thought about my limits ahead of time. Wells Fargo sets your daily ATM withdrawal limit based on a combination of your account type, your banking history with them, and the verification level on your profile. The standard starting range for most checking accounts sits between $500 and $1,000 per day. Premier Accounts and Performance Complete checking customers typically start higher, somewhere in the $1,500 to $2,500 range. This isn't arbitrary. Banks are managing fraud exposure and operational risk, and a higher limit means more money at stake if your account gets compromised. The key detail nobody mentions upfront is that the ATM withdrawal limit is separate from your overall daily spending limit. Your card can simultaneously have a $1,500 ATM cap and a $3,000 purchase limit. These are tracked independently in their systems. When you're budgeting around cash needs, you can't conflate the two numbers.
I found this out after trying to withdraw $2,000 at a branch ATM once. The transaction declined with a message that referenced my purchase limit rather than my ATM limit. It took me two calls to understand why. The system was cross-referencing my total available daily spend, not just the cash portion. Wells Fargo's approach here is actually defensive in a useful way, since it prevents someone from bypassing an ATM cap by running the same amount through a point-of-sale terminal and then withdrawing the refund as cash.
How to Check and Adjust Your Limit
The fastest way to see your current limit is through the mobile app. Go to Account Details, select your checking account, and look for Daily Limit or Withdrawal Limits under Account Settings. If that section is grayed out, you're probably on an older profile version that requires a branch visit to modify. I hit this wall last year when I upgraded from a standard to a Premier account and expected my limits to shift automatically. They didn't. The system flags the new account tier for manual limit review within the first thirty days. You can request an increase through the app, through online banking, or by calling customer service. App-based requests usually process within minutes to a few hours during business days. After-hours submissions queue until the next business morning. A branch visit is the slowest option unless you already have an established relationship with a relationship manager who can push the change through immediately. There's a trick most people miss. Instead of asking for one large temporary increase, ask for a permanent limit bump if your situation is ongoing. Temporary increases expire anywhere from twenty-four hours to thirty days depending on how you request them. If you need consistent access to larger cash amounts, a permanent adjustment prevents you from refreshing the same request repeatedly. I switched a friend to this approach after watching him log into the app every Friday for three months to request a temporary bump for rent day. He never noticed he could just set it once and be done with it.
Get the Full Details

The Hidden Constraints Nobody Talks About
Your posted daily limit is only half the picture. The other half is the per-transaction cap, which is almost always lower. A lot of Wells Fargo ATMs impose a single transaction ceiling of $1,000 or $1,500 regardless of what your daily maximum allows. This means you can technically withdraw your full daily allowance, but you have to do it in multiple passes. The machine will dispense the bills, you cancel the transaction, and run it again until you've hit your limit. Some people find this awkward at public ATMs. I've done it standing next to someone waiting in line behind me. It works, but it's not elegant. Another obscure constraint is the weekend and holiday throttling. Wells Fargo, like most national banks, reduces ATM withdrawal capacity on non-business days. A $2,000 daily limit might effectively drop to $1,000 on a Saturday. This isn't written anywhere prominently on the website. It's a backend routing decision tied to how fraud monitoring systems operate over weekends when staffing is lighter. I discovered this when I tried to pull a large withdrawal on a Saturday to cover a Sunday payment and got cut off halfway through. Calling Monday morning confirmed the weekend throttle. Nothing I could do about it except plan around it. The third thing that catches people off guard is out-of-network surcharge stacking. Wells Fargo reimburses up to $5 in ATM fees per month on certain account types, but that reimbursement doesn't raise your limit. It just softens the blow. If you're hitting your withdrawal maximum and paying surcharges at unrelated machines, you're burning both your cash allowance and your fee budget simultaneously. The math adds up fast if you're doing this weekly.
What Actually Happens When You Hit the Limit
The machine declines the transaction. That's it. No warning, no partial dispensing, no holding the money in escrow until tomorrow. It just stops. I've seen people panic at this point and try multiple times hoping the system will behave differently on the second attempt. It won't. Each decline is logged, and repeated failed attempts can trigger a temporary security hold on your card. I triggered this once by getting frustrated and retrying five times in under a minute. My card was locked for sixteen hours. Customer service said it was an automated fraud pattern flag, not a punishment, but the result was the same: I was stranded without access to my own money. If you need more cash than your limit allows and can't get a quick increase, your options are limited. You can request a same-day deposit to temporarily boost your available balance, but that doesn't change the withdrawal cap. You can use a debit purchase at a point-of-sale terminal and request cash back, though most retailers cap cash back at $100 or $200. You can go to a branch with ID and request a cashier's check or over-the-counter withdrawal, but branches don't always have large bills readily available and may require managerial approval for amounts above $2,500. I prefer the cashier's check route for amounts over $1,500. It takes about ten minutes inside the branch, costs nothing, and bypasses the ATM limit entirely. The tradeoff is that you have to physically go to a branch during business hours, which defeats the convenience of having an ATM nearby. But if you're already doing things manually, you might as well use the channel that gives you the most money at once.
When Limits Break Completely
There are scenarios where Wells Fargo's limit framework simply doesn't apply. New accounts in their first ninety days often run on a probationary limit that's significantly lower than your account type should warrant. I've seen cases where a Premier Checking customer started with a $300 daily ATM cap because the system hadn't yet verified their deposit history. This resolves itself after the qualification period, but it leaves people confused and sometimes embarrassed when their card gets declined repeatedly. Accounts with recent fraud activity or chargebacks also get manually pulled down. This isn't algorithmic. It's a human decision, and it sticks until someone reviews the account and lifts it. The review process can take three to five business days. During that window, you're operating on a skeleton limit regardless of what your account dashboard displays. And then there's the international angle. If you're traveling outside the United States, your Wells Fargo ATM withdrawal limit often drops to a fraction of your domestic maximum. I saw my limit go from $2,500 down to $500 while in Mexico. The reason is straightforward: cross-border transactions carry higher fraud risk, and Wells Fargo compresses exposure aggressively. You can request a travel notification, but that doesn't restore your limit. You have to call customer service separately and ask for an international limit increase, which they may or may not grant depending on your account standing.
Knowing these edge cases ahead of time saves you from the kind of frustration I spent an entire afternoon dealing with in Tijuana. A quick phone call before you cross the border, even if you don't think you'll need cash, can prevent a humiliating situation at an ATM where you're trying to withdraw money for a ride home and the machine won't cooperate.