Understanding Pay Frequency Options
Most people never really think about their paycheck schedule until something goes wrong. You get used to seeing money hit your account every two weeks or every seven days, and you budget around it without questioning whether the system is actually working for you or against you. That's fine until your bills don't line up the way they should.Weekly And Biweekly Showdown Which Pay Schedule Truly Maximizes Your Earnings And Lifestyle
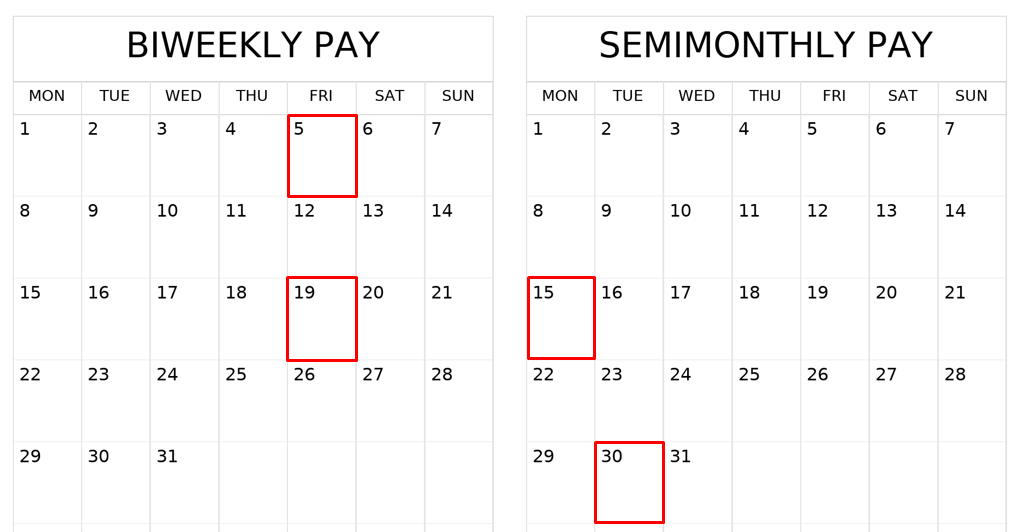
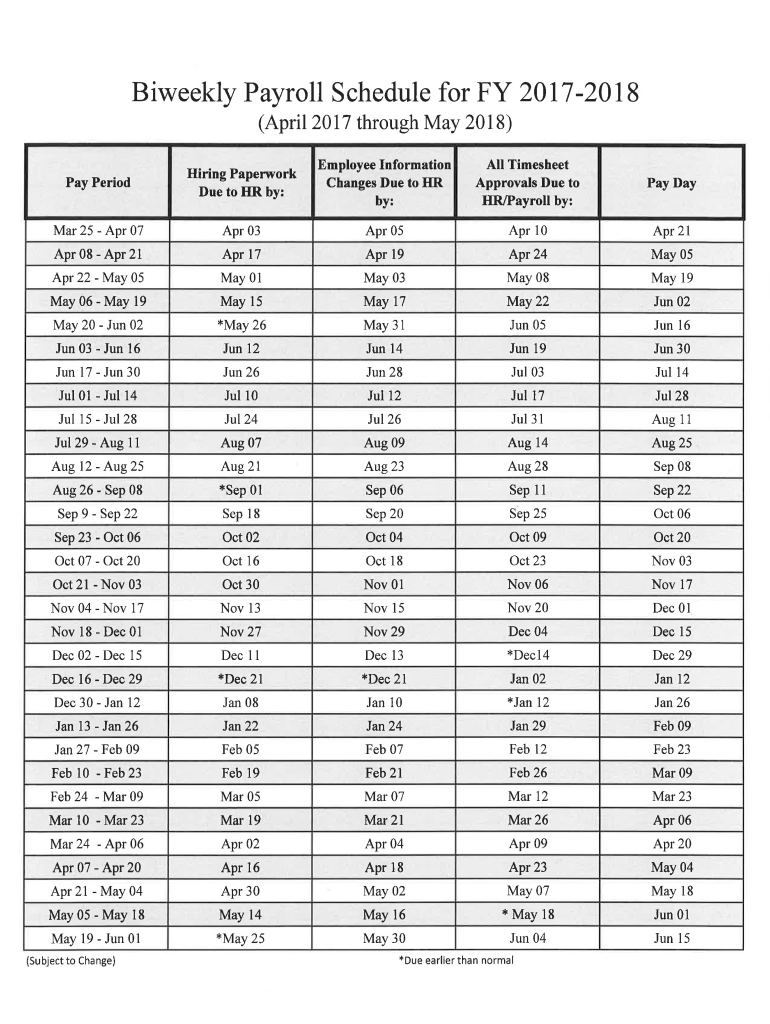
The core difference between these two systems is exactly what the names imply: one pays you every seven days, the other every fourteen. But the math underneath is where things get interesting and where most people make mistakes. A year has 52 weeks, which means a weekly schedule produces 52 paychecks. A biweekly schedule produces 26 paychecks, but because 52 divided by 2 equals exactly 26, you actually get one extra paycheck period every year—usually in February or August depending on how the calendar falls. That extra paycheck isn't free money in the sense that you didn't work for it, but it does create a brief window where your cash flow jumps significantly. I used to work in operations where we handled payroll for about 400 employees across multiple pay frequency options. One summer, I had a manager come into my office completely stressed because her rent was due on the 15th and her biweekly paycheck had just come through on the 13th, but she had accidentally spent what she thought was her regular amount on an extra expense because she'd misread her calendar. She was two weeks out from her next check and short about eight hundred dollars. We ended up setting her up with a simple automated rollover budget in the company's payroll system that split each deposit into a checking account and a hold account, so she'd always have at least one full paycheck buffer sitting there whenever her rent hit. It took about twelve minutes to configure and saved her from that scramble permanently. Here's something most payroll guides won't emphasize enough: the weekly schedule actually creates more consistent budgeting friction for people on fixed monthly obligations. Think about it. If your rent is due on the first and you get paid weekly, your payday drifts through your entire calendar month over the course of a year. Sometimes you'll get paid on the 28th of the month before rent hits, sometimes on the 3rd after rent has already gone out. That drift means you're constantly recalculating how much you can actually spend in any given week. With a biweekly schedule, your paydays land on the same weekdays every time—every other Friday, say—which means your income events are far easier to lock into a recurring budget.
Counter-intuitive point: The biweekly schedule typically leaves you with more usable liquidity during the months when calendar alignment works in your favor. Because you only get 26 deposits instead of 52, each individual deposit is larger, which makes covering big monthly expenses like insurance premiums or property taxes less awkward. With weekly pay, you're managing smaller inflows that require more frequent transaction decisions, and the mental overhead of tracking 52 deposits per year is real. People who choose weekly pay often underestimate how much cognitive bandwidth they waste constantly repositioning money that arrived forty-eight hours ago. The one area where weekly pay genuinely wins is emergency cash flow. If you lose your job or an unexpected expense hits mid-cycle, waiting fourteen days for your next deposit is a real problem. With weekly pay, you're only seven days away from relief. I've seen this play out with hour workers who switched from biweekly to weekly specifically for this reason, and they reported feeling noticeably less anxious about the rhythm of their income even though the total annual earnings were identical. Another thing people miss: tax withholding behaves differently between the two schedules on paper, and your employer's payroll system may calculate your effective tax rate slightly differently because the periods have different lengths. Some employers round to the nearest whole day when computing weekly withholding tables versus biweekly tables, which can shift your take-home by fifteen to thirty dollars per check depending on your bracket and filing status. It's not a huge amount, but over a year it adds up enough that people who are meticulous about their tax planning will want to check their W-4 settings when switching frequencies.
There's also a behavioral component that nobody talks about. Weekly pay creates a pattern where you see money arrive frequently, which psychologically makes spending feel more normalized. Biweekly pay creates longer gaps between deposits, which forces you to sit with your money a bit longer before it replenishes. For people who struggle with impulse spending, that two-week gap can actually be a feature rather than a bug. I know someone who tried the weekly schedule because her friend swore it was better for cash flow management, and she ended up spending more each month because she never felt the pinch of waiting. She switched back to biweekly within six weeks. If you're trying to decide between the two and your employer offers both, the decision really comes down to your expense rhythm and your personality type. Fixed monthly bills with large amounts? Biweekly tends to serve you better. Variable income or frequent emergencies? Weekly might reduce your stress. Run a simple test for thirty days: track every dollar that comes in and goes out under your current schedule, then map out what your next twelve months would look like under the alternative. Most people discover in that exercise that their actual difference in total earnings is zero, and the real question is which cadence matches how their life works. The one scenario where neither option is ideal is if you're a contractor or freelance worker getting paid irregularly. In that case, forcing yourself onto a standard biweekly or weekly budgeting rhythm and treating each payment as a deposit into a dedicated operating account usually works better than trying to match income to expenses week by week. Irregular income plus a rigid pay schedule creates more anxiety than it solves, and the workaround most people find helpful is simply opening a separate business checking account, routing everything there, and paying yourself a fixed amount on a schedule you control rather than letting the employer's payroll system dictate your rhythm.
Get the Full Details

Bottom line: neither schedule maximizes your total earnings because your gross pay stays the same. What changes is your cash flow predictability, your mental bandwidth for managing money, and your exposure to timing risk. Pick the one that matches your actual behavior, not the one that sounds optimal on paper.