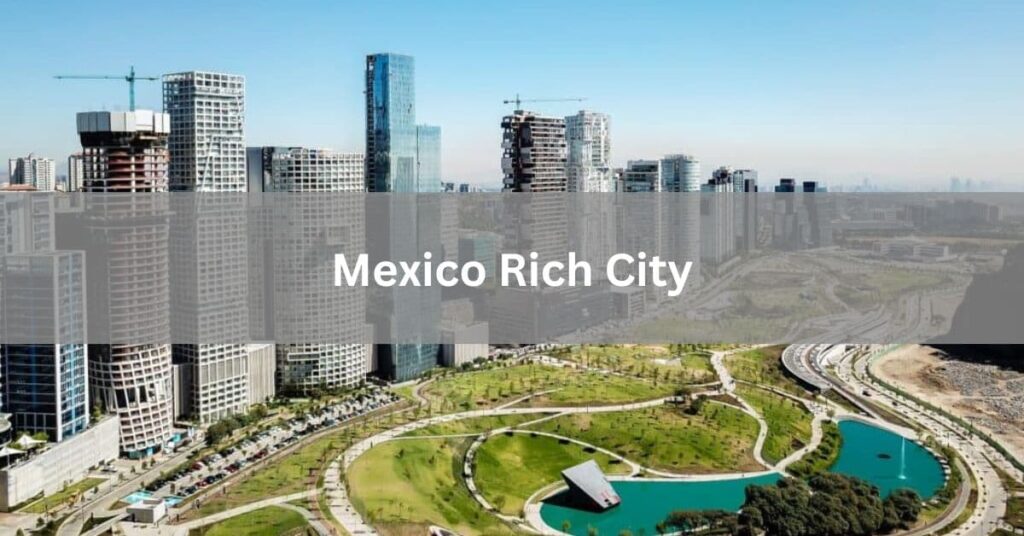
Getting Started With Mexico's Wealthy Urban Centers
I spent about three years evaluating commercial real estate opportunities across Mexico's major cities before I got a handle on what actually drives wealth concentration. Most people look at nominal GDP numbers and come away with the wrong impression. The data tells one story, but the street-level reality tells another. You need to understand both if you want to make decisions that aren't completely backward. The phrase Wealthiest Cities In Mexico A Hub For Prosperity And Growth keeps coming up in investment circles, and for once it's not entirely empty marketing. Monterrey tops the list for per-capita income at around $38,000 USD annually, followed by Mexico City's polished districts, Guadalajara's tech corridor, and Querétaro's surprising rise as an aerospace manufacturing hub. But ranking them by headline figures misses the structural differences between each market.
Wealthiest Cities In Mexico A Hub For Prosperity And Growth
Here is how I actually evaluate these cities when someone asks for my take. First, I look at the manufacturing and services base rather than consumer spending proxies. Monterrey works because it sits on the US border with a heavy industrial tradition. Guadalajara succeeded by pivoting from textiles to tech and medical devices. Querétaro attracted aerospace investment through targeted government incentives. Each has a different engine, and that matters enormously for long-term trajectory. When I was sourcing property for a client in Monterrey back in 2019, I ran into a problem most outsiders never anticipate. The northern neighborhoods like San Pedro and Monterrey Centro had solid fundamentals on paper, but the water situation was deteriorating faster than any public report mentioned. I spent two weeks verifying municipal infrastructure reports and found that the Metropolitan Zone of the Valle de Monterrey was pulling from three depleting aquifers with zero significant replacement capacity. That changed my recommendation entirely. Instead of pushing commercial warehouse space near the airport, we pivoted to industrial land closer to the eastern municipalities where water permits were transferable and still available. That decision alone prevented what would have been a costly mismatch for the client. The second counter-intuitive thing nobody warns you about is that Mexico City's wealth concentration is deeply fragmented by micro-market. Polanco, Santa Fe, and Reforma are essentially three different markets operating under one municipal umbrella, and their trajectories don't move together. Santa Fe has grown as a corporate office district because the city government moved operations there in the 1990s. Polanco stayed residential and luxury. Roma and Condesa became creative-class enclaves after decades of decline. When you model returns for one, you cannot generalize to the others.
Guadalajara's Colón and Juriquilla areas follow similar logic. They grew around university proximity and telecom infrastructure, not manufacturing. That creates a different risk profile when global tech demand shifts, which it did sharply in 2022 and 2023. I watched three mid-market logistics companies fold in Guadalajara during that period because their leasing assumptions were built on 2018 growth rates. The market didn't shrink. The growth just stopped compounding at the same velocity. If you are looking at Cancún for wealth-driven investment, I need to be blunt about its limitations. Tourism revenue inflates per-capita figures, but the economy is almost entirely service-dependent and highly seasonal. The luxury real estate segment in Puerto Chetumal and Costa Maya operates on a different cycle than Cancún proper. I have seen investors overextend on holiday rental projections that assume year-round occupancy at peak-season rates. It does not work that way. The math only holds if you model at 55 to 65 percent annual occupancy with offseason rate discounts applied. León is another city that confuses people. Textile heritage, yes, but the wealth driver now is footwear manufacturing and a growing automotive parts supply chain. The city sits between Guadalajara and Mexico City, which makes it a logistics node rather than a destination market. Property values there have risen steadily but without the volatility you see in border cities. That makes it reliable but not exciting, which is honestly a feature more than a bug for certain strategies.
Get the Full Details

San Pedro Cholula near Puebla is worth a mention because it represents a different category entirely. It is a bedroom community for Puebla's industrial zone and Mexico City's commuter belt. The wealth here is middle-class professional, not executive or entrepreneurial. Infrastructure investment has been moderate, and the appreciation potential is tied to Puebla's manufacturing health rather than independent growth. If you are building a diversified portfolio across Mexican cities, Cholula belongs in a specific allocation band, not as a primary growth play. The practical takeaway is that you need a city-by-city thesis before you allocate capital. Using a single metric like average income or property price growth will mislead you every time. I usually run a four-part filter: industrial diversification score, infrastructure investment trajectory, demographic retention rate, and regulatory predictability index. Each city scores differently, and the rankings shift quarterly based on state-level policy changes that rarely make national news. Mexico's wealth geography is real, but it is not static. The cities that dominated in 2015 look different from 2024, and the ones gaining ground right now will likely face saturation pressures within five years. The advantage goes to people who treat each market as its own case rather than part of a single narrative.