What You Actually See When People Post Photos Of That House On Silver Ave
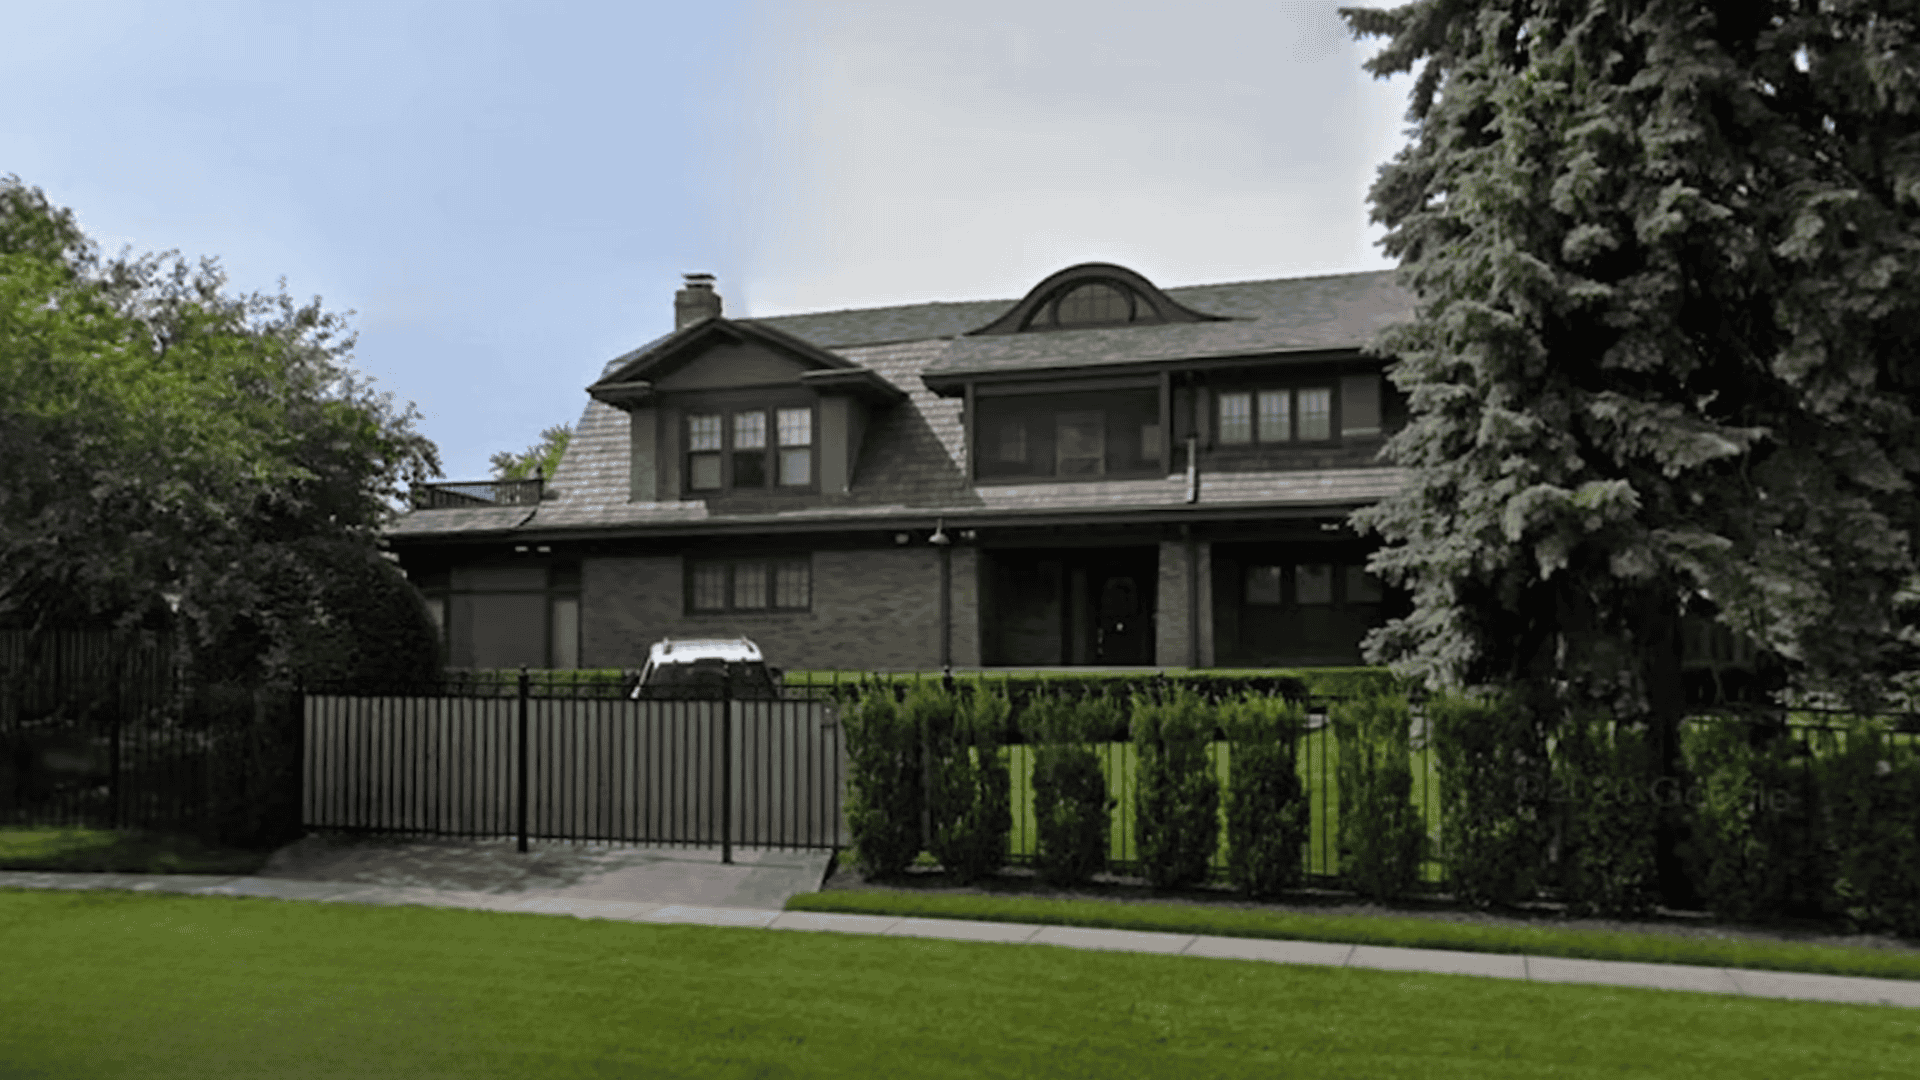
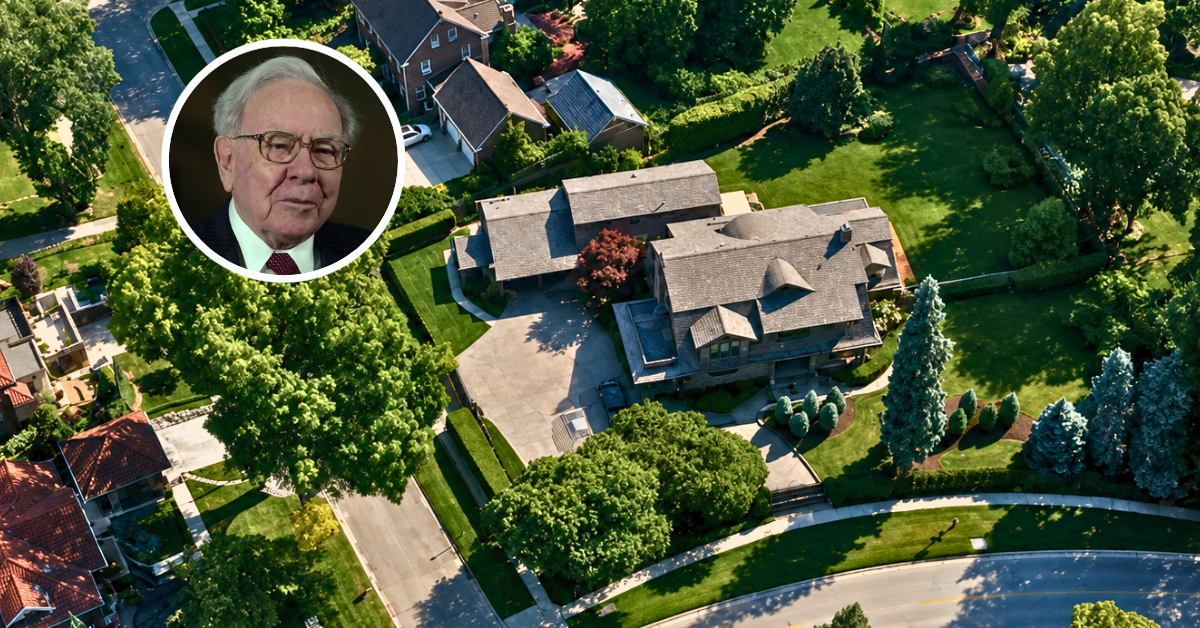
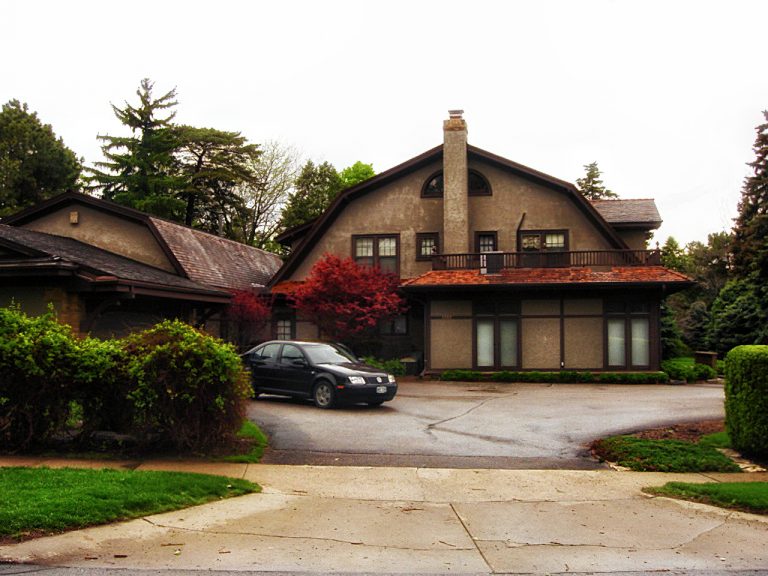
The street in question is West Silver Avenue in Omaha. The house itself is a two-story limestone structure, roughly 1400 to 1500 square feet, built sometime in the mid-twentieth century. It sits on a corner lot with a modest front lawn, a driveway that accommodates maybe two cars, and a porch that looks like any other porch you would drive past without noticing. There are no fountains. There are no gates. The paint is a neutral tone. Neighbors have said for decades that the landscaping is routine, trimmed but not elaborate. The reason this becomes a topic is that the person who lives there is Warren Buffett. The address is publicly known. Real estate records are accessible. So when a photo circulates of that front yard, it is always framed as a statement about his philosophy. Which is fair, because the philosophy is real. The framing tends to get sloppy, though.
Warren Buffetts Front Yard A Peek At His Omaha Home And The Frugal Philosophy Within
The house was purchased in 1958 for about thirty-one thousand dollars. He has lived there since. He bought it while making his first partnership returns and before Berkshire became the vehicle people associate him with today. The purchase price is worth noting because it anchors the rest of the story. This was not a late-in-life declaration of modesty. He chose this house at a point where he could have bought something larger and more conspicuous, and he did not. The front yard itself does not convey much information on its own. The grass is cut. The edges are clean. There is a sidewalk and a couple of mature trees. If you stand on the street and look at it, you are looking at a normal middle-class suburban yard. The signal is not in the landscaping. The signal is in the fact that the house has not been expanded into a compound, that the garage has not been turned into a wing, that the property has not been subdivided or traded up to something that signals status in the Omaha market.
How The Frugality Actually Works In Practice
Buffett’s capital allocation style mirrors the house. He avoids leverage unless the balance sheet can absorb a severe shock. He prefers businesses that generate cash without requiring constant reinvestment. He holds positions for long periods and ignores quarterly noise. The front yard is a visual shorthand for that discipline, but the discipline is in the financial behavior, not the property line. One thing most summaries miss is the role of transaction costs and tax drag. Staying in the same house for over six decades is not just a lifestyle choice. It is a tax event. Every time you sell a primary residence in the United States, you face capital gains exposure unless you qualify for the Section 121 exclusion, which provides up to $250,000 for single filers and $500,000 for married couples filing jointly if you have owned and used the home as your principal residence for at least two of the five years preceding the sale. Buffett meets that easily. But the real advantage is the basis step-up at death, combined with the fact that he has never needed to liquidate appreciating assets to fund daily expenses. The house is paid off. The carrying cost is low. The property tax in Omaha is moderate by national standards. There is no mortgage payment dragging against his liquidity. When I review portfolios for clients who want to replicate this kind of behavior, the first mistake I see is mistaking the symptom for the mechanism. People focus on the address and assume the lesson is about living small. The lesson is about optionality. A paid-off house in a low-cost market frees up cash flow. Free cash flow lets you wait for asymmetric opportunities instead of taking mediocre ones because you need income in the short term. That is the part that actually matters for investing.
Get the Full Details

The Edge Case I Ran Into When Someone Tried To Use This As A Checklist
A client once asked me to model what would happen if he sold his larger suburban home, bought a smaller place near his office, and moved the difference into a concentrated position in a single stock he admired. On paper it looked rational. The math showed higher expected return. The problem was timing and liquidity drag. He needed to close on the new house in a seller’s market while waiting for his current home to sell. The escrow timeline overlapped with a market drawdown. He was forced to take a discount on his existing property to meet his closing date. The concentrated position he bought dipped twenty-two percent in the following quarter. The savings from the smaller house did not offset the transaction costs and the temporary illiquidity. He ended up worse off than if he had stayed put. The workaround was to delay the move by nine months, rent briefly, and let the market pressure ease. He avoided the fire sale. The concentrated position was entered at a better price. The lesson was not that the strategy was wrong in theory. It was that the strategy assumed frictionless execution, which never exists in practice.
What Beginners Get Wrong About This Philosophy
The first common error is treating frugality as a virtue in itself. It is not. Frugality is a means to preserve optionality and reduce dependency on external funding. If you cut expenses but also cut your earning power or your ability to take intelligent risks, you have moved in the wrong direction. The Omaha example works because Buffett’s earnings capacity was already enormous. The constraint was not survival. The constraint was distraction. The second error is assuming that a small house guarantees good investment decisions. It does not. There are wealthy people in large homes who make excellent capital allocation choices, and there are people in small homes who blow their money on speculative positions. The correlation between square footage and financial competence is weak. What correlates more strongly is whether you can tolerate holding cash through boring periods and whether you can say no to opportunities that look good on the surface but carry hidden structural risks.
Where This Approach Fails
The frugality framework breaks down in markets with extreme cost inflation, particularly housing and healthcare. If you lock yourself into a low-cost base in a region where property values spike unpredictably, you may miss appreciation that could have funded later opportunities. Omaha has been relatively stable compared to coastal markets. That stability is part of why the strategy works there. It would not translate cleanly to a city where a modest home doubles in value every five years and then you regret not having captured that gain. The approach also fails when your income is highly variable. If you are a professional with irregular earnings, a low overhead lifestyle is helpful as a cushion, but it does not replace the need for diversification. Buffett’s businesses generate steady operating cash. Most individuals do not have that luxury. Staying overly lean in an income-uncertain environment can lead to underinvestment in career capital or skills development. The marginal return on spending for training or relocation is often higher than the marginal return on keeping that money in a low-yield account. If you are looking for a practical alternative, the better move is not to copy the house. It is to copy the behavior: minimize fixed costs, maintain liquidity, and allocate capital only when the margin of safety is clear. The front yard is a reminder, not a manual.