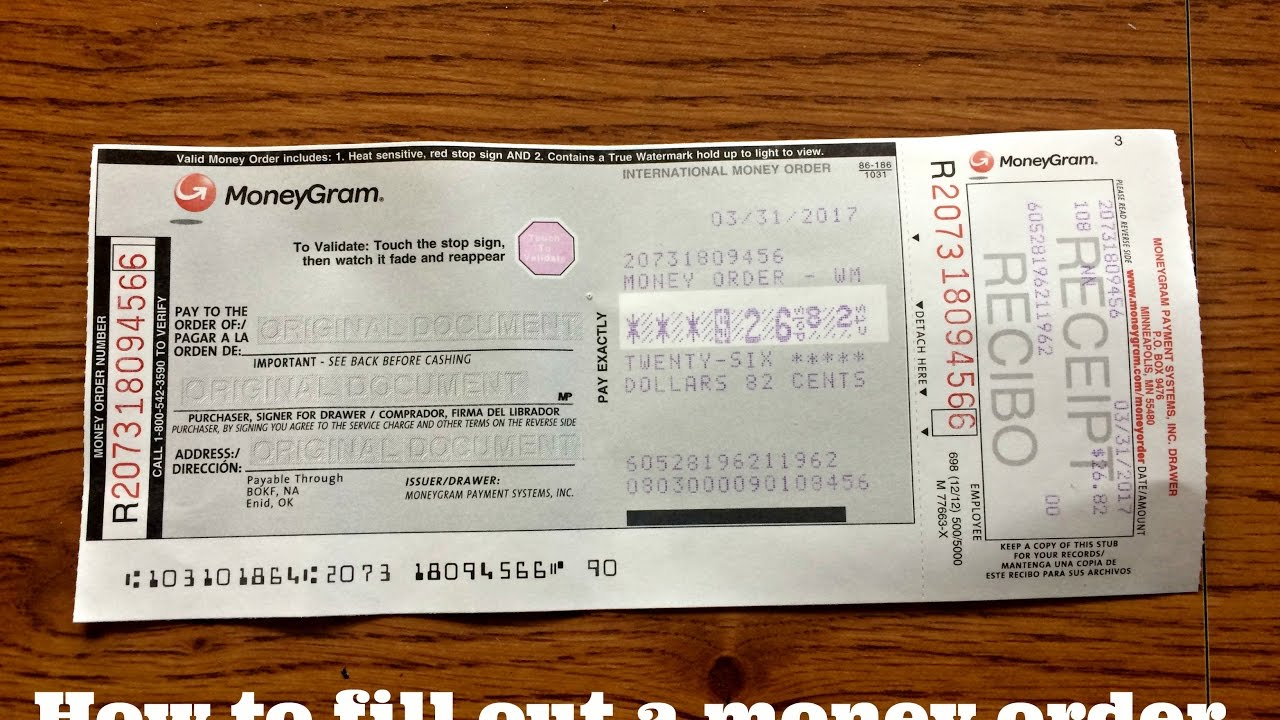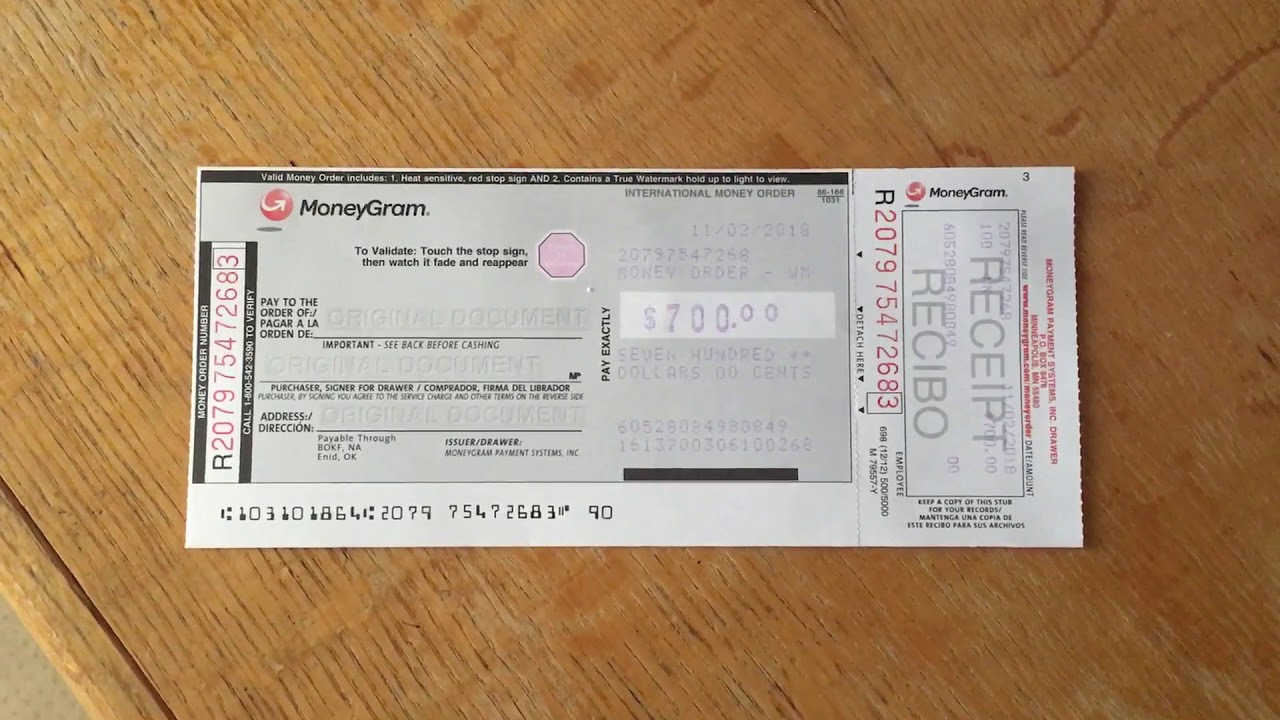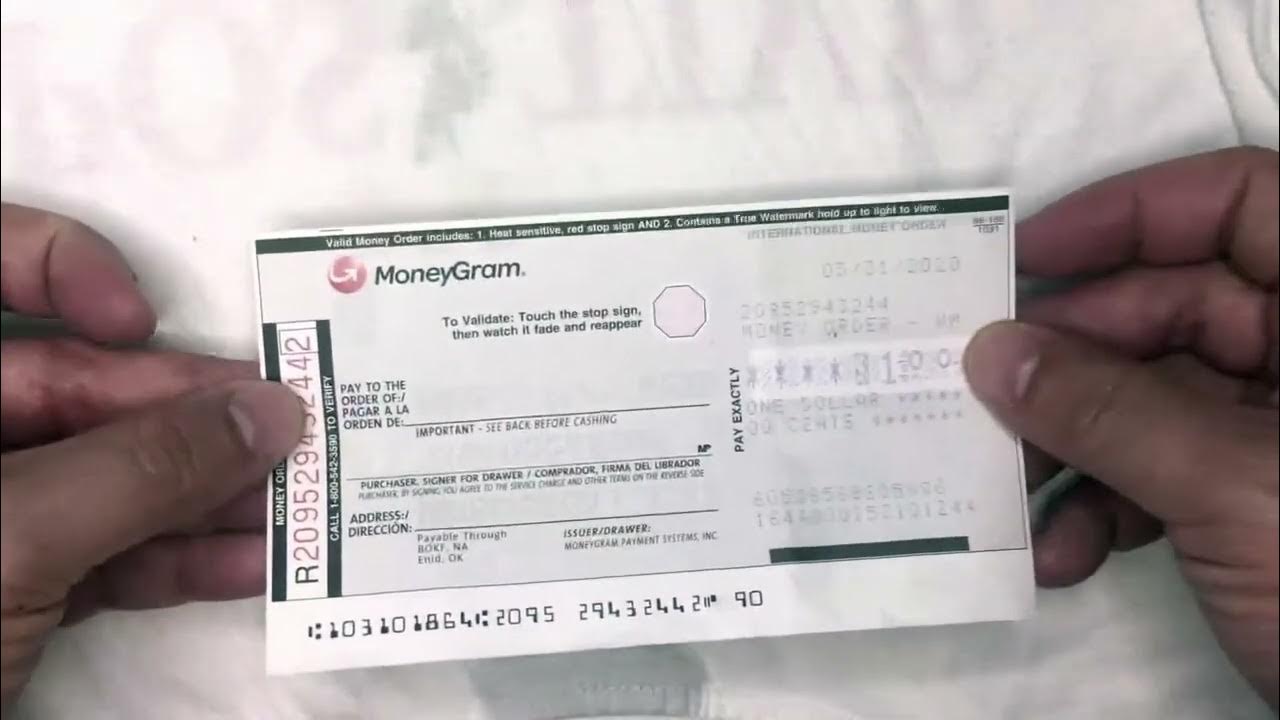
Buying a money order at Walmart is straightforward, but the process has a few details most people miss until they run into them at the register.
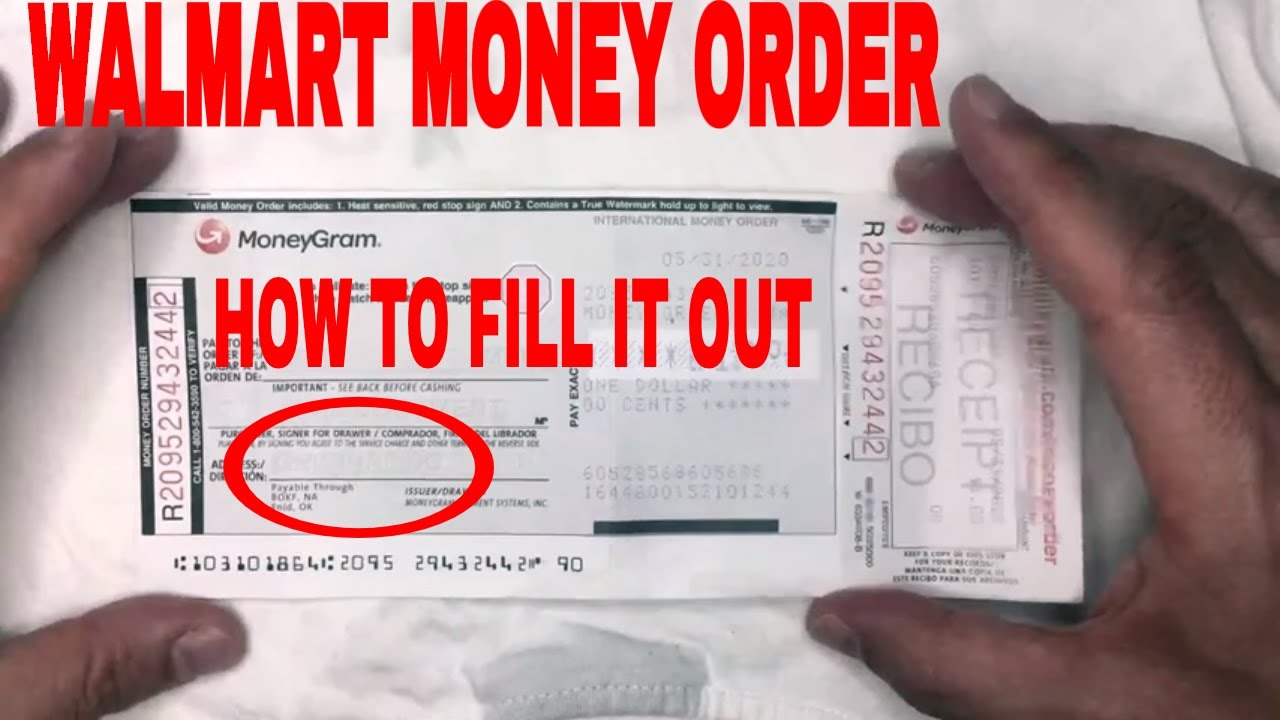
I've been buying and cashing money orders at Walmart for years, mostly for people who don't have bank accounts or need to send guaranteed funds quickly. The whole thing costs $0.50 to $1.00 depending on the amount, which is significantly cheaper than Western Union or MoneyGram at comparable stores. You can get a money order for up to $1,000 per order. If you need more than that, you split it into multiple money orders. That's important because one receipt covers each individual order. Go to the customer service desk or the register. Tell them you want a money order and how much. Hand them your cash. They print the receipt first, then hand you the actual money order slip. Sign the top left area of the money order. Sign the bottom right as the payee when you fill in who it's going to. Don't sign both sides before you know who the recipient is. I once filled out a money order for a contractor, signed my side, then realized I wrote the wrong amount because I was thinking about a different project. Had to scrap the whole thing and buy a new one. Waste of a dollar and ten minutes. The receipt is your proof of purchase. Keep it separately from the money order itself. If the money order gets lost or stolen, you can't replace it without that receipt. I learned this the hard way when I put both in the same envelope and lost the mail entirely. Took about three business days to reissue it, and even then, the person who was supposed to receive it was pissed because the deadline had passed. Always separate them.
There's a lesser-known detail about endorsements. Some places that cash money orders require the recipient to endorse the back with their ID presented at the same time. Others don't care. Walmart itself will cash a money order at the customer service desk or register, but they charge a fee. It's usually around $1.00 to $1.50. Many banks and credit unions will cash them for free if you're a customer. Non-customers sometimes get charged a higher fee or turned away entirely. The MoneyGram network backs Walmart money orders, so they're widely accepted. But acceptance at the point of cashing isn't universal. Here's something most guides don't mention: the tracking number. Every Walmart money order has a tracking number on the receipt. You can check its status at moneygram.com using that number. This is useful if you're the sender and want to confirm the recipient has picked it up, or if you suspect it was cashed fraudulently. I used this once when a friend claimed he never received a money order I'd mailed. The tracking showed it was deposited two days after I sent it. We figured out he'd left it in his mailbox in the rain and the bank had already processed it. Problem solved without any confrontation. If you're cashing a money order and the amount is large relative to your typical transactions, expect questions. Walmart has internal policies about cashing amounts above certain thresholds, and they may ask for additional ID or restrict the cashing to customer service rather than the register. This varies by store. Some locations are stricter than others. There's no published nationwide policy on this, so you just have to deal with whatever the clerk tells you.
One edge case worth noting: expired or old money orders. Walmart money orders don't technically expire, but if one is very old, the processing bank might flag it for review. I had a situation where someone brought in a money order from roughly five years earlier, and the cashier had to get a manager involved. It took another twenty minutes and the manager had to verify it through the MoneyGram system. The money was valid, but the extra scrutiny delayed everything. Don't hold onto these for years. For the recipient, you don't need to go to Walmart specifically to cash a Walmart money order. Any bank, check-cashing store, or postal service that accepts MoneyGram-backed instruments will handle it. That's the main advantage over store-specific money orders. But again, fees apply outside of Walmart, and some check-cashing places charge absurd percentages on larger amounts. A $500 money order at a random check-cashing store could cost you $10 to $20 in fees. At Walmart, it's around a dollar. Do the math before you choose where to cash it.
Get the Full Details
What to watch out for
Never send a money order without keeping the receipt. Ever. Not even for small amounts. Not even for someone you trust. Receipts get lost, mail gets intercepted, and disputes happen. The $0.50 you save by not getting a receipt isn't worth the hassle of a missing $200 money order. Be aware that some merchants refuse money orders from unfamiliar sources. If you're trying to pay a utility company or landlord with a money order, call ahead. I've seen people show up at a billing office only to be told they don't accept them anymore, which means a trip back to Walmart and another dollar out of pocket. Same goes for online payments. You can't use a money order to pay a credit card bill through most portals. It has to be a physical mailing or in-person drop-off. The daily purchase limit is per transaction, not per day. You can buy multiple money orders in one visit as long as each one is $1,000 or less. I've seen people not know this and walk away thinking they couldn't get more than $1,000 total. Just ask for two or three separate orders and you'll have your full amount covered.
Walmart money orders are a solid option for quick, low-cost transfers. They're not perfect. Fees at third-party cashing locations can add up, old orders cause headaches, and the lack of a uniform cashing policy across stores means you never know exactly what you'll face until you're standing at the counter. But for most everyday uses, they work fine and cost less than the alternatives. Just keep your receipt and know your options before you need them.