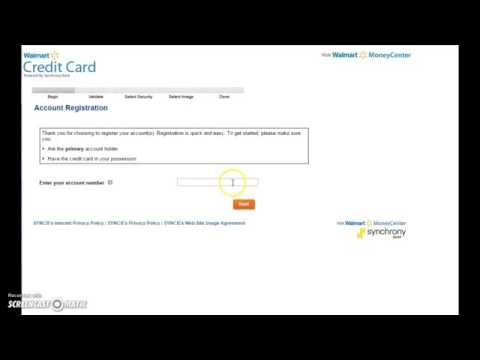
Logging Into Your Walmart Credit Card Account
The Walmart Credit Card is issued by Synchrony Bank. You access it through synchrony.com, not through walmartsavings.com or any other Walmart site. I've seen people waste ten minutes typing the wrong URL before finding the right one. Put synchrony.com in your browser and look for the Sign In button in the upper right corner. That's it. After clicking Sign In you enter your username and password. If you're logging in for the first time, click Register Now and follow the prompts. You'll need your card number, the last four digits of your Social Security Number, and an email address that you check regularly. Synchrony sends a confirmation code there. I made the mistake of using a Gmail address that had spam filters turned up too high once, and the confirmation email went into a filter folder I never check. Took me three days to sort it out. Just use a straightforward email address and make sure you can see what comes in. Once you're in, the dashboard shows your current balance, minimum payment due, statement closing date, and a link to make a payment. The interface is functional, not flashy. It gets the job done.
If you've forgotten your password, click Forgot Password. They'll send a reset link to your email. It usually arrives within a minute. If it doesn't show up after five minutes, check your junk folder and then call customer service. Don't keep clicking the reset button repeatedly. Each click generates another request and just slows everything down. The mobile app works similarly. Download the Synchrony Bank app from the App Store or Google Play, tap Add Account, and search for Walmart. Enter your card details and log in the same way. I use the app mostly for checking my balance while I'm at the store. Sometimes the app lags when the network is weak inside a Walmart, but the desktop version loads fast every time.
Managing Your Payments
There are a few ways to pay your bill, and each has different timelines you should know about. One-time online payment is the fastest option. Log in, go to Make a Payment, enter the amount, and submit. If you pay by bank account, the funds usually show up in one to two business days. If you pay by debit card, it posts faster, sometimes the same day. I always pay by bank account unless I'm near the due date and need the payment to hit immediately. Same-day posting only works with a debit card, and even then it's not guaranteed. Automatic payments are available if you want the system to handle things for you. You set up a recurring payment from a checking or savings account, and it pays either the full balance or the minimum due on a date you pick. I've used auto-pay for years. It eliminates the risk of forgetting a due date and getting hit with a late fee. The one catch is that if your bank account has insufficient funds on the scheduled date, the payment fails and you get charged a returned payment fee from both your bank and Synchrony. That double hit is annoying. Make sure your account balance covers the payment before the scheduled date.
Get the Full Details

Payment by mail is the old-school method. You mail a check or money order to the address listed on your statement. It takes about five to seven business days for mailed payments to post. I only do this when I don't have internet access, which doesn't happen often anymore. Payment by phone is another option. You call the number on the back of your card and follow the automated prompts. It works, but it's slower than doing it online. I call only when something is wrong with my account and I need a human to help me.
Common Problems and What to Do
Sometimes people try to log in and get an error saying their account is locked. This happens after too many failed login attempts. Wait 24 hours and try again, or call customer service to unlock it. It's not a serious issue, just a security measure. Another problem is the statement date. If you make a big purchase right before your statement closes, it shows up on that month's bill. If you wait until after the statement closes, it appears on next month's bill. This is the same for all credit cards, but it trips a lot of people up with the Walmart card because they assume purchases posted on the same day will be on the same statement. They aren't. The statement closing date is what matters, not the posting date. Check your statement closing date in the account dashboard so you know when your next bill is coming. I once had a payment show as delayed even though I submitted it online two days before the due date. It turned out the payment was submitted after the 8 PM Eastern cutoff on the due date. After 8 PM ET, it counts as the next business day. That detail is buried in the fine print, but it's important if you're close to a deadline. I learned that the hard way.
Another thing to watch is the reward points balance. The Walmart Credit Card earns Reward Money on purchases. It's not the same as a percentage cash back on a regular credit card. It's store credit you can use at Walmart. The points accumulate, but they expire after a certain period if you don't use them. I've lost points before because I didn't notice they were about to expire. Log in a couple of times a year just to check your balance and see if anything is approaching expiration. It takes two minutes.
Security Notes
Never share your password or account number with anyone who calls you claiming to be from Synchrony or Walmart. I've had people call me pretending to be from the bank, asking for my login details. That's a scam. Synchrony will never ask for your password. If someone calls and asks for it, hang up and call the number on the back of your card directly. Also, log out when you're done, especially on a shared computer. I've seen people leave their accounts open at home on a family laptop. Anyone who uses that computer can see your balance and payment history. It's basic stuff, but people forget about it constantly. That's about all there is to it. The process is straightforward once you know where to go and what to expect. Most issues come down to timing, not complexity.


