Navigating the Wake County Market Right Now
I've been watching Raleigh and the surrounding Wake County area for over a decade, and the dynamics have shifted enough that old playbooks don't work anymore. The market isn't broken or magical—it's just faster and more complex than it was five years ago. If you're trying to buy, sell, or invest here, you need to understand what's actually happening on the ground rather than relying on broad growth narratives. Wake County Real Estate A Growing Market With Endless Opportunities sounds good in a marketing email, but the reality is more nuanced. Population growth is real. The county added roughly 3,200 residents per month in recent years, driven largely by employment in the Research Triangle Park corridor and downtown Raleigh office conversions. That creates demand. But demand doesn't equal opportunity for everyone, and it certainly doesn't mean prices will keep climbing in a straight line.
Where the actual opportunity lives
Most people look at median home prices across the whole county and make a decision. That's backwards. The meaningful moves happen at the neighborhood level, sometimes block by block. I recently worked with a buyer who wanted to purchase near North Hills, and the numbers simply didn't work there anymore. Median sale prices in that area had pushed past $475,000 for entry-level homes, which eliminated any realistic cash flow potential for rental investment. We pivoted to the Oak City Plaza corridor near Glenwood South, where comparable properties were still trading under $340,000 with stronger rent-to-price ratios. That single geographic pivot changed the entire investment thesis. The lesson isn't that North Hills is bad. It's that county-wide statistics obscure the actual margins you need to hit. You have to drill down to the submarket level, ideally using sale price per square foot alongside days on market and list-to-sale price ratios. These metrics tell you whether a neighborhood is still appreciating or if it's plateauing and possibly entering a correction phase.
The Mechanics of Buying in This Market
The process itself has gotten tighter. Pre-approval letters used to carry weight. Now they're table stakes, and strong offers routinely come in at or above asking price in desirable corridors. What separates successful buyers now is speed combined with flexibility on terms, not just having the best rate. I recommend running a soft credit pull on yourself before you even start looking so you know exactly where you stand. A single hard inquiry won't wreck your score, but going in blind costs you time you don't have when a decent property hits the market. Properties in Wake County that are properly priced move in under ten days on average. Anything that sits past day fifteen usually has an issue—roof age, foundation concerns, zoning complications, or an overpriced listing that the seller is refusing to adjust. Inspection negotiations are where most deals fall apart here. Sellers in this market have leverage, and they know it. The standard inspection contingency gives you ten days, but in competitive situations, some sellers are asking for shorter windows or waiving repairs entirely. I've seen buyers accept homes with unresolved HVAC issues just to keep the contract alive. That's not always a bad call if you've priced the repair into your offer, but you need to know the numbers before you remove contingencies.
Get the Full Details
A specific problem I ran into recently
Last spring, I was helping a client evaluate a property in the Swainmore neighborhood that had a recent renovation permit on file but no final sign-off from the county. The seller's disclosure was vague, and the title search showed an open permit with a $18,000 value for electrical and plumbing work. Most agents would have either ignored it or assumed it was resolved. It wasn't. The prior owner had pulled the permits, done the work himself, and never scheduled the final inspections. Without that sign-off, the renovation technically doesn't exist in the eyes of the county, which affects both the appraisal and any future resale. The workaround was straightforward but tedious. I had the buyer's contractor walk the property, document what appeared to be completed versus what needed verification, and then we submitted a request for a double inspection through Wake County Building Inspections. That process took about three weeks and cost roughly $650. The inspector found two code violations—an improperly ganged breaker panel and an unpermitted outlet near the kitchen sink. We negotiated a $4,200 credit at closing to cover the corrections, which the seller accepted because the alternative was losing the deal entirely. The house appraised at the contracted price after the permits were closed out properly. That outcome depended on moving fast on the inspection request and having a contractor who understood Wake County's specific electrical and plumbing codes, not just general building standards.
Selling in a Market That Favors Neither Side Completely
Wake County has flipped between a buyer's market and a seller's market several times in the last eight years. Right now, it's somewhere in the middle with slight seller advantage in well-maintained suburban areas and genuine buyer leverage in the higher-priced segments. Pricing strategy matters more than anything else. List at market value or slightly below if you want multiple offers. List significantly above, and the property will stagnate. I've watched homes sit for forty-five to sixty days at inflated prices, then drop to a number that was already achievable three months earlier. The buyer pool shrinks with each price reduction, and the house starts carrying stigma in the MLS notes. Staged showings and professional photography still move the needle, but they won't fix bad pricing. Nothing will.
The counter-intuitive part nobody talks about
Higher inventory doesn't always mean lower prices. When inventory increases in Wake County, it often comes from distressed sales or motivated sellers who need to move quickly. Those properties can actually pull comparable sales down across the neighborhood, which then reassesses your own home's value lower. I've seen this happen in areas like Brier Creek andparts of Northwest Wake, where a cluster of short sales or estate sales depressed appraisals for nearby standard listings. The fix isn't to panic-list immediately. It's to pull comparable sales from the same subdivision over the last ninety days, exclude any distressed properties, and price against healthy comps. If the math doesn't support your target price, you hold and wait, or you adjust the price to match reality. Rental demand in Wake County remains strong, but the old strategy of buying anywhere near the city and letting it appreciate doesn't work the same way. Property management costs in Raleigh average between 8 and 10 percent of monthly rent, and vacancy rates in certain micro-markets have ticked upward as new apartment construction absorbs some of the rental pool. You need to model your numbers conservatively. A duplex in the Southeast Raleigh area might seem like a solid play at first glance, but if you're paying $380,000 and the combined rents only come to $3,200 monthly, your cash flow after expenses is probably negative or break-even. The appreciation thesis becomes your entire return, which is riskier than it looks. I prefer analyzing the cap rate before the appreciation story. If the numbers don't work at current rents, they won't work better in a year either.

Property taxes in Wake County have been climbing alongside assessed values. The county reassesses annually based on market changes, and homeowners in rapidly appreciating neighborhoods like Wade Avenue or North Hills have seen tax bills increase by fifteen to twenty-five percent over three years. Factor that into your carrying costs before you commit to anything.
What the Data Actually Shows Right Now
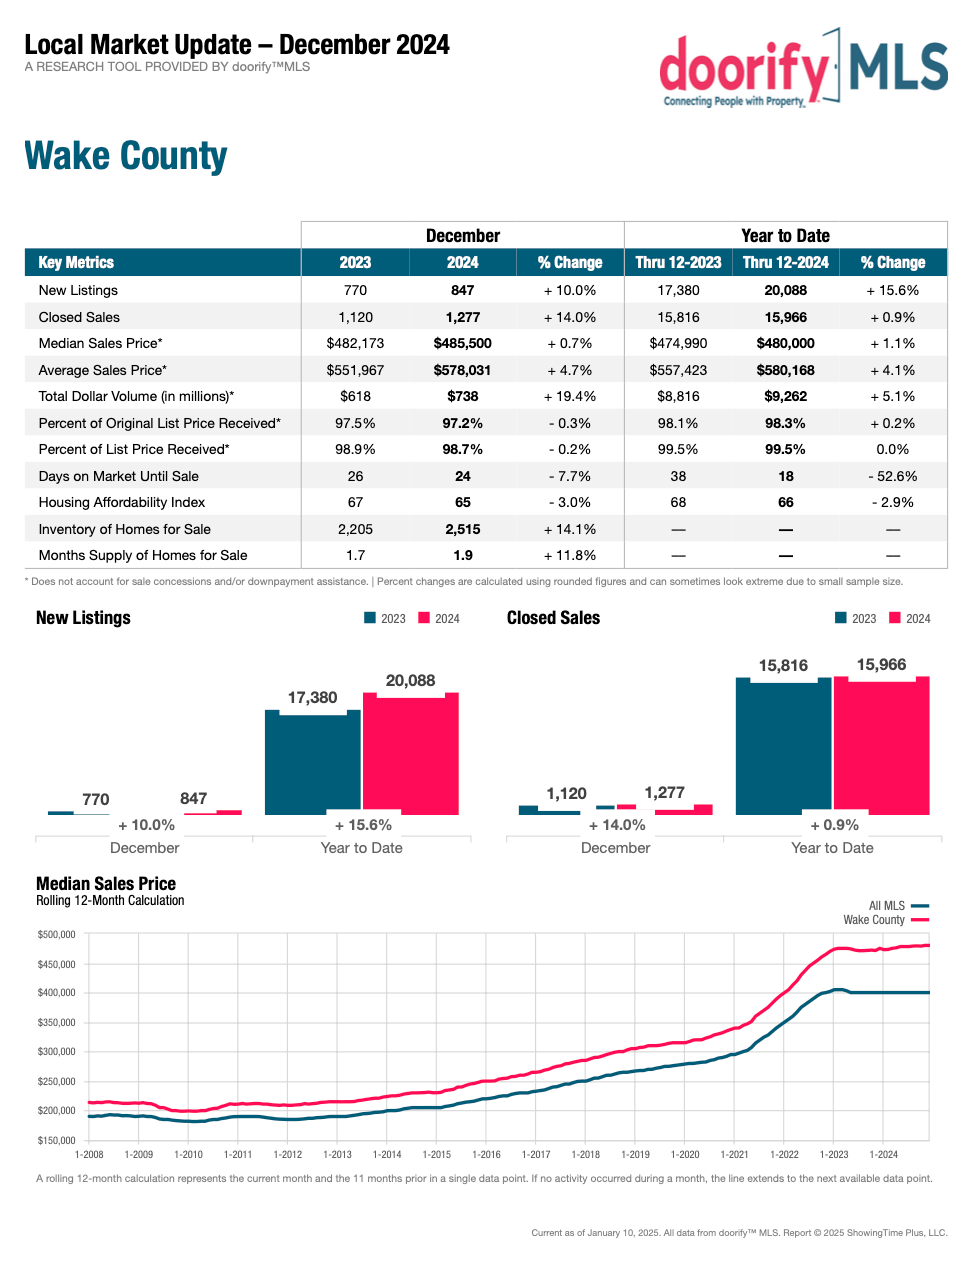
Median sale price for single-family homes in Wake County currently sits around $385,000 to $410,000 depending on which data source you use and when you pull it. Days on market averages between eighteen and twenty-five days for properly priced inventory. Absorption rate hovers near six percent, which is a balanced market indicator, meaning neither side has overwhelming leverage. Inventory remains constrained compared to historical norms but has improved from the extreme shortages of 2021 and 2022. Interest rates are the variable that changes everything in this equation. At current rates, monthly payments on a $400,000 home with twenty percent down run approximately $2,900 to $3,100 depending on tax and insurance estimates. That affordability ceiling pushes many buyers toward the $300,000 to $350,000 range, which is where competition is fiercest and margins thinnest for investors. If you're considering entering this market, start by pulling thirty days of closed sales in the specific neighborhoods you're targeting. Look at the spread between list price and sale price, the percentage of homes selling above ask, and how many transactions involved waivers or escalated clauses. That data will tell you more than any general market report ever will. The opportunities exist, but they're specific to location, price point, and timing, not blanket statements about a growing market.