What Vz Compaymybill Actually Does
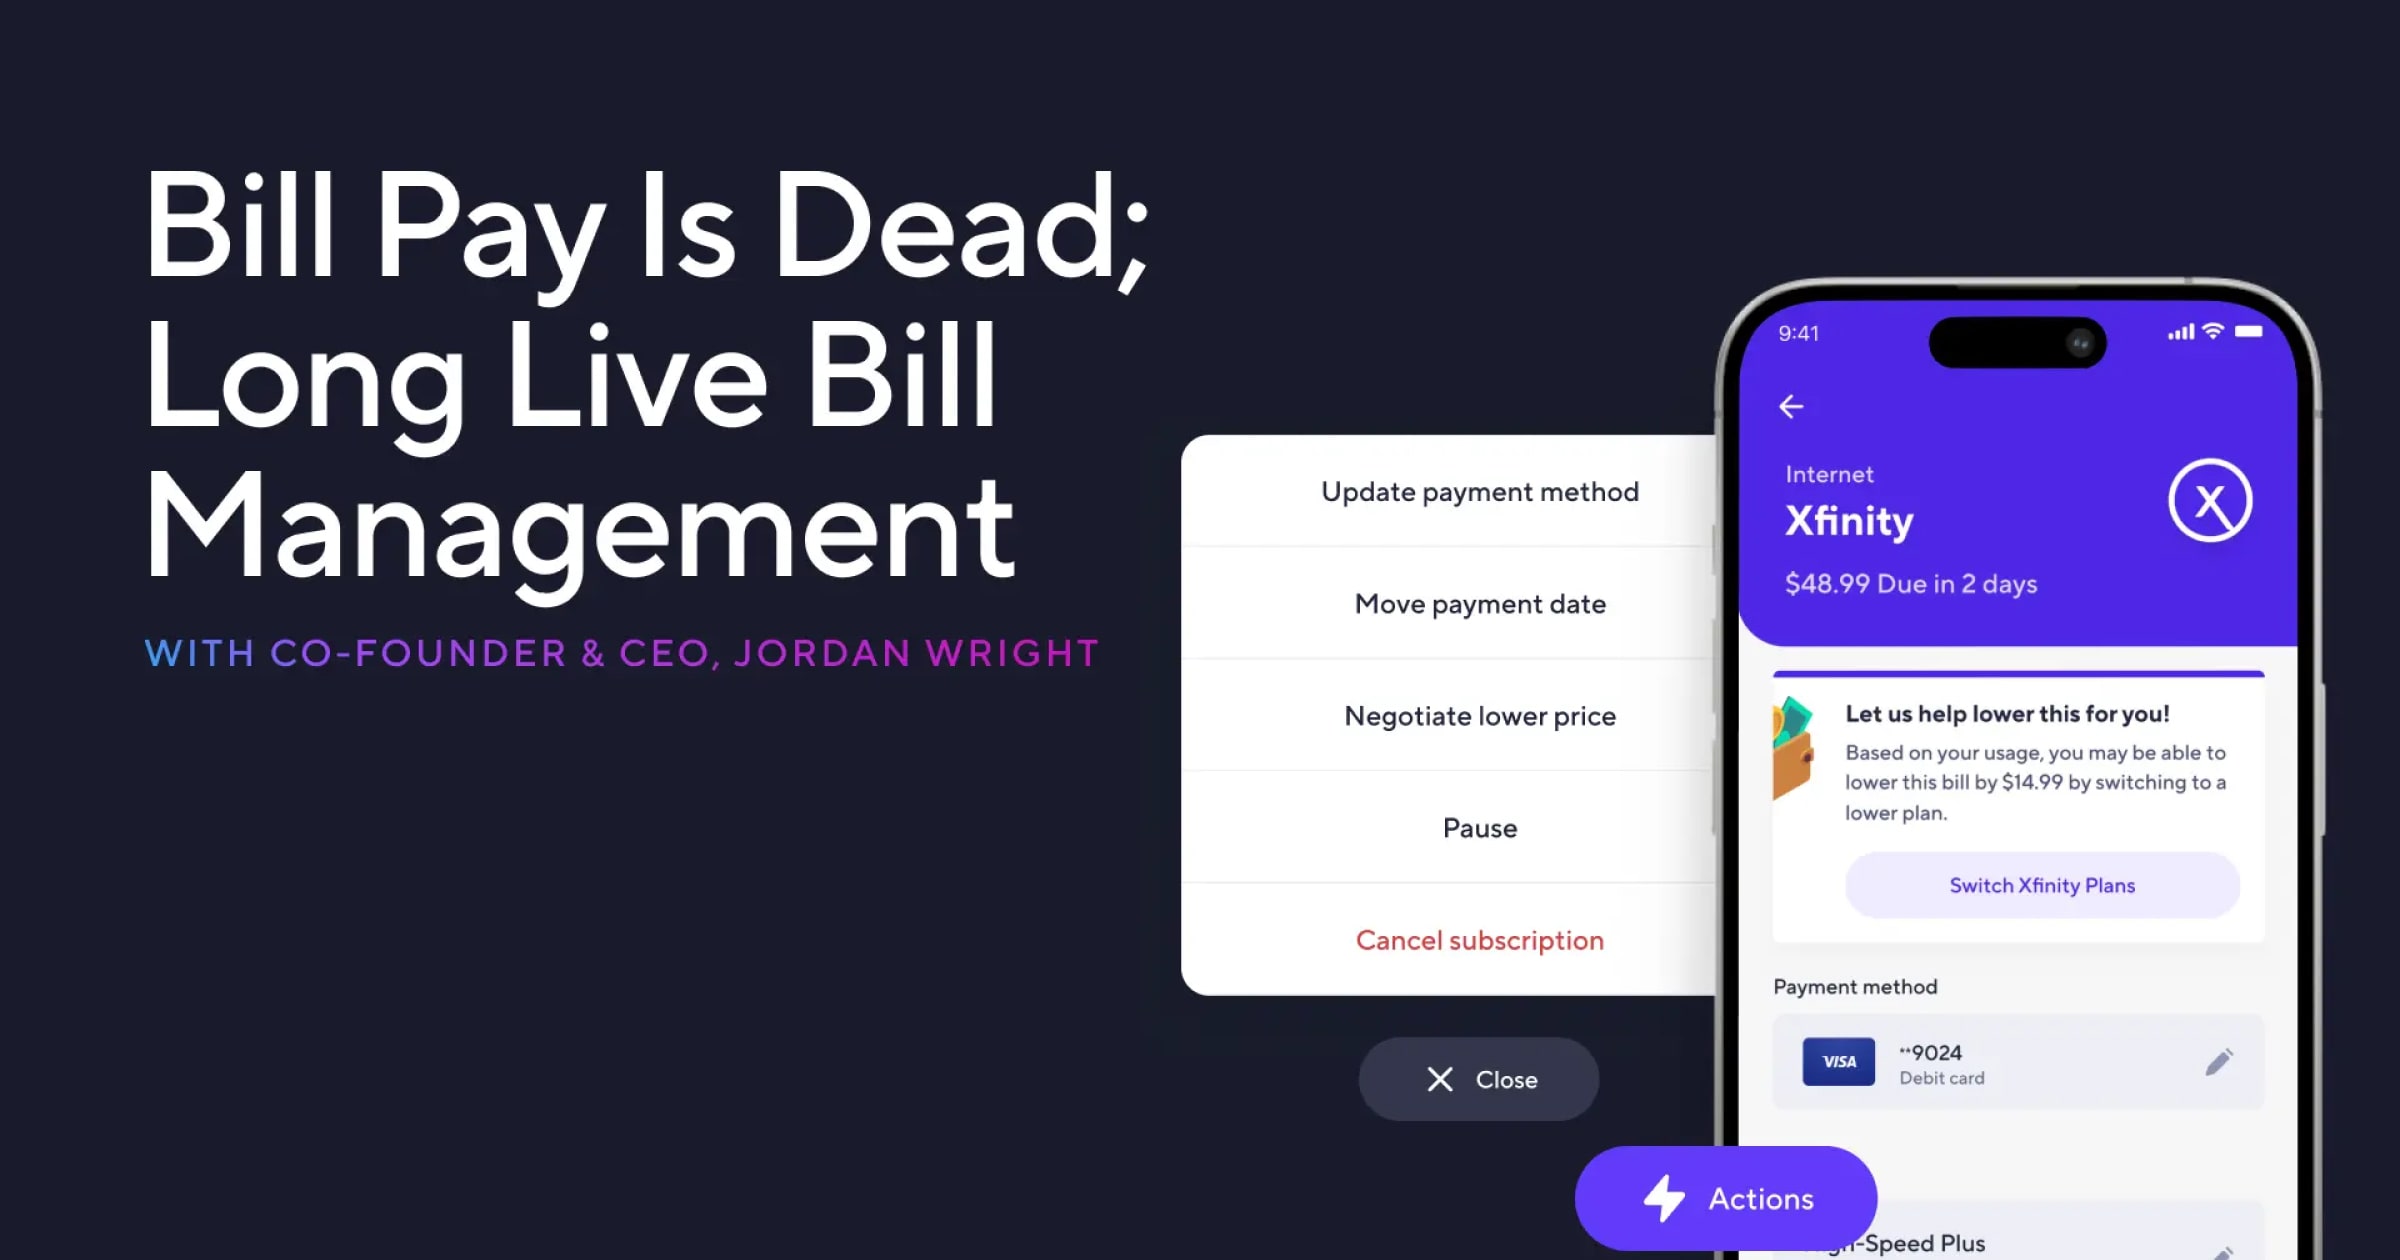
It's a bill aggregation and payment platform that pulls your accounts together and lets you manage due dates, automate payments, and track spending from one dashboard. Most people who start using it do so because they're tired of logging into six different portals every month to check whether their electric, phone, and credit card bills are ready. The platform connects through either direct bank feeds or by manually importing statements, then organizes everything into a single calendar view with push notifications when payments are coming due. The core workflow is straightforward. You link your accounts, set payment preferences for each bill, and the system handles the timing. When a bill arrives, it shows up in your inbox inside the platform. You can review it, flag it for a team member, schedule the payment for a specific date, or set up auto-pay with a reserve buffer to avoid overdrafts. That's the basic promise anyway.
Vz Compaymybill The Groundbreaking Platform Revolutionizing How You Manage And Pay Bills
The marketing language around this platform is heavy, and I'll get to why that matters in a moment. The real value shows up in two areas that most users overlook at first. The first is the reconciliation layer. When you link multiple accounts, the platform doesn't just display your bills, it matches them against your actual bank transactions and flags discrepancies automatically. This means you catch duplicate charges or missed payments before they hit your credit report. The second is the payment scheduling engine, which lets you stagger outgoing payments based on your cash flow rather than the original due dates. If you're paid on the 15th and the 28th, the system can hold non-urgent bills until those windows open up instead of forcing you to pay everything on the 1st. Here's something most guides don't mention. The platform's API for third-party integrations is one of the more flexible ones in this space, but it doesn't support every financial institution out of the box. If your bank isn't in their supported list, you're stuck with manual upload or CSV import. I learned this the hard way when I tried to connect a regional credit union that wasn't on their partner list. The workaround was to export the bank statement as a CSV, map the columns to the platform's import template, and run a reconciliation check after the first import to catch any misaligned transaction dates. Took about twenty minutes and saved me from trying to force a connection that wasn't going to work.
Setting It Up Without Wasting Your Evening
Create an account and verify your identity first. They require this up front because the platform needs to comply with KYC regulations before allowing any money movement. Once verified, go to the account linking section and start with your primary checking account. Let the feed establish itself fully before adding secondary accounts. If you try to link five accounts simultaneously, the system will throttle you and you'll spend more time waiting for refresh cycles than actually setting things up. After your accounts are linked, go into each one and configure the payment rules individually. Don't skip this step. Most people assume they can just set auto-pay and move on, but that's where the problems start. Auto-pay without threshold checks will drain your account if a large unexpected bill comes through. Instead, set up a minimum balance rule so the platform only executes payments when you have enough cushion. I keep my threshold at $200 above my expected monthly outflow, which prevents overdrafts even when I forget about a one-time charge.
Get the Full Details
Common Pitfalls and What Actually Breaks
The biggest issue I've encountered with this platform is around subscription services that change their billing cycles mid-month. The system learns billing patterns over time, but if a provider suddenly shifts from a monthly to a bi-weekly schedule, the platform's prediction model gets confused and may double-schedule or skip payments entirely. The fix is simple enough, but you need to catch it early. Check the prediction accuracy report weekly for the first month, and adjust any bill that shows an anomaly before it causes an actual payment error. Another thing worth noting. The platform's customer support is decent for standard issues but falls apart when you hit a genuine edge case involving international transfers or multi-currency accounts. If you're dealing with anything outside domestic USD accounts, expect to wait 48 hours for a response, and prepare to have your transaction reference numbers ready. I had a situation where a bill from a European provider came through in euros and the platform's conversion rate was off by nearly three percent. Support confirmed they use a mid-market rate that updates hourly, but during high-volatility periods that spread can widen significantly. The workaround was to manually approve the conversion rate within the transaction detail page before confirming the payment, which locked in a more accurate rate at that moment. There's also a hard limitation with how the platform handles joint accounts. If you and a partner both access the same bill set, the platform doesn't have a built-in approval workflow for shared payments. You need to set up separate accounts that reference the same external account, and even then there's no real-time sync between your dashboards. This means both of you can see the same bill and one of you might pay it while the other doesn't know. The workaround is to use the platform's note feature to mark a bill as paid by the other party, but it's manual and easy to forget.
When This Platform Isn't the Right Call
If you're managing fewer than five bills and you already have a simple spreadsheet or a basic calendar system tracking your due dates, this platform is overkill. The setup time alone isn't justified for that volume. Similarly, if you rely heavily on manual payment workflows inside your existing banking apps and don't feel the pain of fragmented bill management, switching to a dedicated platform adds complexity without proportional benefit. For people who already use their bank's built-in bill pay feature and are satisfied with it, the incremental value here is marginal. If you need advanced features like contract management, automated escalation workflows, or integration with accounting software beyond basic CSV export, you'd be better served by a full ERP solution or a dedicated expense management tool like NetSuite or Expensify. Those platforms cost more but handle enterprise-grade complexity that Vz Compaymybill doesn't attempt. For small business owners with more than ten recurring bills across multiple vendors, the platform works but you'll spend a significant amount of time maintaining the categorization rules and reconciling mismatches. The platform has a free tier that covers basic bill tracking with limited account links, and paid tiers unlock automation features and higher transaction limits. As of right now the pricing starts around $8 per month for the standard plan, which should be sufficient for most personal use cases. There's no annual discount available, which is unusual and worth knowing if you're evaluating long-term costs.
I've been running this platform for about fourteen months across personal and small business accounts, and the overall assessment is that it does what it promises without major surprises, provided you invest the first two weeks in proper configuration and accept that some manual oversight is still necessary for anything outside routine domestic payments. It won't eliminate the mental load of bill management entirely, but it cuts the administrative time significantly once everything is tuned correctly.