What the VSP Vision Service Plan Actually Looks Like From the Inside
VSP is one of those companies that exists in almost every workplace benefits handbook, yet most people never really understand how it functions until they're staring at an eye exam bill and wondering why their coverage amount doesn't seem to cover what they just spent. The Vision Service Plan operates differently from standard medical insurance. It's a direct benefit program with contracted providers, fixed copayment schedules, and specific allowances that refresh on a calendar or anniversary cycle — sometimes both at once, which is where confusion creeps in. The press release language makes it sound like a complete overhaul of how employers and consumers interact with vision care. In reality, what's being highlighted is the expanded employer-facing platform and the consumer portal that tracks your benefits more transparently. Employers can now see utilization data, employee participation rates, and cost projections before they commit. Consumers can check their remaining allowances and find in-network providers without calling a support line. That part is useful. The marketing gloss around "revolutionary" is just that — gloss. Here is how it actually works when you are the one trying to use it.
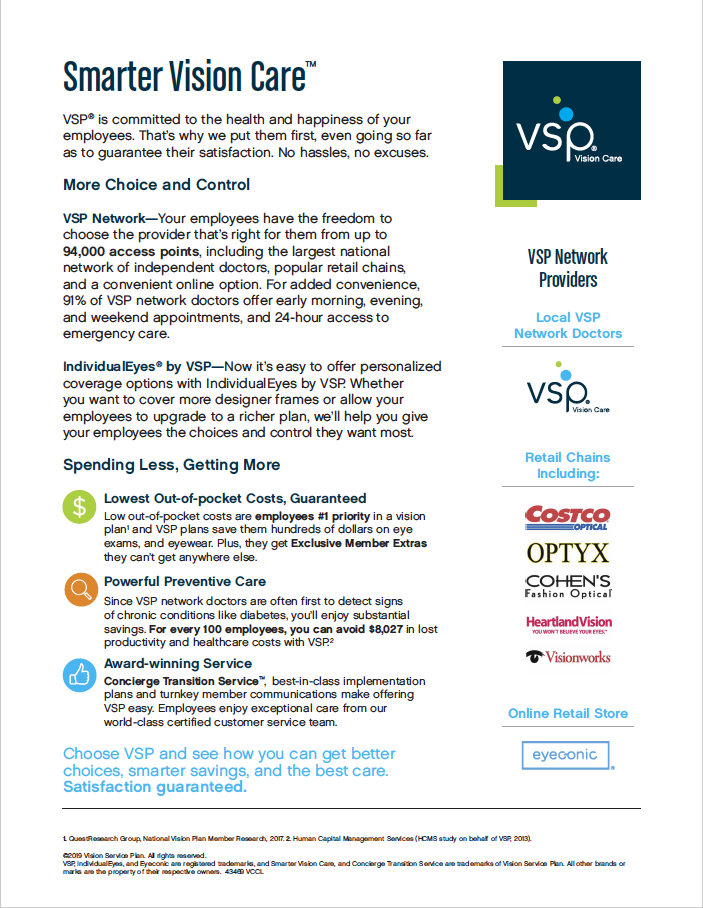
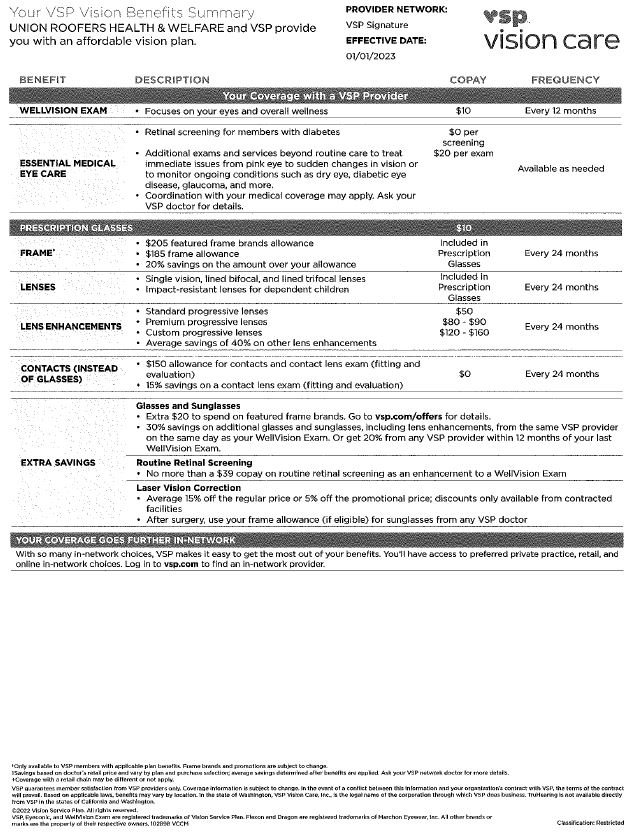
First, you log into the MyVSP portal or use the VSP mobile app. You enter your member ID, which is on your physical card but also accessible through the app after authentication. From there you can pull up your benefit schedule. This is the document that matters most. It will list your copay for a routine exam, your allowance for frames or contacts, and whether you have an additional allowance for lenses or coatings. Some plans bundle these. Some keep them separate. You need to know which model your employer sponsors. Second, you find an in-network provider. VSP has roughly 40,000 locations across the United States, but the quality and availability vary by region. Urban areas tend to have dense networks. Rural areas can be thinner, and some networks include optical chains while others are primarily individual practitioners. You can search by zip code and filter by specialization if the portal lets you. Not all portals give you that level of filtering, so don't assume every interface is equally detailed. Third, you schedule your appointment and confirm that the provider accepts your specific plan variant. This sounds obvious but it is where I learned the hard way that not all VSP contracts are identical. My employer's group plan had a different allowance structure than the standard individual VSP plan. When I went to an optometrist who only accepted the standard plan, the billing system rejected my information at check-in. The office manager had to manually verify my benefit package, which added about twenty minutes to my appointment. I learned to call ahead and ask them to run a quick benefits verification before I arrived. It costs nothing and saves time.
After the exam, you pick out your frames or contacts. Your allowance covers a set dollar amount toward the frame, not a percentage. If your frames exceed that amount, you pay the difference. Contacts work similarly but often use a different allowance tier. Some plans reimburse for contacts instead of frames, or let you choose between the two annually. Check your specific schedule. The online portal usually labels this as "frame allowance" or "contact lens benefit," but the terminology shifts depending on which VSP product tier your employer selected. If you need lenses beyond basic single vision, that is where things get complicated. Progressive lenses, blue light coatings, and thin-material lenses often fall outside the standard allowance. You will pay out of pocket for those upgrades unless your plan includes an enhancement benefit. Some employer groups negotiate upgrades into their contract. Most do not. It is worth asking your benefits administrator whether those items are covered before you get to the optical counter. One thing people consistently miss is the timing of benefit resets. VSP uses either a calendar year or an anniversary year depending on the plan. Calendar year resets happen on January first regardless of when you enrolled. Anniversary year resets happen twelve months after your first eligible date. Mixing these up leads to people thinking they have used up their allowance when they have not, or vice versa — spending early in the cycle and finding out mid-year that the reset already happened and their funds are gone. Your MyVSP dashboard should display your reset date clearly. If it does not, call member services and ask. The representative can pull your benefit schedule and read it to you in under five minutes.
Get the Full Details
What Employers Should Know Before Rolling This Out
From the employer side, the VSP model is straightforward to administer because VSP handles most of the claims processing and provider network management. Your HR team does not need to adjudicate vision claims the way they would for medical insurance. The main work is choosing the right plan tier, communicating the benefits to employees, and reviewing utilization data periodically to spot trends. High utilization in certain regions or among certain demographics might signal that a network change or a different plan design would reduce costs without hurting access. The new employer tools in the recent press release focus on analytics and communication. Employers can generate reports showing participation rates, average employee savings, and cost-per-employee metrics. These reports are useful for renewal negotiations. If you are a small business owner, the reporting may feel overbuilt. The data is still accurate, but the interface assumes you have someone dedicated to benefits administration. If you are wearing multiple hats, you will spend more time learning the portal than you save on administrative overhead. A practical tip that is not in any VSP brochure: always confirm whether your plan includes an eyewear upgrade benefit before renewal season. Some employers auto-renew without reviewing the details. If you keep getting the same plan year after year, you might be paying for allowances your employees never use, or worse, you might be under-insured while your workers struggle with high out-of-pocket costs at the optical counter. Reviewing this annually takes about ten minutes and can change your premium meaningfully.
Pitfalls and Limitations
VSP is reliable for routine eye care. It is not a comprehensive health solution. If you have a complex ocular condition requiring specialist care, surgery, or prescription medication, VSP benefits will not cover those things. That is medical insurance territory. VSP handles exams, frames, contacts, and basic lens upgrades. Anything beyond that falls outside the scope of the plan, and you will need to route those expenses through your medical benefits or pay out of pocket. Another limitation is the network restriction. Going out of network with VSP is possible in many cases, but the reimbursement rate drops significantly. You might recover a portion of what you spent, but it is rarely close to what an in-network provider would have cost. For most people, staying in network is the rational choice unless there is a compelling reason not to. The customer service experience is inconsistent. Some regions have responsive support teams. Others have long hold times and representatives who seem to be reading from a script without much flexibility. I have called about benefit discrepancies and waited upwards of twenty minutes on a few occasions. The callback option is usually available and worth using if you are in a hurry. Leave a number and hang up. They typically return within an hour during business hours.
One edge case that causes problems: seasonal allergies and contact lens intolerance. If your eyes are sensitive, switching between frames and contacts annually within your VSP allowance might not work for you. You could find yourself needing a different lens material or a specialized fitting that is not fully covered. In those situations, the out-of-pocket cost for premium contact lenses or specialty fittings can add up quickly. Talk to your eye doctor about whether your plan's contact allowance covers the specific brand or type you need before you commit to a purchase.
Bottom Line
VSP remains one of the more predictable vision benefit options available through employers. The process is standardized, the network is large, and the digital tools have improved enough that most routine tasks can be completed online. The plan has real limitations around specialty care, out-of-network reimbursement, and the occasional support bottleneck. Understanding your specific benefit schedule, verifying in-network status before appointments, and reviewing your plan details at renewal are the three habits that will prevent most problems. Beyond that, it is just another insurance product doing what it was designed to do.