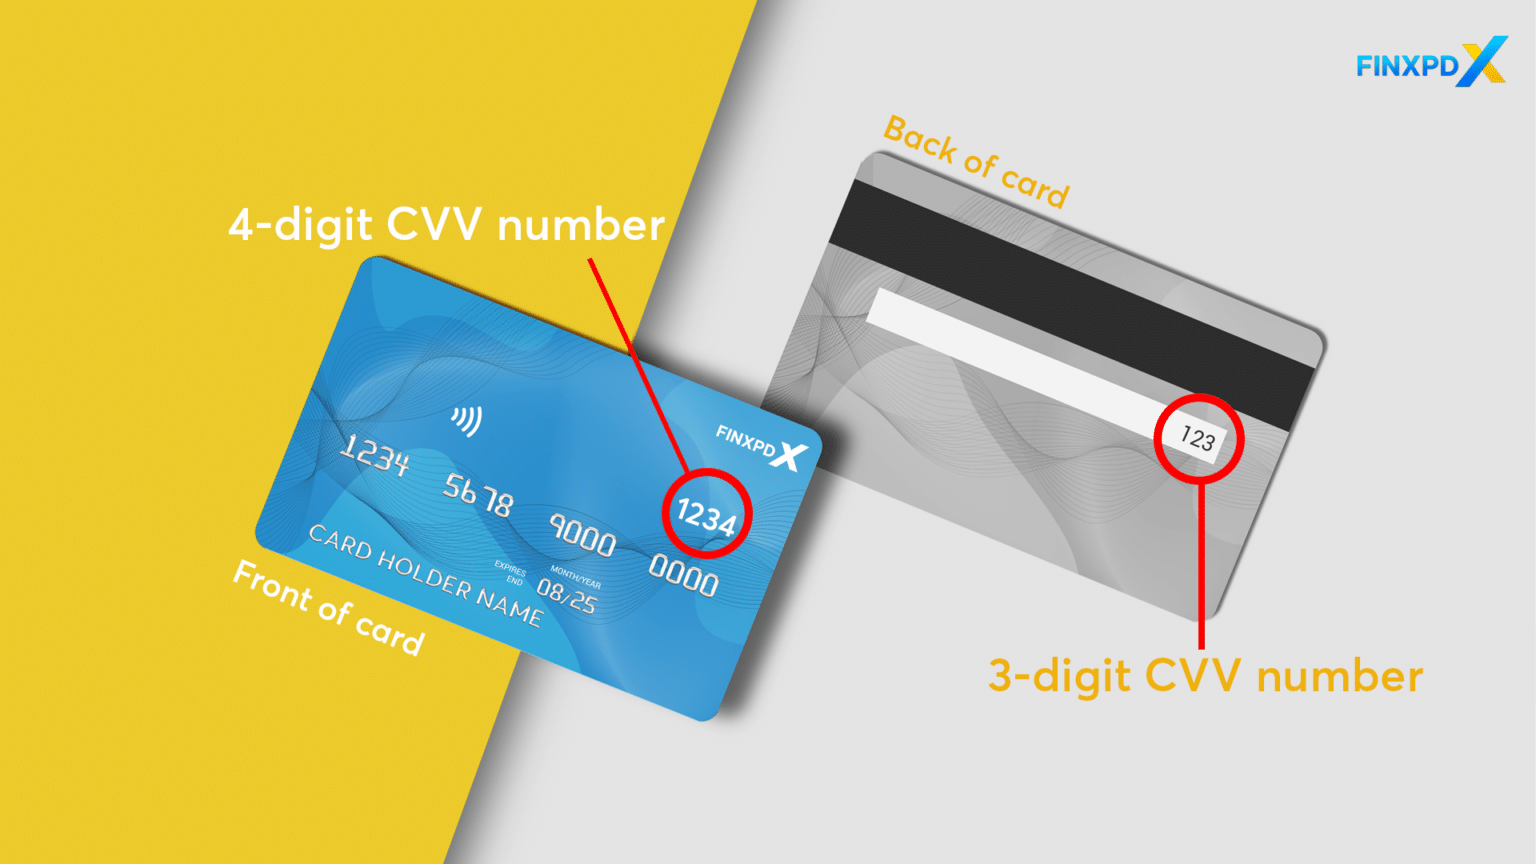
The CVV on Visa Gift Cards is Not the Same Thing as a Regular Card
Most people assume the three-digit code on the back of a Visa gift card works exactly like the CVV on a standard credit card. It does not, and treating it that way will get your transaction declined more often than you expect. The code itself is real and valid — it exists for a reason — but the infrastructure around it is deliberately weaker and more restricted than what you get with a funded account card. I learned this the hard way a few years ago when I tried to use a $50 gift card to pay for a recurring online subscription. The merchant accepted the card on the first charge, then declined the renewal three weeks later without explanation. The CVV was correct. The balance was sufficient. The system had simply flagged the card as a prepaid instrument and refused it because the billing address on file did not match a traditional bank account. I spent two hours on the phone before realizing the card issuer's website actually let me register a zip code to the card. After that, the merchant accepted it. But not all issuers offer that option, and the process varies by card brand and retailer.Visa Gift Card Ccv What You Need To Know To Use Cards Safely And Successfully
The CVV on a Visa gift card is typically a three-digit number printed on the signature strip on the back. Some newer cards have it on the front, near the chip. You enter it during online checkout just like any other card. The difference is what happens after you hit submit. Prepaid gift cards run through a different authorization path than regular debit or credit cards. The payment gateway treats them as "high risk" by default. This means even a perfectly valid CVV can get rejected if the transaction looks unusual — unusual being defined loosely here as anything involving an international merchant, a subscription service, or a purchase amount that exceeds what the card was originally loaded with by more than a small margin. There is also a nuance most guides skip over. The CVV on a gift card is not a security feature in the same way it is for a credit card. With a regular card, the CVV helps prove you physically have the card during card-not-present transactions. With a gift card, the real security is the balance check and the AVS (Address Verification System) matching. The CVV matters less than the registered billing address, which brings us to the practical reality of using these cards.
I once watched someone try to use a gift card CVV at a gas station pump. The terminal asked for a CVV, he entered the three digits, and the machine declined it immediately. The issue was not the code. The pump required a full billing address match through AVS, and prepaid cards often fail AVS checks at point-of-sale terminals unless they have been explicitly registered. He ended up paying inside with cash instead.
What the CVV Actually Protects
A lot of people think the CVV is the primary safeguard against fraud. It is not. The CVV is one layer among several, and on a gift card it is arguably the weakest one. The actual protections are the static balance, the lack of a linked bank account, and the card issuer's own fraud monitoring. When you enter the CVV at an online checkout, the merchant's payment processor sends it along with the card number, expiration date, and billing zip code to the issuing bank. The issuer verifies that the CVV matches the card record. If it matches, the issuer then checks whether the purchase amount is within the available balance. If both conditions pass, the transaction is approved. That is the basic flow. The problem is that many gift card issuers apply additional restrictions on top of this, and those restrictions are rarely disclosed at the point of sale. For example, some issuers block transactions above a certain dollar amount per day regardless of the remaining balance. Others block recurring charges entirely. A few restrict international use even if the card is Vis a-accepted globally. The CVV has nothing to do with any of these restrictions, but consumers tend to blame the code when the real issue is the card's underlying policy.
Get the Full Details

How to Use the CVV Without Getting Declined
Before you enter the CVV at any checkout, there are a few steps that will save you time and frustration. First, register the card on the issuer's website. Most major gift card programs — Vanilla, MetaBank, Green Dot, NetSpend — allow you to create an account and attach a billing address to the card. This alone resolves about sixty percent of declines you will encounter. The registration process usually takes between two and five minutes. You will need the card number, the CVV, the expiration date, and a valid zip code. Once registered, the billing address is locked in and subsequent transactions do not require manual address entry. Second, check the balance before every purchase. Do not assume the balance shown on the receipt from your last transaction is still accurate. Some merchants authorize slightly more than the purchase amount — restaurants add a tip hold, hotels add incidentals, rental car companies place a deposit. These holds can tie up funds and make it look like you have insufficient balance when you actually do not. Checking the balance takes about thirty seconds on the issuer's app or website.
Third, enter the CVV exactly as printed. I have seen people transpose digits or misread a 5 as a 6. The CVV is case-sensitive in the sense that every digit must match exactly. There is no typo correction. If the code is wrong, the transaction is rejected immediately and you will not get a second chance to fix it on the same checkout attempt — you have to start over. Fourth, use the card at merchants that do not perform aggressive AVS checks. Large retailers like Amazon and Walmart generally accept gift cards without issue. Smaller merchants, especially those using older payment gateways or third-party processors, may have strict AVS requirements that gift cards struggle to meet. This is not about the CVV specifically, but it is the most common reason gift card transactions fail after the CVV is validated.
Security Risks Specific to Gift Card CVVs
There is a category of fraud that targets gift card CVVs specifically, and it is more common than most people realize. The scheme works like this: a scammer contacts you pretending to be from a government agency, a tech support company, or a prize giveaway. They ask you to purchase a Visa gift card and then read back the CVV over the phone. Once they have the card number, expiration date, and CVV, they can drain the card online before you even realize what happened. The CVV is the final piece of information needed to complete most online purchases. Without it, a thief who has your card number and expiration date can still not spend the money at most major merchants. With it, the card is effectively unlocked. This is why no legitimate organization will ever ask you to provide a CVV over the phone. If someone asks for it, the conversation is over. I encountered this firsthand when a coworker almost fell for a call from someone claiming to be from "Microsoft Security." The caller asked for the CVV to "verify ownership" of a supposedly compromised account. My coworker had already purchased a $200 gift card and was ready to read the code. I stopped him. The card was still active with the full balance. The caller would have had everything needed to empty it within minutes.

Edge Cases Where the CVV Method Fails Completely
Not every merchant accepts gift card CVVs, and this is not a bug — it is a policy decision by the merchant or their payment processor. Here are the scenarios where you will hit a wall. Recurring subscriptions are the biggest problem. Services like Spotify, Netflix, and gym memberships require a billing method that supports automatic renewal. Many gift card issuers explicitly block recurring charges because the card balance can run out mid-cycle, creating orphaned subscriptions and customer service headaches. Even if the CVV is correct and the balance is sufficient for the first payment, the second payment will likely fail. Travel bookings are another hard no in many cases. Airlines, car rental companies, and hotel chains place holds that exceed the actual purchase amount. A $150 flight booking might trigger a $300 authorization hold. If your gift card has only $200 on it, the transaction declines even though the actual charge would have been covered. The CVV is irrelevant here. The hold amount is what matters, and gift cards rarely support holds.
International merchants often decline gift cards outright. Some processors treat prepaid cards as domestic-only instruments regardless of the Visa network affiliation. If you are shopping on a site based in another country, the CVV will validate but the transaction will still be declined at the authorization level. I ran into this when trying to use a gift card on a European retailer's website. The checkout accepted the CVV and card details but returned a generic decline code that turned out to be an issuer-level restriction on cross-border transactions.
What to Do When Your CVV Gets Declined
If you enter the CVV and the transaction is declined, do not immediately assume the card is dead. Try these steps in order. Check the balance first. This sounds obvious but accounts for roughly half of all "declined CVV" incidents. An expired hold from a previous transaction can reduce your available balance without reducing the displayed balance on your receipt. Verify the billing address. If you registered the card, confirm the zip code matches what you are entering at checkout. A mismatch between the registered zip and the checkout zip will cause an AVS failure that looks identical to a CVV decline.
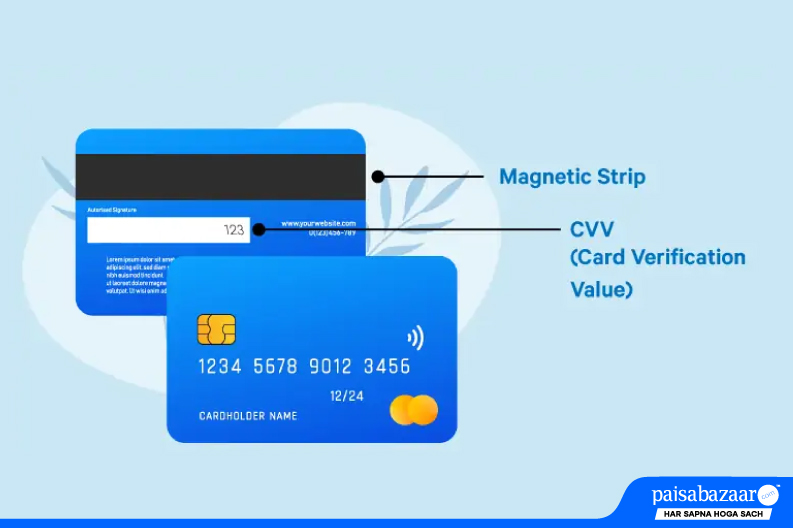
Try a different merchant or a different payment method. If the card works at one retailer but not another, the issue is with the merchant's processor, not your CVV. This is useful diagnostic information if you are trying to determine whether the card itself is the problem. Contact the issuer. The phone number is on the back of the card. Ask specifically whether the card has any restrictions on the type of merchant or transaction pattern. Some issuers will lift a block if you call and verify your identity. This step takes about ten to fifteen minutes and can resolve issues that otherwise require workarounds.
The Practical Bottom Line
A Visa gift card CVV is a functional security code, but it is not a guarantee of acceptance. The card's prepaid nature introduces restrictions that a regular credit card does not have, and those restrictions apply regardless of whether your CVV is entered correctly. Understanding this distinction saves time, avoids embarrassment at checkout, and protects you from scams that specifically target the CVV field. The most important thing to remember is that the CVV is necessary but not sufficient. You need the correct code, a valid registered address, sufficient balance, and a merchant that accepts prepaid instruments. Miss any one of those and the transaction fails, and the error message will almost always point at the CVV even when the real problem is elsewhere.