Vietnam's Green Energy Shift: What Actually Happens When You Try To Execute It
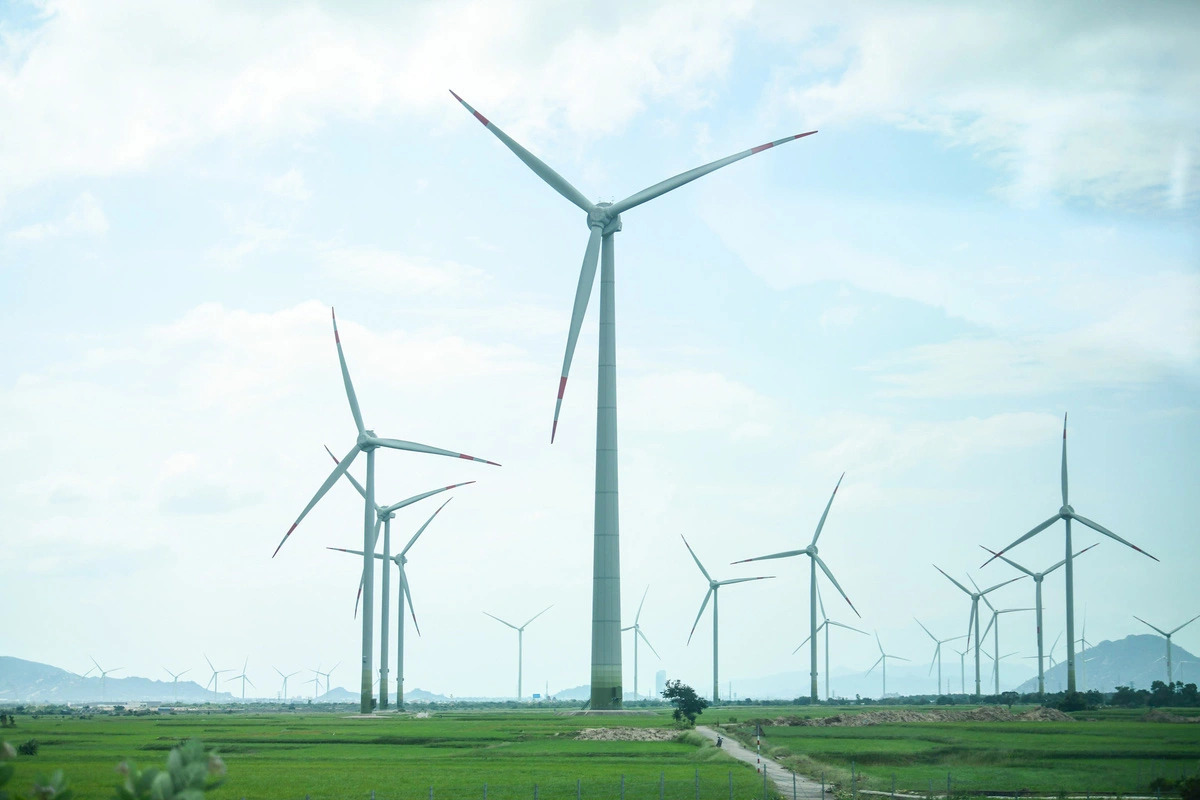
Vietnam's climate commitments sound aggressive on paper. They announced peaking emissions before 2030, cutting CO2 by 30% below business-as-usual by 2030, and reaching net zero by 2050. The policy vehicle is Decision 687/QD-TTg, approved in 2022, which lays out sector-by-sector pathways across power, industry, transport, agriculture, and waste. But reading the document and then actually working inside it are two completely different experiences. I have spent the last few years tracking Vietnamese clean energy projects and policy implementation, and the gap between target and ground reality is where everything falls apart. The core of the strategy is electricity. Vietnam's power sector accounts for roughly 35% of national emissions, and it has been expanding at one of the fastest rates in Southeast Asia. Coal fired much of that growth. The plan pivots hard toward renewables, specifically offshore wind in the central provinces, onshore wind in the south-central coast, and utility-scale solar across the southern corridor. The government also pushed for a revised power planning cycle, PDP8, which formally incorporated more renewable capacity targets than earlier versions. That was a meaningful shift, but PDP8 itself is a planning document, not a binding law. The actual constraints show up later. Vietnam operates through a series of governmental resolutions and ministry circulars rather than a single carbon law. The main lever for emission reduction is the greenhouse gas inventory system, which reports through the Ministry of Natural Resources and Environment. Sectoral targets flow down from the Prime Minister's decision to ministries, then to provincial people's committees. In practice, that means a provincial official in Binh Thuan responsible for approving a wind project is looking at different guidance than a colleague in Dong Nai handling industrial emissions. There is no unified national carbon pricing mechanism yet. Vietnam joined the international carbon credit discussions and has been building domestic rules for carbon trading under the amended Environmental Protection Law, but commercial trading has not fully launched. What exists now is mostly pilot structures and voluntary corporate commitments.
The JETP, the Just Energy Transition Partnership, changed the conversation materially. Announced at COP26 and operationalized with a $15.5 billion mobilization plan backed by the US, EU, Japan, and other partners, it targets phasing out coal capacity, scaling grid infrastructure, and supporting retraining for fossil fuel workers. Money on paper does not equal money in the bank, but it did force Vietnam to produce more detailed roadmap documents and commit to specific coal retirement timelines. The first tranche of disbursement has been slow. Grid bottlenecks in the south have delayed project connections more than anything else. That single constraint has stalled more renewable capacity than policy ambiguity ever did.
Where The Real Work Happens
If you are trying to align a project or a corporate strategy with Vietnam's low-carbon trajectory, start with the grid connection queue. The southern provinces, particularly Binh Thuan, Ninh Thuan, and Dong Nai, have pipelines of solar and wind projects waiting for transmission capacity that does not exist yet. EVN has been upgrading the 500kV corridor, but the pace is not matching project milestones. My own experience with a mid-size solar farm in Ninh Thuan showed that the permitting paperwork could be resolved in weeks, but the grid impact study and dispatch agreement took fourteen months. The workaround was straightforward: we restructured the project to include a battery storage component sized for curtailment mitigation rather than revenue, which changed how EVN classified the interconnection and moved the queue position forward. Storage in Vietnam is not economically justified by arbitrage yet, but it is the only practical lever for project timing. Another area people underestimate is the agricultural methane component. Rice cultivation and livestock account for a large share of non-CO2 emissions, and the 687 decision includes specific measures for alternative wetting and drying in rice paddies, better manure management, and biogas rollout. These are not headline-grabbing sectors, but they are where some of the lowest-cost abatement exists. The difficulty is dispersion. You are dealing with millions of smallholders, not a handful of point sources. Monitoring and verification across that landscape is expensive and often relies on satellite proxies and model-based estimates rather than direct measurement. If you are building an offset project or a corporate scope three reduction plan tied to Vietnamese supply chains, budget heavily for data collection. The MRV costs can consume forty percent of what you expect.
Get the Full Details
Carbon Market Realities
Vietnam is building a domestic carbon market, but it is not operational for general commercial use. The legal basis exists under the Environmental Protection Law and subsequent decrees, and the government has been developing registry infrastructure. Cross-border recognition under Article 6 of the Paris Agreement is still being negotiated. Vietnamese companies selling into European markets will encounter CBAM compliance requirements starting in its transitional phase, which effectively treats Vietnamese steel and cement producers as if they were already subject to a carbon price. That creates pressure to act even before the domestic market is live. The counter-intuitive part is that many of the largest emitters are moving faster on internal carbon pricing and efficiency upgrades than the policy framework would suggest, simply because export customers are demanding it. The power sector's decarbonization path has a similar gap between signals and execution. Vietnam has offered FITs for solar and wind, and those programs drove rapid capacity additions. The FITs have expired or are being replaced by auction mechanisms and PPAs negotiated directly with EVN. The problem is tariff risk. EVN has struggled with financial sustainability, and off-taker risk remains a real constraint for independent power producers. International lenders and JETP funds are partially de-risking new projects, but local financing is cautious. If you are evaluating a Vietnamese renewable project on purely commercial terms without blending instruments or political risk coverage, the return profile looks thin. With the right structure, it becomes viable. The difference is usually a multilateral guarantee or a concessional loan component.
Industrial And Transport Angles
Manufacturing is the next frontier. Textiles, footwear, and electronics assembly are energy-intensive and export-oriented, which means they face increasing pressure from downstream buyers. Several large Vietnamese manufacturers have already set science-based targets and are purchasing renewable energy through PPAs or Green Electricity Certificates, though the GEC system is still being formalized. Industrial clusters in the northern provinces are seeing early adoption of rooftop solar and energy management systems. The bottleneck there is capital. Margins in garment and shoe manufacturing are narrow, and retrofitting facilities without subsidy or lease structures is difficult. Project developers who can offer energy-as-a-service models with no upfront cost to the manufacturer are finding real traction. Transport is harder. Electric two-wheelers and buses are growing in Hanoi and Ho Chi Minh City, but the charging infrastructure gap is significant. Grid capacity in dense urban areas is not designed for concentrated EV load. Battery swap networks for motorbikes are emerging as a practical workaround because they avoid the need for simultaneous high-power charging. The government has issued guidelines for EV promotion, but implementation depends on local authorities and utility capacity. Emissions from transport in Vietnam are still dominated by internal combustion engines, and the turnover rate for the existing fleet is slow. Policy levers like import tax adjustments on electric vehicles have had limited impact compared to total cost of ownership dynamics.
What This Means In Practice
The plan is directionally clear. The obstacles are institutional and financial. Vietnam has the natural resources for wind and solar, the regulatory intent, and growing international support. What it lacks is grid infrastructure, dispatch flexibility, and a mature carbon pricing signal. The net-zero by 2050 target is achievable only if coal retirement accelerates beyond current announcements and if the grid can absorb variable renewable input at scale. Both require investment levels that exceed what domestic budgets can provide. The JETP and similar mechanisms are meant to close that gap, but disbursement timelines are inconsistent, and conditionality can delay projects. For anyone working inside this space, the practical takeaway is to focus on the constraints that matter operationally. Grid connection timing, off-taker credit quality, and MRV feasibility for non-power sectors determine whether a project or policy initiative actually lands. The broader targets are useful for strategy and stakeholder communication, but they do not replace detailed due diligence on transmission capacity, permitting timelines, and local authority alignment. Vietnam's low-carbon transition is happening. It is just happening at the pace of its infrastructure and institutional bottlenecks, not at the pace of its announced targets.