The Victoria's Secret Mastercard Actually Has Some Usefulness If You Shop There Regularly
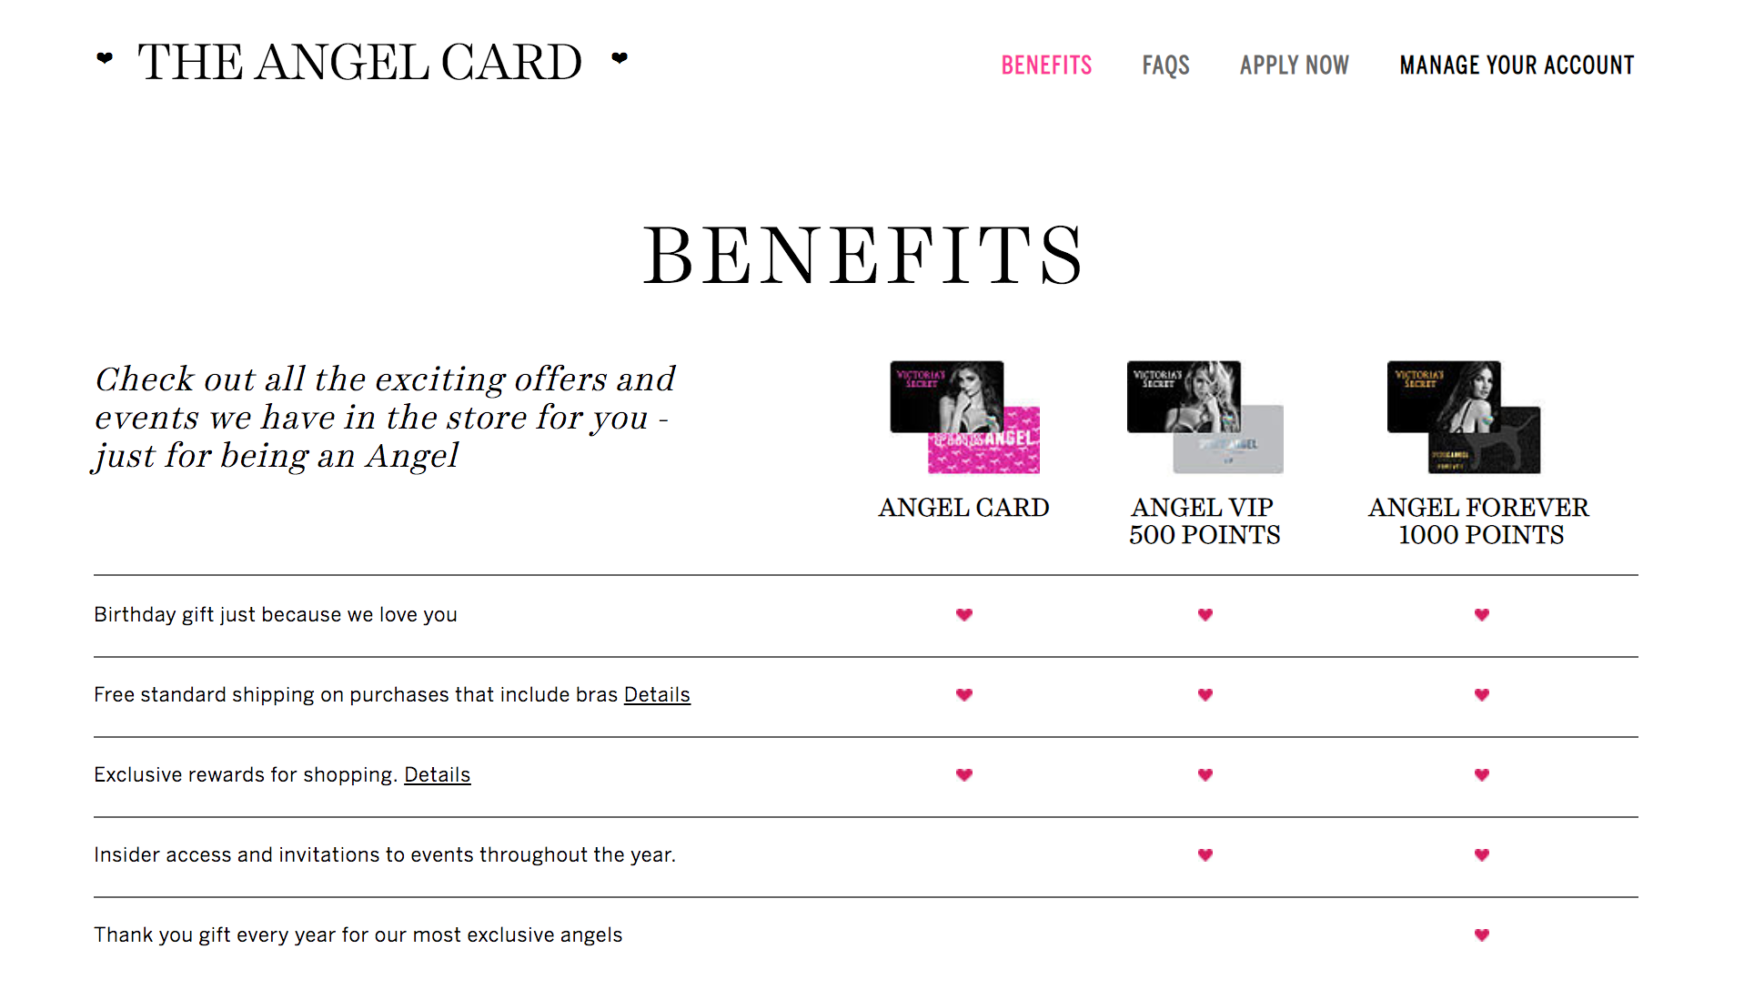
Most people sign up for this card because they get 25% off at checkout, and then they forget about it until the bill arrives. I've worked in retail credit card territory long enough to know what actually matters here, so let me break down the real numbers instead of the marketing fluff. The card has two versions: the standard Mastercard and the more expensive Premier version. The standard one earns you 1 point per dollar on Victoria's Secret purchases, PINK, Bath & Body Works, and a few other brand partners. That adds up to 25% back in rewards if you only use it there, since every 100 points gets you $2.50 off. The Premier card costs $79 a year but bumps your earning rate to 4 points per dollar on Victoria's Secret and Bath & Body Works, which changes the math significantly if you're a high-volume shopper. I spent three years tracking my own card usage against the math before I decided whether it was worth keeping open. Here's what I found that nobody talks about. The points don't expire, which is rare for retail cards, but they also don't earn anything outside those specific brands. Most people treat this as a secondary card, which means they use it occasionally at Victoria's Secret and then rotate it back into storage. You're leaving money on the table by not using it strategically. The 25% discount at checkout applies to your entire order, including full-priced items, which is the single biggest leverage point most cardholders miss. I once had someone come to me complaining their points were "almost nothing" after a year. They'd spent about $1,200 at Victoria's Secret, earned 1,200 points, and felt disappointed. Twelve hundred points gets you $30 off. That's not nothing, but it's also not life-changing unless you're already a frequent buyer.
The Premier card's annual fee only makes sense if you're spending over roughly $2,000 per year at Victoria's Secret and Bath & Body Works combined. Do the division yourself: the extra 3 points per dollar on Premier versus the standard card needs to outpace that $79 fee, and it does after about 2,600 dollars in eligible spending. Below that threshold, you're paying to lose money compared to the no-fee version. Another counter-intuitive thing: the card occasionally runs promotions where they boost your earning rate temporarily. I saw a period last year where they offered 5 points per dollar on everything during a birthday month promotion. These aren't advertised prominently, and the cardholder portal doesn't send push notifications about them. I started checking my account status manually every few weeks, which added maybe five minutes of work but netted me an extra 400 points in one cycle alone. Here's the edge case that nearly made me cancel the card and cost me about 200 points before I figured it out. I was trying to redeem a large batch of points at checkout, and the system rejected the redemption because I hadn't made a new purchase in over six months. The fine print says points can become dormant after 12 months of inactivity on the rewards side, but the redemption engine apparently has its own separate trigger. I couldn't get customer service to explain this clearly. What worked was simply making a small purchase, waiting 24 hours, and then attempting the redemption again. Nothing more dramatic than that. I flagged it in a note to myself and check every quarter now just to keep the account active enough to avoid any surprises.
The down sides are real and they aren't subtle. The credit line tends to be conservative, often starting around $500 to $1,000 depending on your score. If you're building credit, this can actually help because it reports to all three bureaus and the low utilization from occasional small purchases looks fine. But if you carry a balance, the APR is not competitive. It's around 26% variable, which is well above average for a retail card and nowhere near worth carrying month to month. Pay it in full every time, or the rewards are immediately eaten by interest charges. There's also the matter of limited external usefulness. You can't use this card to earn points on groceries, gas, or travel. If your strategy is to maximize earnings across categories, this card pulls its weight in only one lane. For someone who shops at Victoria's Secret and Bath & Body Works weekly, it's solid. For everyone else, it's decorative. I'd recommend pairing it with a broader-category rewards card rather than relying on it as your only card. If you apply, expect a hard inquiry on your credit report. The approval odds improve noticeably if you already have a history with the brand or a decent credit score above 700. Rejection isn't final though. I've seen people get declined once, wait three months, and come back approved the second time with a slightly higher limit. The underwriting seems to look at recent changes rather than permanent history.
Get the Full Details

The application itself takes about four minutes online. You'll need your Social Security number, annual income, and housing payment information. No one makes this process particularly difficult, but don't submit multiple applications within a short window. Each one triggers another hard pull, and that compounds quickly. My recommendation is straightforward. If you spend at least $500 a year at Victoria's Secret or Bath & Body Works, get the standard card, no question. It costs nothing to hold and the 25% discount pays for itself on a single purchase. If you're spending over $2,000 annually across those brands, consider the Premier version after you've confirmed the math works for your actual spending pattern. Otherwise, skip it and use that checkout moment to just say no to the card offer. Nothing wrong with that either.