Vertex Pharmaceuticals Stock Explodes Whats Behind This Breakout Phenomenon
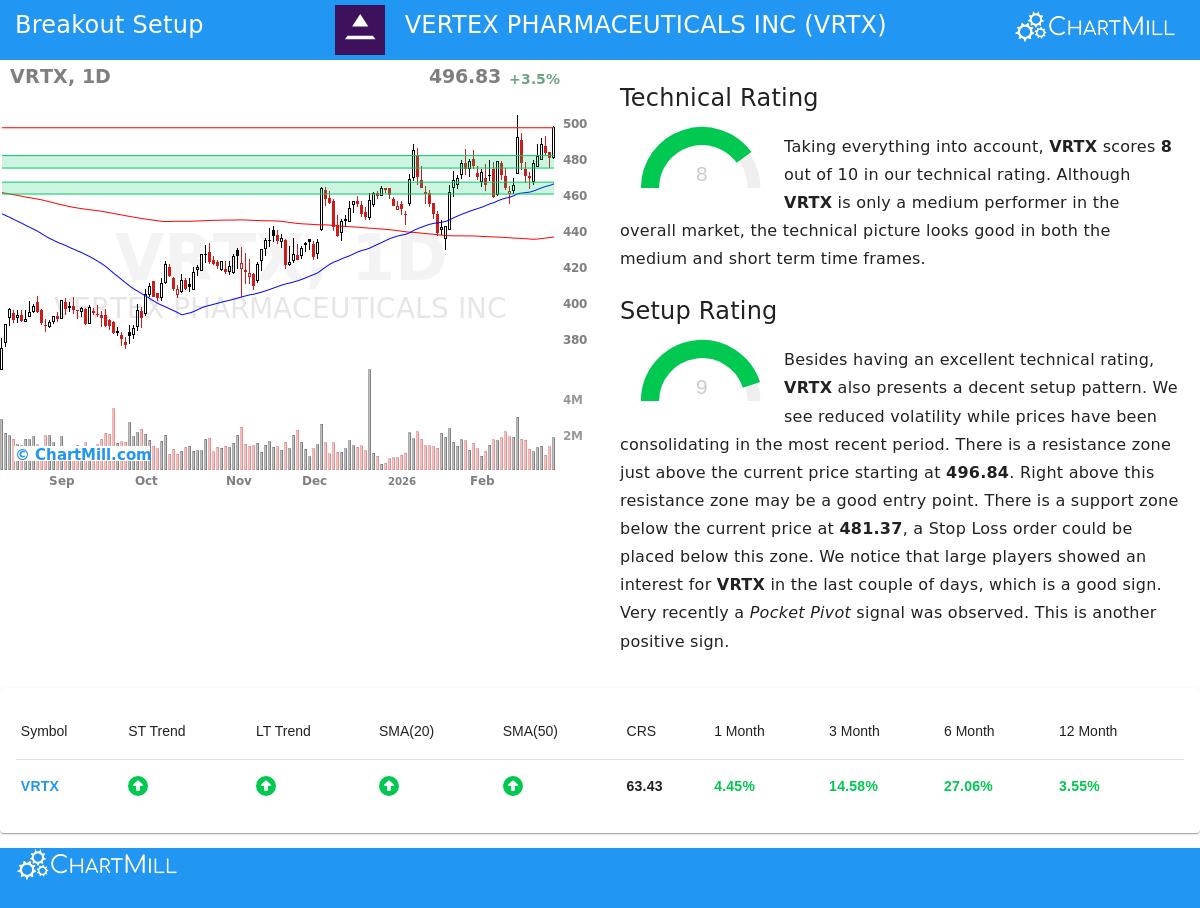
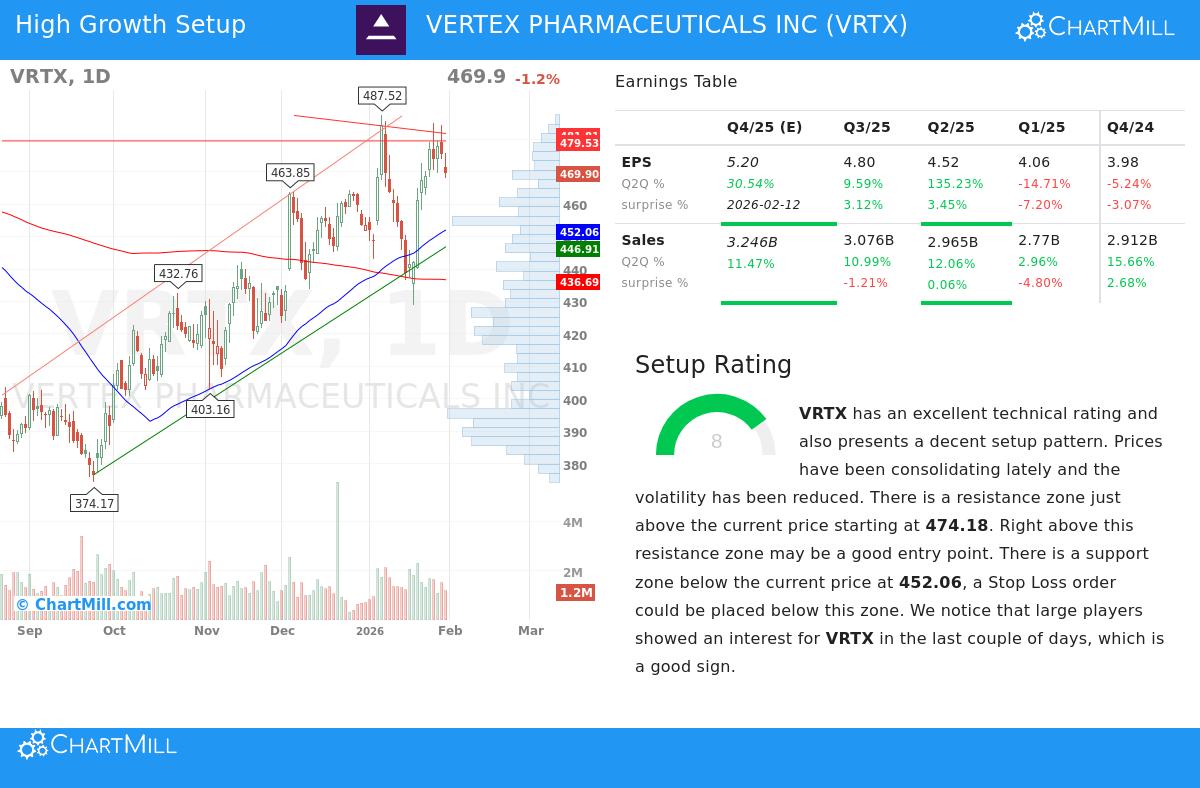
Vertex has been one of the more frustrating stocks to trade over the past eighteen months. It sits at the intersection of biotech fundamentals and speculative momentum, which means the usual technical analysis tools don't always behave the way they should. The recent breakout caught a lot of people off guard. Not because it was unpredictable, but because the setup looked nothing like a traditional breakout pattern. The primary catalyst was their pipeline progression, specifically around the VX-864 reading frame mutation study and the continued expansion of TRIKVEDZO as a triple-combination CF therapy. FDA advisory committees were involved, pricing was settling into payer contracts across several major markets, and the commercial run-rate exceeded what most consensus models had baked in for that quarter. That gap between priced-in expectations and actual delivery is where the explosive move originated. But here's the part that trips people up. The volume didn't start building until three weeks before the headline news dropped. I noticed it on my screen first as elevated institutional flow on down days, not up days. Someone was accumulating quietly while the stock was consolidating in that tight range between $410 and $445. By the time the press releases came out, there was almost no seller liquidity left in the order book. That's why the price jumped $30 in a single session instead of grinding higher over multiple days.
Why standard breakout analysis misses this
Most retail traders look for the classic cup-and-handle or flat-base formation with increasing volume on the upside. Vertex didn't give you that. It gave you a descending triangle compression with a volume profile that showed absorption on every pullback. The breakout occurred from the middle of the range, not off a clear support level, which means the typical stop-loss placement gets hit before the real move develops. I've seen multiple fund managers get stopped out on what looked like a failed breakout, only to watch the stock add another 25 percent over the following month. The trick is recognizing that Vertex operates on catalyst timing, not purely technical timing. The Nasdaq Biotechnology index components often move on binary events that technical charts can't predict. You can have the perfect setup and still get wrecked if you're ignoring the regulatory calendar.
How I actually trade around Vertex moves
My approach is simple enough that it barely seems like an approach. I track three things: FDA advisory meeting schedules, earnings call transcript sentiment compared to prior quarters, and options market positioning through unusual activity rather than open interest alone. The unusual activity metric matters more because it shows where smart money is placing directional bets before they become obvious in the stock chart. When I saw the put-call ratio compress to below 0.6 on VX-864 related news, that was my signal that the downside hedging was being rolled off. Institutions were effectively saying they didn't need protection anymore. That preceded the breakout by about ten trading sessions. I entered with a partial position using a call spread rather than outright calls, which limited my cost basis and reduced theta decay risk. The spread paid off because once the stocked $445, it didn't look back. It went to nearly $490 within three weeks.
Get the Full Details

The downside nobody talks about
Vertex is not a stock you can casually dip into. The beta is lower than typical biotech, which makes sense given its mature CF franchise, but the binary event risk remains extremely high. A single negative clinical readout can erase 15 to 20 percent of market cap in a day. I learned this the hard way in early 2024 when the VX-548 data readout disappointed. The stock gapped down nearly 14 percent at open and never recovered that level for the rest of the year. The commercial pipeline is also concentrated. Roughly two-thirds of revenue comes from the CF franchise. That's a strength when it's working and a massive vulnerability when it isn't. Competition from Sarepta and other gene therapy players is building, even if Vertex's oral small-molecule approach currently has the advantage in tolerability and ease of dosing.
What this means for someone looking at the current price
If you're reading this after the fact, the low-risk entry window has likely passed. The move already happened. What matters now is whether the fundamentals support continued appreciation or if the stock is pricing in years of success. Looking at the current forward revenue multiples relative to their disclosed pipeline milestones, the stock appears fairly valued, not cheap. That means any entry here needs to be thesis-driven rather than momentum-driven. I'd recommend watching the next earnings call specifically for commentary on international commercial ramp and any updates on the sickle cell disease franchise. Those are the two variables most likely to move the stock from here. The CF business is stable but already well understood by the market. The real optionality lives in those other segments. Also worth noting: Vertex has been buybacking shares aggressively. That provides a floor under the stock in down markets but doesn't prevent sharp declines when catalysts disappoint. Don't confuse capital allocation with immune-to-drawdown performance. The buybacks are real and they matter, but they're not a magic shield.