Understanding How Verizon's Payment System Actually Works
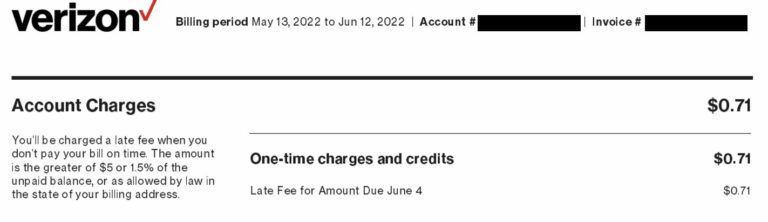
You probably think your bill just charges you on the due date and that's it. It's not that simple. Verizon operates on a cycle where your statement date and your payment due date are two different things, usually separated by about 21 days. If you miss that window, you get hit with a $15 late fee per line, plus interest. That interest compounds monthly if you carry a balance for more than a couple of billing cycles, which most people don't realize until the numbers look strange. I learned this the hard way back in 2019 when my autopay somehow got disconnected after a routine account update during a service window. I didn't notice until I pulled up the app three days past the due date. I was staring at a $30 charge on two lines and a 47-day-old delinquency flag that was going to damage my credit if I let it sit another 30. What saved me was calling in and asking specifically for a one-time courtesy waiver while I explained the autopay failure. They approved it in about six minutes, but only because I had a clean payment history going back four years. If you have missed payments before, don't bother asking nicely — they won't do it.
Verizon Payment Arrangement The Ultimate Guide To Managing Bills And Avoiding Late Fees
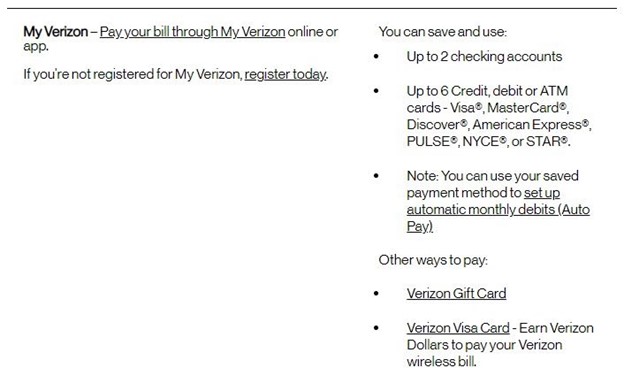
The core mechanism here is autopay enrollment. You link a bank account or credit card and agree to have the full statement balance pulled automatically on the due date. There are two small incentives to do this: a permanent $10-per-line monthly discount and a guarantee against accidental late fees since the system triggers before the cutoff. Most people enroll through the My Verizon app under Settings > Payment Options, but doing it through a representative on the phone sometimes unlocks additional promotions that the website doesn't show you. I don't know why that happens. It just does. Here's something the FAQ pages won't tell you: autopay doesn't always mean paid on time. If your bank account has insufficient funds, Verizon still processes the attempt on the due date and rejects it. You then have approximately four business days before the late fee kicks in and another four before they report the account as delinquent to the credit bureaus. That narrow window is where most people get caught. The workaround is setting up a separate alert with your bank that notifies you of pending automated debits, so you can move money around before Verizon tries to take it. Most major banks offer this feature under their transaction notification settings, and it takes about ten minutes to configure. There's also the option of making a partial payment before the due date. This doesn't prevent the late fee on its own, but combined with autopay it can reduce the total amount at risk if something goes wrong. I've seen people pay half the bill manually and set autopay for the remaining balance as a hedge. Verizon processes these independently, so the timing matters less than you'd think.
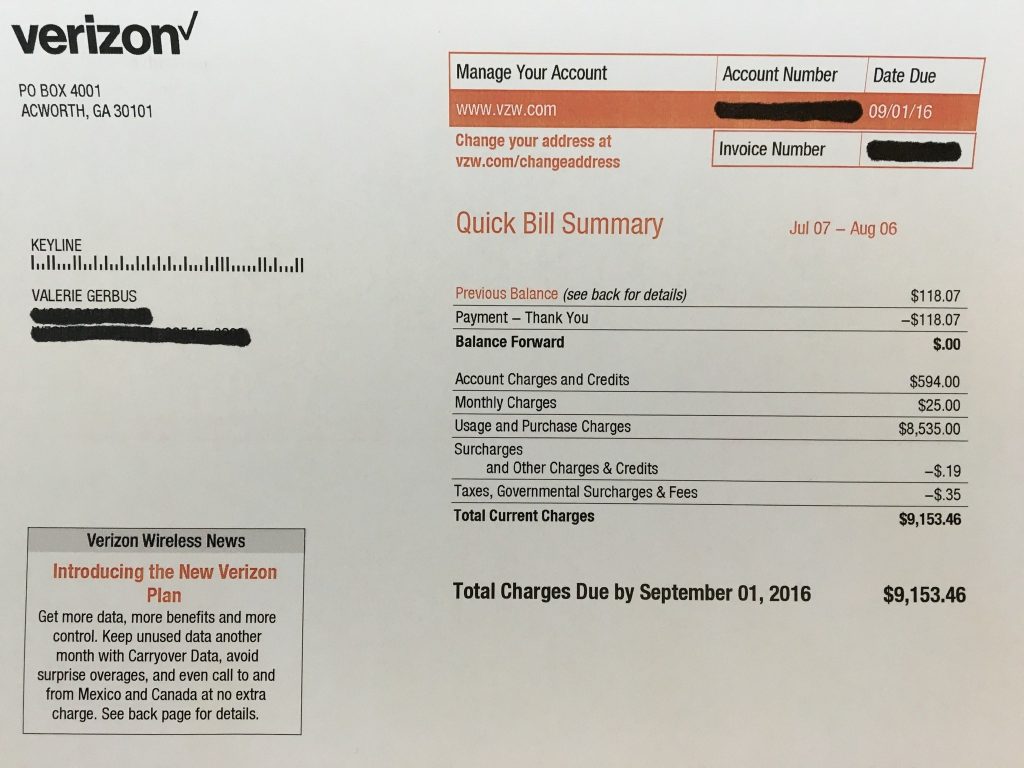
If you're already behind and need to set up a formal payment arrangement, Verizon offers short-term hardship programs through their Customer Assistance department. These typically let you restructure a balance into smaller monthly installments over 60 to 120 days. The catch is that late fees stop accumulating during the arrangement, but interest continues to accrue on the remaining balance at your plan's standard rate. You have to qualify based on things like a demonstrated financial hardship, which means providing documentation if you've missed more than two payments. This is not something you sort out through the chatbot. You need to request a callback from a retention or assistance specialist directly. One thing I wish more people understood about Verizon's billing: the plan-specific charges can create confusion about what actually counts as your "total due." Your bill separates services, taxes, regulatory fees, and one-time charges. Autopay pulls the total, but if you're paying manually you need to make sure you're hitting the full statement balance and not just the rounded subtotal. I had a customer once who paid what she thought was the total and got charged a late fee anyway because the rounding difference was $2.47. The system marked it as an incomplete payment regardless of how small the gap was. Another edge case involves device installment plans. If you have a phone on EIP (Equipment Installment Plan), that payment is baked into your monthly bill. When you upgrade or return a device mid-cycle, the prorounced charges show up on your next statement, and the due date doesn't shift to accommodate them. I've watched people miss this and end up with a suddenly larger payment they weren't prepared for. Setting up a manual calendar reminder for upgrade dates helps, or just checking your upcoming balance in the app a week before your statement generates.
Get the Full Details

The most reliable long-term strategy is combining autopay with a standing calendar reminder that fires three days before your due date. Not to pay early necessarily, but to review the upcoming charge and verify nothing unexpected has appeared. Thirty seconds a month prevents ninety percent of the problems I see people dealing with after the fact.