Understanding How Venezuela Got Here
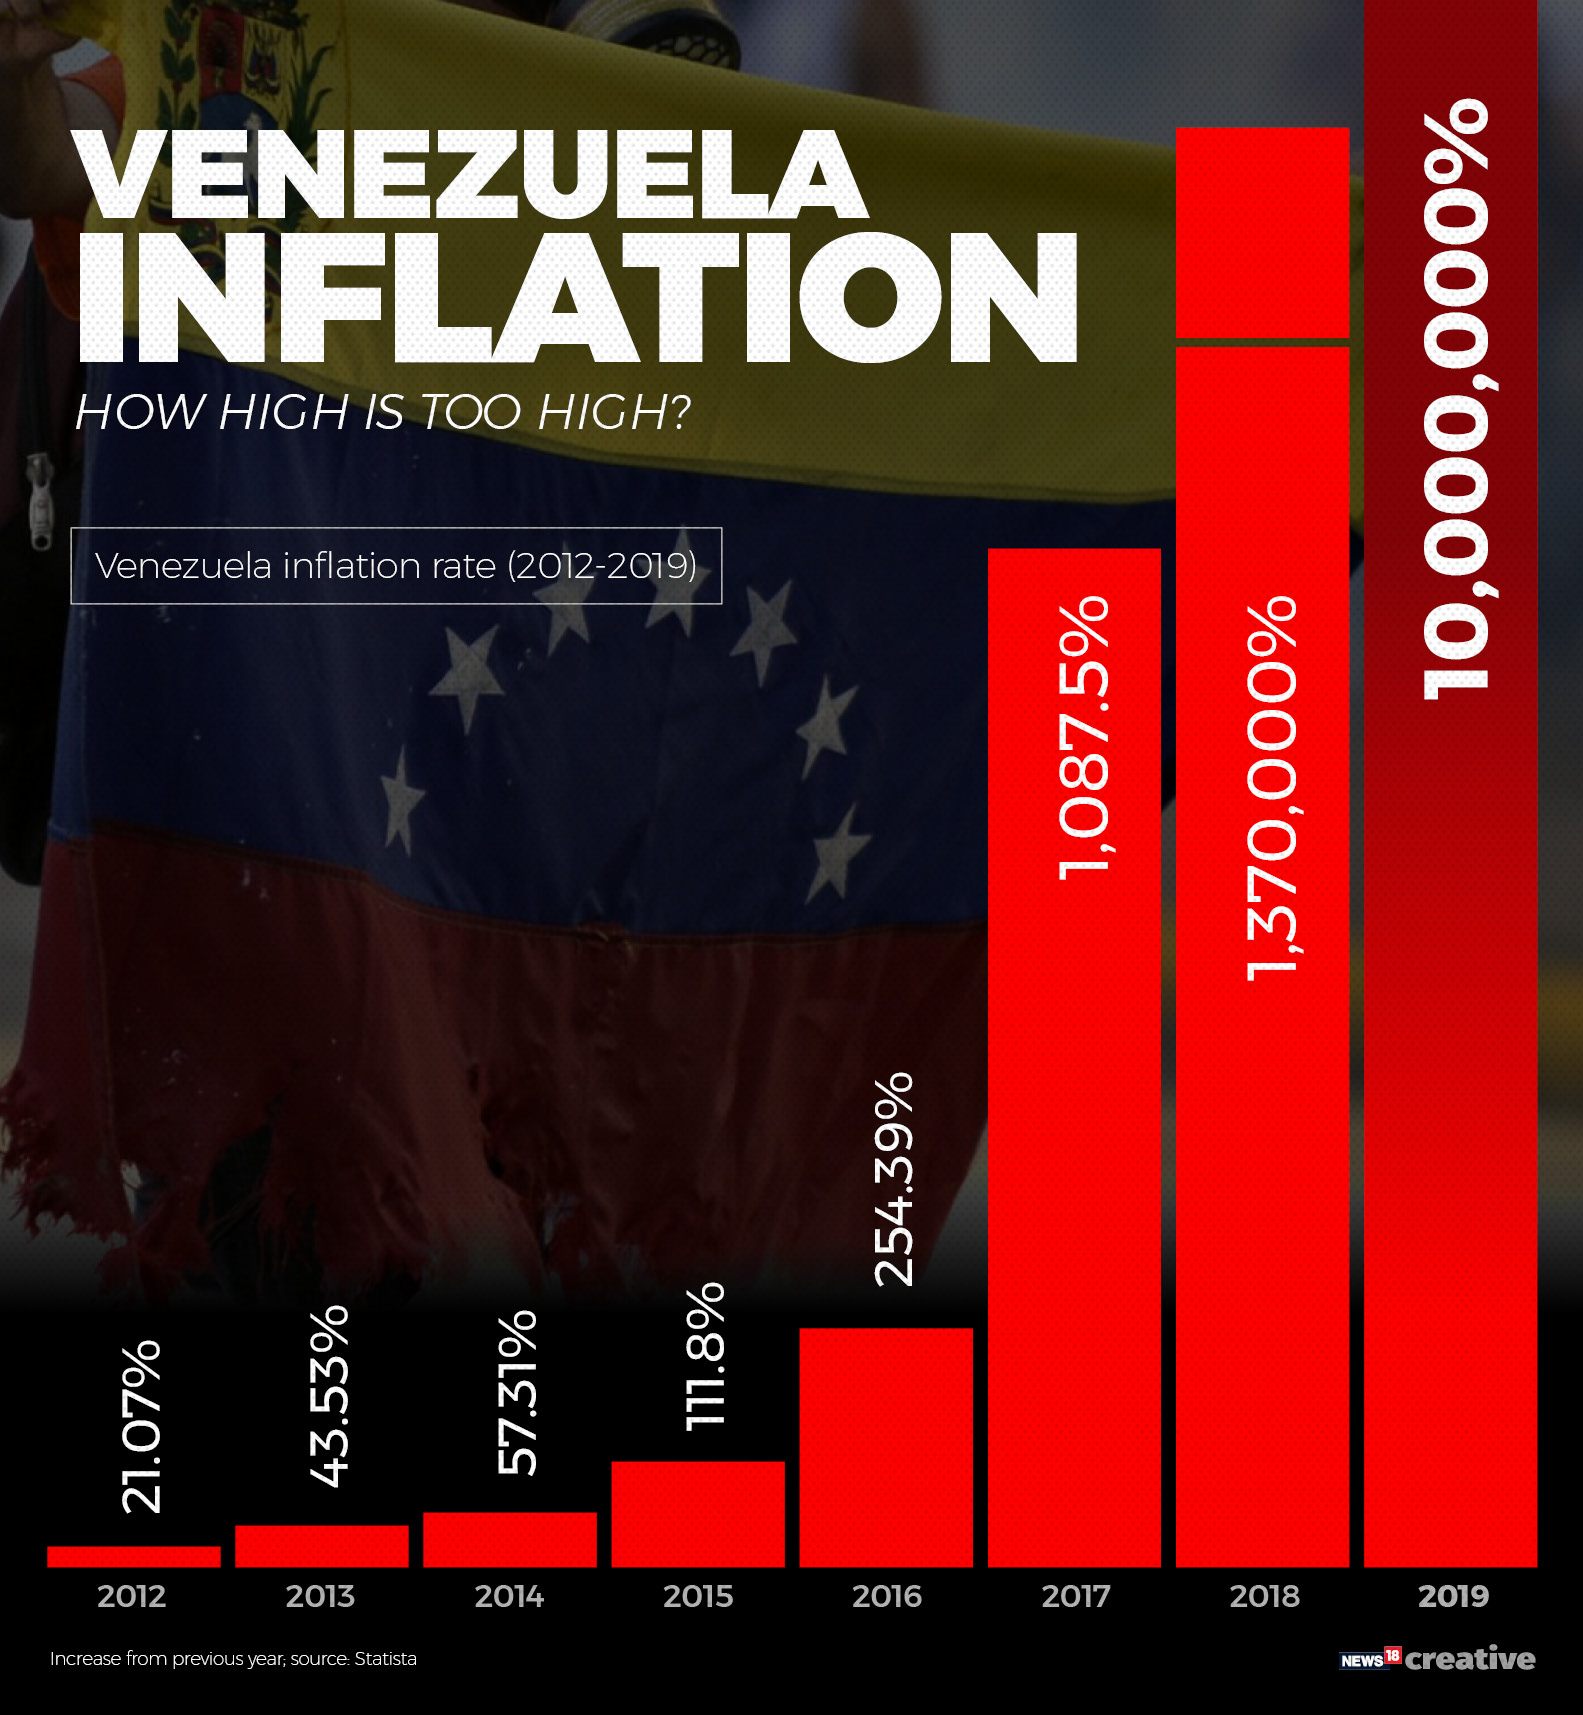
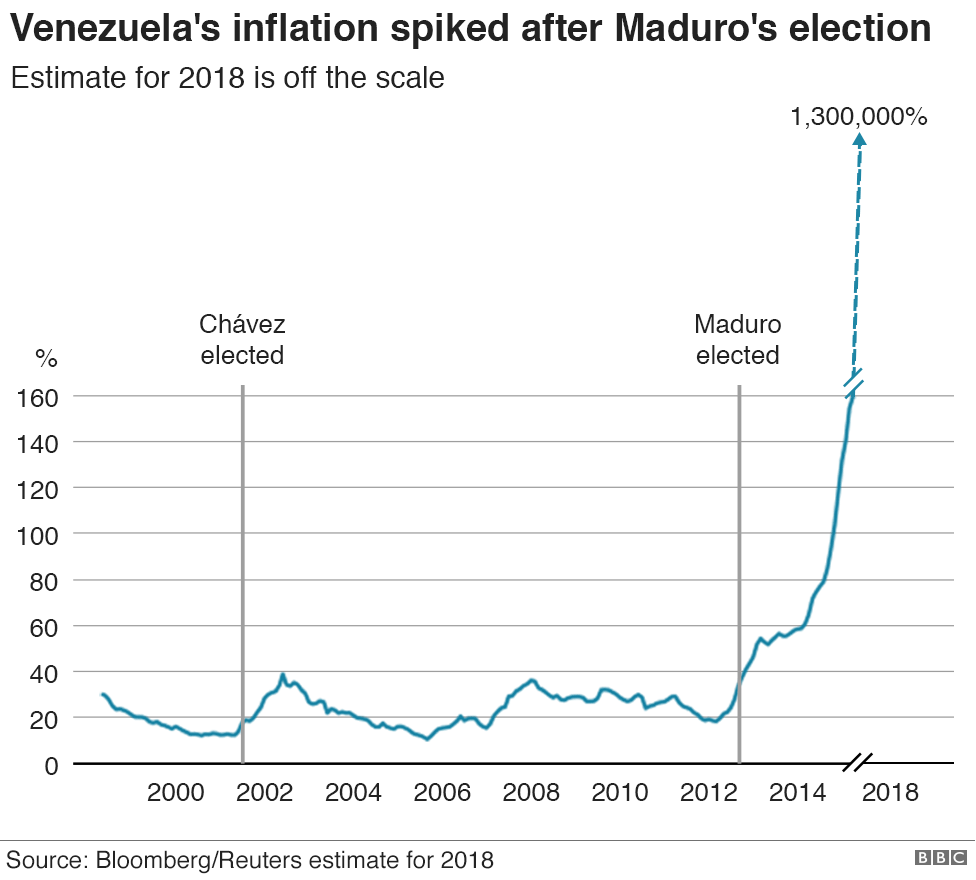
The inflation in Venezuela didn't start overnight. It was a slow build from the late 2000s that became unmanageable by 2016 and has been catastrophic since. Oil revenue made up roughly 95% of export earnings at its peak, and when prices collapsed in 2014, the government had no diversified economy to fall back on. Rather than adjust spending, they printed money. Massive amounts of it. The Central Bank of Venezuela issued bolívars faster than the economy could produce goods, and prices responded accordingly. I spent three years in Caracas between 2017 and 2020, and the first thing you notice is how fast prices move during a single shopping trip. You walk into a supermarket at 9 AM with a price list you photographed the night before. By the time you reach the checkout at 9:40 AM, the total has gone up roughly 8 to 12 percent. Not because the store is being malicious, but because the electronic register automatically updates prices multiple times a day based on the parallel exchange rate. You literally cannot plan a budget in advance because the baseline currency changes value between the time you decide what you need and the time you pay for it.
Venezuelas Unrelenting Inflation Crisis The Causes Devastating Effects And Overdue Solutions
The causes break down into a few overlapping categories. First, fiscal monetization: the government ran chronic deficits and the Central Bank financed them directly. Second, price controls imposed on basic goods from around 2003 onward created severe shortages because producers couldn't cover their costs at set prices. Third, a controlled exchange rate system meant there were multiple parallel rates, and businesses had to navigate what was essentially a black market for dollars just to import anything. The effects are what you'd expect from any hyperinflation but amplified by the structural weaknesses unique to Venezuela. Industrial output collapsed. Most factories closed because they couldn't import raw materials at official rates and couldn't compete with imported goods at parallel rates. Food insecurity became widespread. The population dropped by an estimated 7 to 8 million people who left the country, which isn't just a humanitarian statistic but an economic one: the workforce shrank dramatically, and remittances from abroad became a critical lifeline for those who remained. Here's something beginners in macroeconomics often miss when they study Venezuela: the dollarization that emerged was never official. It was ad hoc, uneven, and actually made things worse in some ways. When you have businesses pricing in dollars but paying workers in bolívars at fluctuating rates, you create a two-tier economy where access to dollars determines your standard of living. I watched a friend who worked for an NGO with a dollar salary buy an apartment in 2019 while his colleague at the same organization making bolívar wages couldn't afford to replace his refrigerator. The inflation rate itself is only half the problem. The currency fragmentation is what the society.
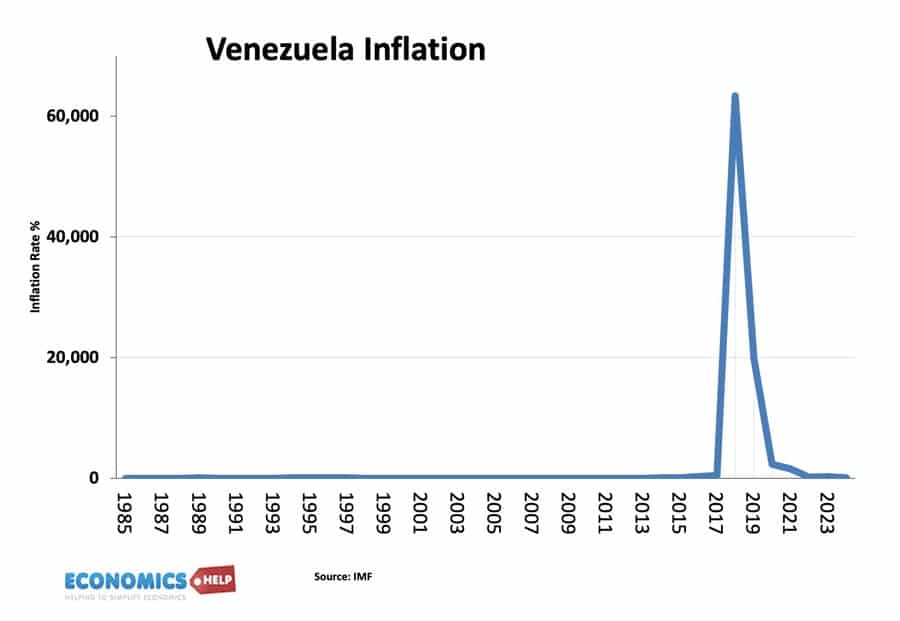
There's also a technical detail that rarely gets explained clearly. Venezuela's hyperinflation peaked at an annualized rate above 10,000 percent in 2018, but the government stopped publishing reliable CPI data after 2017. Independent economists like Alejandro Grey at USB and the team at El National use alternative methodologies: tracking shelf prices directly, using parallel exchange rates as a proxy, and applying the GDP deflator from limited official figures. The numbers vary by methodology but all point to the same conclusion. Even after the apparent slowdown in 2021 and 2022, inflation remained in the high hundreds of percent annually according to most independent sources. The solutions that have been proposed over the years fall into a few buckets, and none of them are simple. Full official dollarization would eliminate the currency risk overnight but means giving up monetary policy entirely. That worked partially in Ecuador but requires having enough dollars in reserve to back transactions, which Venezuela doesn't have. Monetary reform with a new currency, which they attempted with the sovereign bolívar in 2018 and the digital bolívar in 2021, doesn't solve anything unless you simultaneously fix the fiscal deficit and restore credibility. It's like renaming a bottle without changing what's inside. The most practical path that economists generally agree on involves three sequential steps. First, achieve fiscal balance or at least stop financing the deficit through the Central Bank. This is politically the hardest part because it means cutting subsidies, reducing the public payroll, and dealing with pension obligations. Second, establish a unified exchange rate. The current system with multiple rates is a distortion engine that rewards connectedness over productivity. Third, rebuild institutional credibility through an independent Central Bank with a clear inflation target. None of this happens in isolation. Remove any one pillar and the whole structure collapses again.
Get the Full Details

I've seen people recommend crypto or Bitcoin as a solution, and there's a grain of truth to it. Venezuelans do use crypto extensively for remittances and as a savings vehicle. But crypto doesn't solve the underlying problem of domestic price setting. If your government still prints money to finance deficits, crypto adoption just becomes another parallel market rather than a stabilization mechanism. It's a coping strategy, not a solution. The humanitarian impact remains severe. The Inter-American Development Bank estimated that poverty rose from 49 percent in 2014 to over 90 percent by 2019. Life expectancy dropped by nearly seven years between 2013 and 2020. Healthcare systems collapsed because hospitals couldn't afford supplies and doctors emigrated. These aren't side effects. They're the direct result of inflation destroying the purchasing power of wages and savings over nearly a decade. What's overdue is political will. The technical prescriptions have been written in papers and policy briefs for years. What hasn't happened is the internal consensus needed to implement them. Until there's a government willing to accept the short-term pain of fiscal adjustment and institutional reform, the cycle continues. The inflation slows, people get complacent, then the structural imbalances pile up again and it accelerates. That's the pattern I observed firsthand, and it's the pattern that keeps repeating.