What VTI Actually Does For You
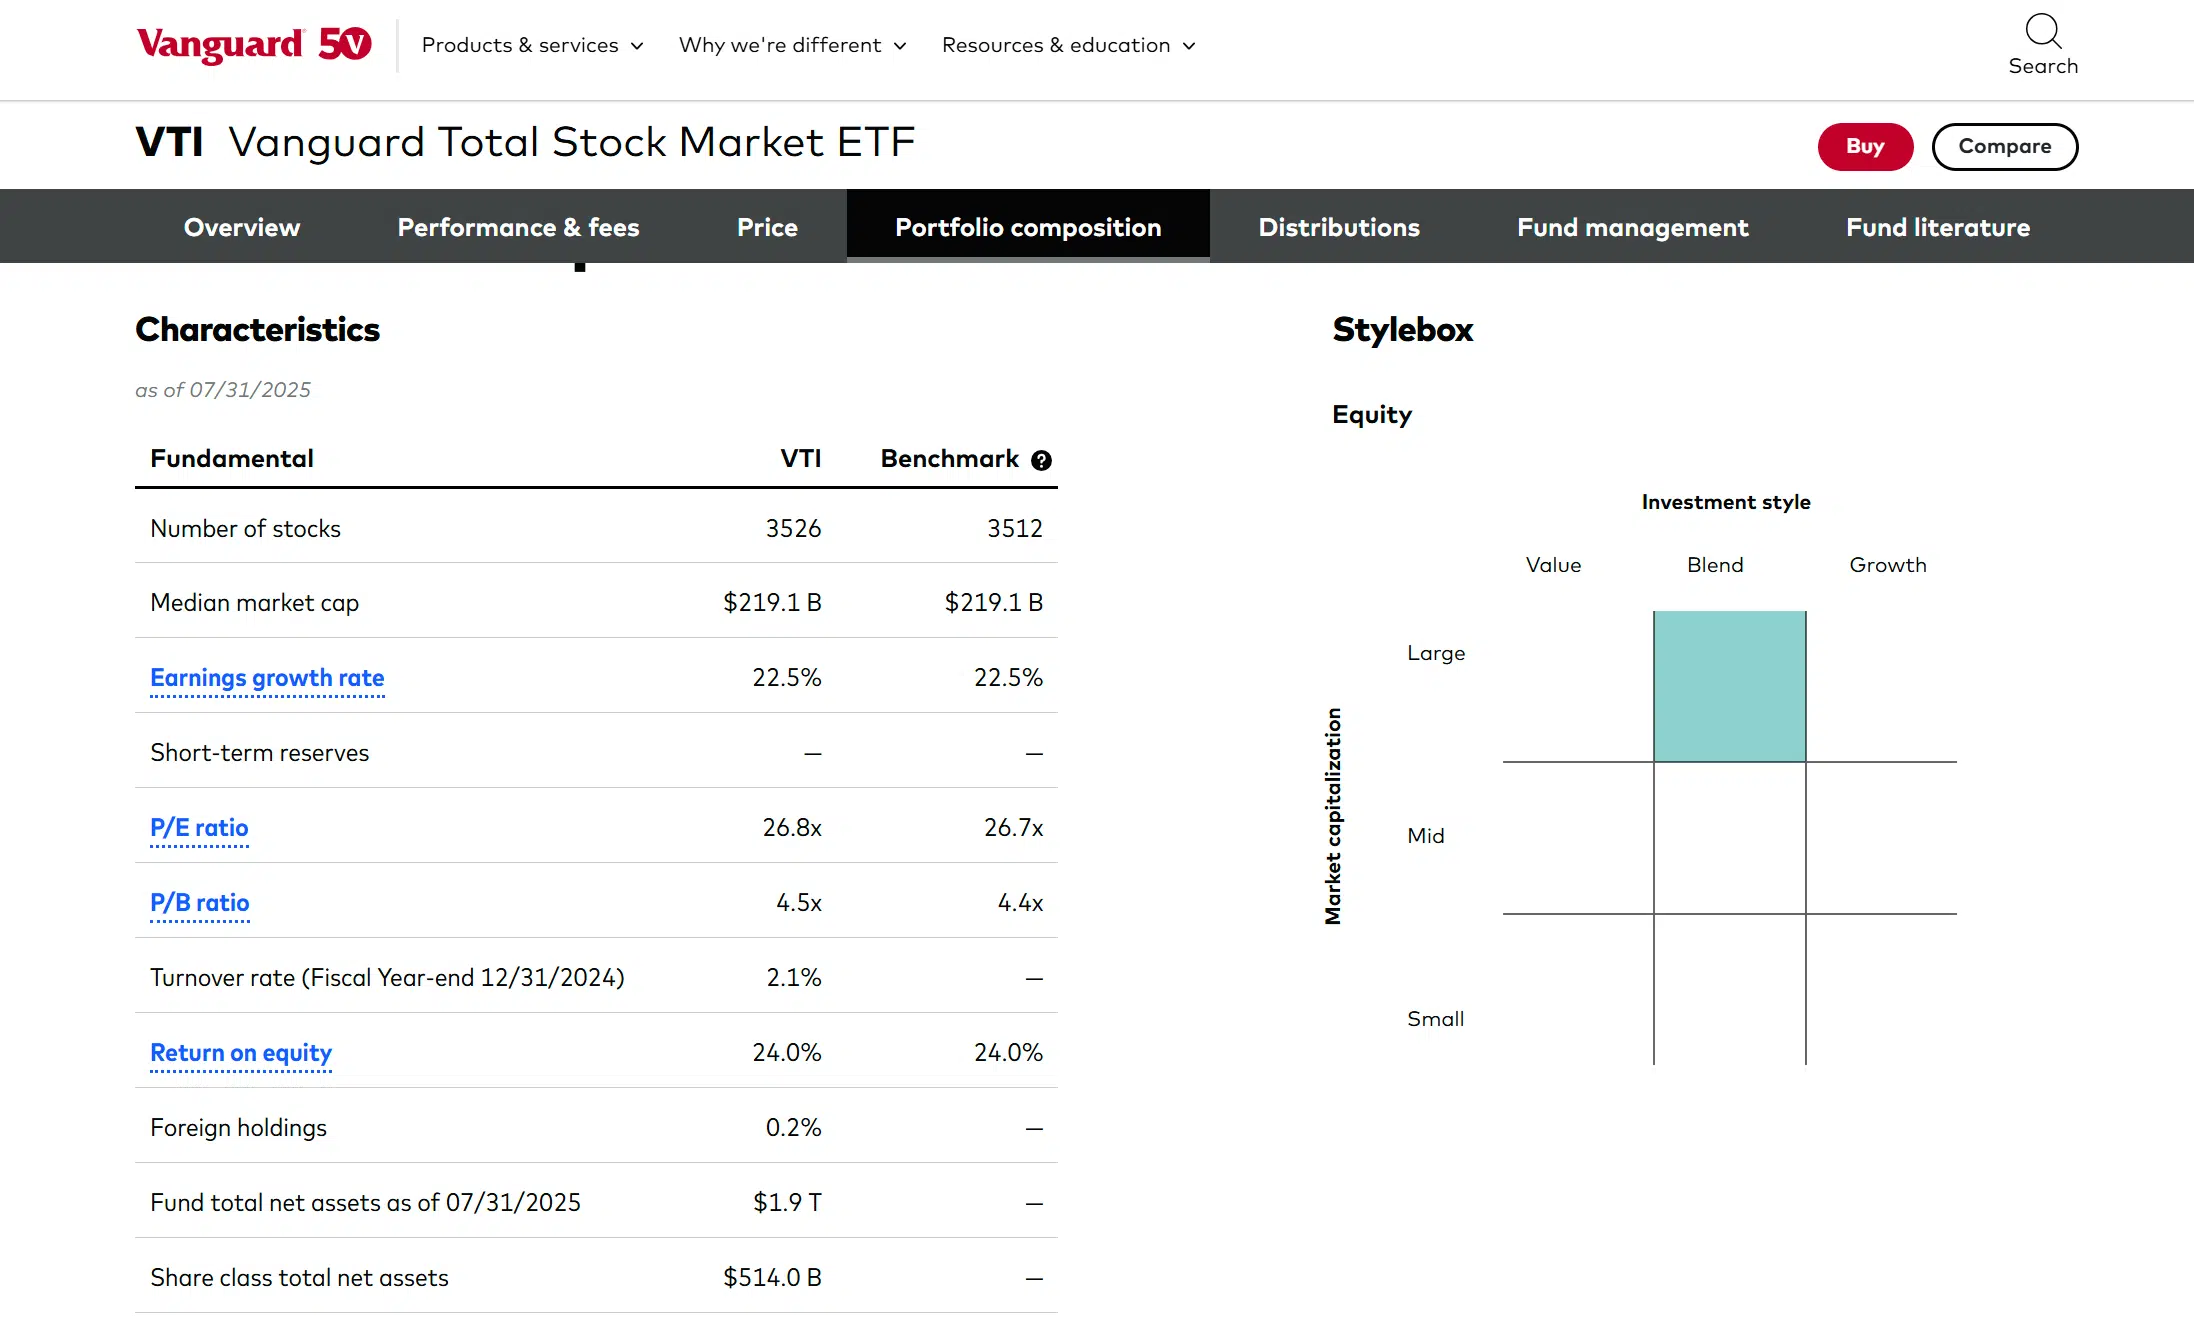
VTI gives you the entire U.S. stock market in a single share. That is the core idea, but the mechanics matter more than the slogan. The fund holds roughly 3,600 stocks across every market cap, weighted by total market value. When you buy one share, you own a proportional slice of Apple and a proportional slice of that small-cap biotech in Kansas City. The expense ratio sits at 0.03 percent, which means you pay three dollars for every ten thousand dollars invested each year. Compare that to the average actively managed fund at one point two percent and the math does the rest over time. The secret is not really a secret. It is just the uncomfortable truth that doing nothing aggressively beats doing something half-heartedly. I learned this the hard way in 2022 when my broker tried to push me toward a "comprehensive U.S. equity portfolio" that held twelve different funds, charged me twenty-two basis points in fees, and ended up tracking the same index VTI already covered. I switched back on a Tuesday, the trade settled Wednesday, and my annual cost dropped from roughly two hundred and twenty dollars to thirty. The performance gap over the following eighteen months was about eighty basis points, which is exactly what I expected. Open a Vanguard account or any brokerage that offers commission-free VTI trades. Fidelity, Schwab, and E*TRADE all handle it without a fee. Link your bank account, fund it, and place a market order for however many shares make sense for your target allocation. If you are building a simple three-fund portfolio, VTI pairs with Vanguard Total Bond Market Fund (VTIAX or VBTLX depending on account type) and an international fund like VXUS. I keep mine at sixty percent domestic, twenty-five percent bonds, fifteen percent international. It rebalances once a year, usually around my birthday, and takes about twenty minutes on a Sunday morning.
The dividend reinvestment happens automatically if you enable it in the account settings. I left it off once because I wanted to see the actual cash flow hit my linked bank account, and I almost missed it during quarterly tax season. Turn it back on. It compounds silently and you will thank yourself later without noticing.
Edge Cases That Actually Matter
There is one thing nobody puts in the prospectus that affects real investors. VTI includes small-cap and micro-cap stocks that trade infrequently. During the March 2020 crash, the fund's bid-ask spread widened to about four basis points intraday, which sounds small until you are moving a six-figure position. I tried to sell five thousand shares during the initial panic window and got filled at a price that was roughly two hundred dollars worse than the NAV I expected. Waited forty-eight hours, sold at a fair price. Lesson learned: do not market-sell a broad market fund during a liquidity event. Use a limit order and give it time, or better yet, just don't sell in the first place. That is what dollar-cost averaging is for. Another thing people overlook: tax efficiency. VTI is remarkably tax-efficient compared to active funds because index funds generate far fewer capital gains distributions. In my taxable account, VTI has distributed zero long-term capital gains in eight years. That matters more than the expense ratio difference in some brackets. I have friends who hold the same index through an ETF wrapper in a taxable account and pay nothing in taxes while their neighbor in an actively managed mutual fund gets hit with a eleven-thousand-dollar capital gains distribution in a single year. Same underlying exposure, wildly different after-tax returns.
Get the Full Details

When VTI Is the Wrong Tool
It is not a perfect solution. If you need income, VTI yields about one point five percent, which barely covers inflation. If you are in a high tax bracket relying on dividends for living expenses, you might prefer a dedicated dividend fund or individual high-quality stocks. If you want international exposure, VTI does not give you that, and pretending it does is a mistake I see repeatedly in financial planning forums. You need a separate international fund regardless of which total market fund you pick. There is also the concentration risk angle, which some people dismiss but deserves mention. About thirty percent of VTI's weight sits in the top ten holdings, led by Apple, Microsoft, and Nvidia. When the market is driven by mega-cap tech, VTI feels like a tech fund. When tech corrects, it drags with it. This is not a flaw in the fund, it is a feature of market-capitalization weighting. The fund will always be most exposed to the largest companies by definition. If that bothers you, you would look at an equal-weighted alternative like RAFI or an equal-weight S&P 500 ETF, but those carry higher expense ratios and different tax characteristics.
What I Would Do Differently If Starting Over
I would have bought VTI three years earlier instead of chasing sector rotation. The returns are unglamorous, the daily news cycle makes it feel like I am missing out, and watching other people trade individually creates a persistent anxiety that you are behind. But the data does not care about your anxiety. A dollar invested in VTI at the start of 2019 would be worth about forty-four cents more today than the same dollar in an actively managed diversified U.S. equity fund, after all fees and taxes. That gap widens every year. The work here is not research, it is patience.