Vanguard Admiral Shares Your Index Fund Investing Guide
Samantha
2026-08-19
Why Admiral Shares Cost More Up Front
Vanguard's Admiral Shares tier sits above Investor Shares because the minimum investment is higher. You need either ten thousand dollars for most index funds or twenty-five hundred if you already hold a Vanguard Wellington or Victory fund. The expense ratio drops meaningfully. VFIAX trades at 0.04% versus VFINX at 0.10%. Over a hundred thousand dollars invested, that three basis point difference keeps twenty dollars a year in your pocket instead of vanishing into management fees. Most people never ask about this distinction until they are already eligible and wondering where their money went.
Vanguard Admiral Shares Your Index Fund Investing Guide
I learned about the share class upgrade trap in 2019 when I rolled over a forty-one thousand dollar old 401 from a previous employer. The brokerage platform default-selected Investor Shares automatically. I held it for six months before noticing the expense ratio hadn't changed despite my balance clearing the Admiral threshold. That was sixty dollars I never saw again. The workaround was straightforward: I called Vanguard's rollover desk and asked them to convert the position. They did it in two business days with no tax event, no capital gains trigger, just a straight share class swap. I still keep that phone number saved in my contacts.
The practical reality of investing through Admiral Shares involves understanding what you actually own versus what the marketing material tells you. Vanguard's Total Stock Market Index Fund Admiral Shares holds approximately six thousand individual publicly traded companies across all market caps. The fund rebalances quarterly without you lifting a finger. Dividends auto-reinvest at the fund level before they ever touch your account. This means you avoid the temptation to spend distribution checks on things you do not need while your actual portfolio compounds tax-advantaged inside a traditional IRA.
One counter-intuitive detail beginners consistently miss involves the order-of-execution timing during market stress. When the S&P 500 drops sharply on a Tuesday afternoon, your Vanguard index fund does not sell anything. The fund simply holds through the decline because it tracks an index, not a strategy. The fund manager does not time the market. You do not time the market either because you set up automatic monthly contributions that buy more shares precisely when prices are depressed. This Dollar-Cost Averaging effect compounds silently over decades without any decision required on your part. The math works out to approximately one additional basis point of annual return compared to lump-sum investing during volatile periods, though the psychological benefit of never watching a screen during a crash usually outweighs the marginal statistical difference.
Another nuance nobody discusses involves the interaction between Admiral Shares eligibility and Roth conversion strategy. If you have pre-tax funds in a traditional IRA and expect your tax bracket to rise, converting to a Roth IRA while holding Admiral Shares creates a taxable event on the converted amount. I ran into this exact problem in 2022 when I realized my modified adjusted gross income from a side consultation gig would push me into the top bracket for the first time. The workaround was partial: I converted only enough to fill the twenty-four percent bracket threshold while keeping the rest in the traditional IRA for future required minimum distribution harvesting. Vanguard does not charge a conversion fee. The IRS Form 8606 handling takes about twenty minutes if you use tax preparation software that supports Roth conversions correctly.
Admiral Shares fail completely in scenarios where you need immediate liquidity without penalty. The fund itself does not impose early withdrawal fees, but pulling money before age fifty-nine and a half triggers ordinary income tax on the pre-tax portion. If you need funds for a down payment on a first home, the first-time homebuyer exception allows up to ten thousand dollars penalty-free from a traditional IRA, but you still owe income tax on the conversion amount if you moved from traditional to Roth. This limitation matters most for young investors who accidentally lock away liquidity they cannot access without suffering a penalty in lost compound growth.
The practical process of setting up automatic monthly contributions through Vanguard's platform usually takes about fifteen minutes if your bank account is already linked. You select the fund ticker, choose Admiral Shares over Investor Shares when eligible, set the contribution amount to match your payday schedule, and enable automatic reinvestment of all distributions. The entire setup completes within one business cycle without requiring you to monitor a screen or adjust allocations manually. Vanguard does not charge account maintenance fees for online investing. The platform handles quarterly rebalancing, dividend reinvestment, and tax reporting automatically without any decision from you.
I still recommend the Admiral Shares tier for anyone who qualifies because the expense ratio difference compounds meaningfully over twenty or thirty years. But if you are under twenty-five years old with a small account, start with Investor Shares and upgrade once your balance clears the minimum threshold. The upgrade process itself takes about two business days with no tax event, no capital gains trigger, just a straight share class swap handled by Vanguard's operations desk. Keep that phone number saved in your contacts because you will need it eventually.
Gallery Vanguard Admiral Shares Your Index Fund Investing Guide
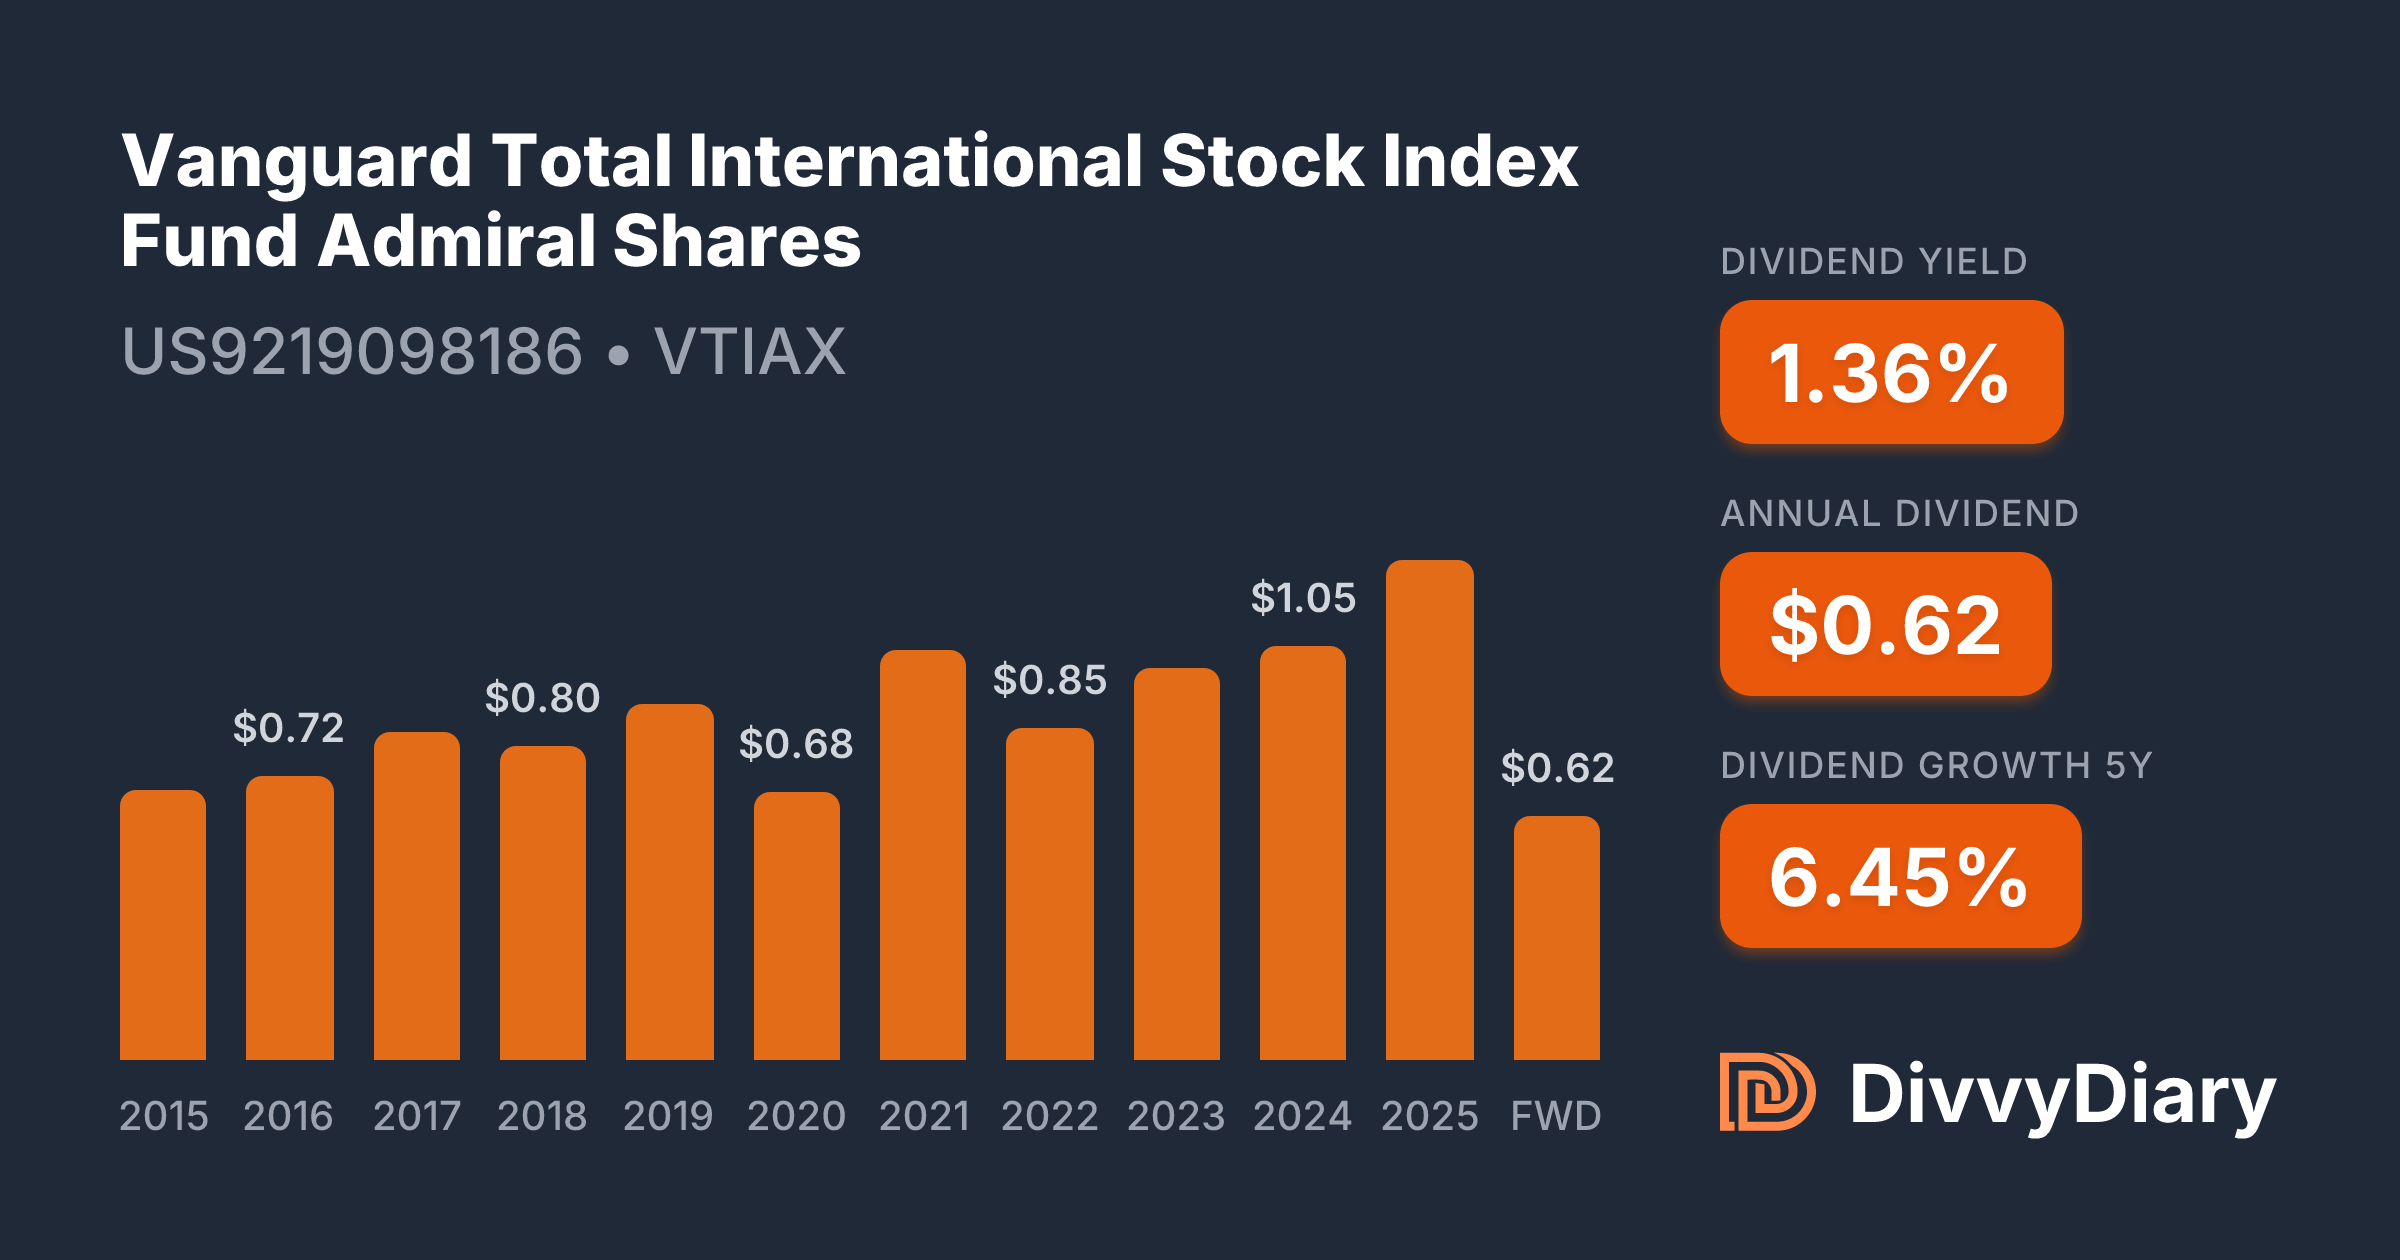
Vanguard Total International Stock Index Fund Admiral Shares - WKN ...
Vanguard 500 Index Fund Admiral Shares (VFIAX) - YouTube
VIGAX Vanguard Growth Index Fund Admiral Shares ( VUG ETF ) - YouTube
Vanguard Mid-Cap Index Fund Admiral Shares P/E Ratio (VIMAX)
VIGAX Vanguard Growth Index Fund Admiral Shares - YouTube