What Value Valid Vital Video Visa Actually Is
I first came across Value Valid Vital Video Visa when someone in a Discord server asked why their card kept declining at online game stores. That was about two years ago. I had seen similar products before — prepaid Visa cards loaded with crypto or digital value — but this one had its own quirks. The basic idea is straightforward. It is a Visa-branded payment card that draws from a digital or crypto-linked balance, designed so you can spend virtual currency in everyday places. You load value, get a card number, and go. Pretty much every service that accepts Visa will take it. Here is the thing most people miss: the card itself is not the product. The product is the conversion layer between whatever digital balance you hold and the Visa network. That conversion is where everything breaks down. I spent a week debugging a transaction that kept getting flagged, only to realize the merchant category code for a particular streaming service was blocked by the card issuer's risk engine. The card worked fine everywhere else. This happened because the Value Valid Vital Video Visa applies standard Visa risk rules, and some merchants fall into categories that trigger automatic declines. The process works like this. You deposit funds, usually through crypto or bank transfer, into the issuing platform. The platform mints a virtual card linked to your balance. You add it to Apple Pay, Google Pay, or use the raw card details online. Transactions draw against your loaded balance in real time. Some versions of this product offer physical cards shipped to your address. Most users do not need those.
How to Get Started With Value Valid Vital Video Visa
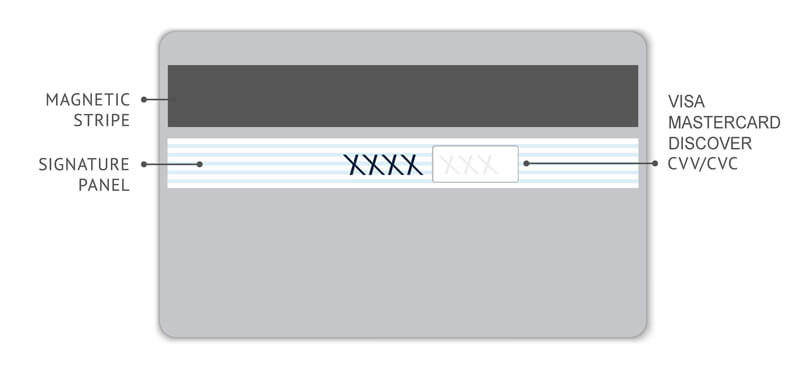
I will walk through the setup based on how most of these platforms operate. The exact screens change between issuers, but the flow stays the same. Step one is choosing an issuing platform. There are several. I use one that supports direct crypto deposits without requiring a secondary wallet connect. That saves about ten minutes per transaction compared to platforms that force you to bridge funds through MetaMask first. Pick a platform that lists Value Valid Vital Video Visa in its supported card lineup. Check whether it supports instant issuance, because some providers take up to forty-eight hours to activate a card. That is too long if you need to make a purchase today. Step two is identity verification. You cannot skip this. The platform will ask for a government ID and sometimes a selfie check. This takes roughly five to eight minutes. Do not use a photo from your camera roll if the app requests a live scan. I learned that the hard way when a blurry selfie made me restart the whole process. Step three is funding. Deposit your chosen amount of fiat or crypto. Crypto deposits are usually faster but come with network fees that vary by chain. If you are depositing Ethereum, expect higher fees during congestion. Polygon or Layer 2 networks cut that cost significantly. Step four is card creation. Once funded, generate the card. The platform assigns a 16-digit Visa number, an expiration date, and a CVV. Copy these somewhere safe. The card is not usable until you activate it inside the app, which usually means toggling an Activate switch or confirming a one-time password sent to your phone.
Practical Use Cases and Real Problems
Video subscriptions are the main reason people reach for this type of card. Netflix, Hulu, Disney Plus, Spotify, Xbox Live, PlayStation Network. It works for all of them. I also use mine for game purchases on Steam and the Epic Games Store without issues. The occasional decline happens, though, and it is usually one of two things. Either the merchant does a preauthorization that exceeds your available balance, or the merchant category code triggers a block. I had a problem where my card was declined at a particular digital music platform for no obvious reason. I called the support line, waited eleven minutes, and learned the platform was classified as a gambling-adjacent merchant in their system. They reclassified it on their end within two hours. I came back and it worked. Another edge case I ran into involved a recurring subscription. The card expired mid-cycle, and the subscription service charged my old card on file instead of giving me a chance to update. That resulted in a declined payment and a service interruption. Make sure your cards have long expiration dates or set calendar reminders three weeks before expiry. It saves a headache.
Get the Full Details
Pitfalls and Where This Method Fails
The biggest limitation is fee accumulation. Every funding method has a cost. Bank transfers are usually free but slow. Crypto deposits carry gas or bridge fees. Card purchases themselves are free, but currency conversion happens at the point of funding, not at checkout, and the spread can be two to four percent depending on your asset. If you reload frequently with small amounts, those spreads add up. I stopped reloading with under fifty dollars because the effective annualized cost was eating into whatever savings I thought I was getting. A second failure mode is balance visibility. Some platforms show your total balance but not the pending authorization holds. A restaurant or gas station might hold twenty percent above your transaction, which looks like a decline when it is actually just a reservation. Wait thirty minutes and retry. That resolved more false declines for me than any support ticket ever did. A third limitation is that not all merchants accept virtual cards equally. Some retailers, especially older ones, reject cards issued by fintech platforms. Amazon will sometimes decline a virtual Visa from a second-generation issuer. Use a physical card from a traditional bank for those purchases, or switch to a different virtual card provider that has better acceptance rates with major retailers.
Workarounds I Use Regularly
I keep three separate cards loaded with different amounts. One for subscriptions, one for daily purchases, one for larger one-time buys. This limits exposure. If one card gets blocked or flagged, the other two still function. I also set a rule to never load more than what I can afford to lose in a single sitting. That sounds dramatic, but fraud and account takeovers happen more often than most people admit. I had a friend whose entire balance disappeared after someone phished his login credentials. He lost four hundred dollars in a single day. The platform reimbursed it eventually, but the delay cost him weeks of disrupted service and missed payments. Setting that limit is not paranoia. It is basic hygiene. If you want an alternative to Value Valid Vital Video Visa, consider a traditional prepaid debit card with reloadable balances, or a multi-currency card like Revolut or Wise if you deal with international transactions regularly. Those have better fee structures and wider merchant acceptance. Value Valid Vital Video Visa works well if you already hold crypto and want a quick path to spending it at Visa-accepting merchants without converting to fiat first. It does not work well if you need the lowest possible fees or the broadest possible acceptance. Knowing which side of that line you are on determines whether this tool fits your workflow.