Understanding Utah's Housing Engine: Current Trends Statistics That Define The Mountain States Real Estate Landscape
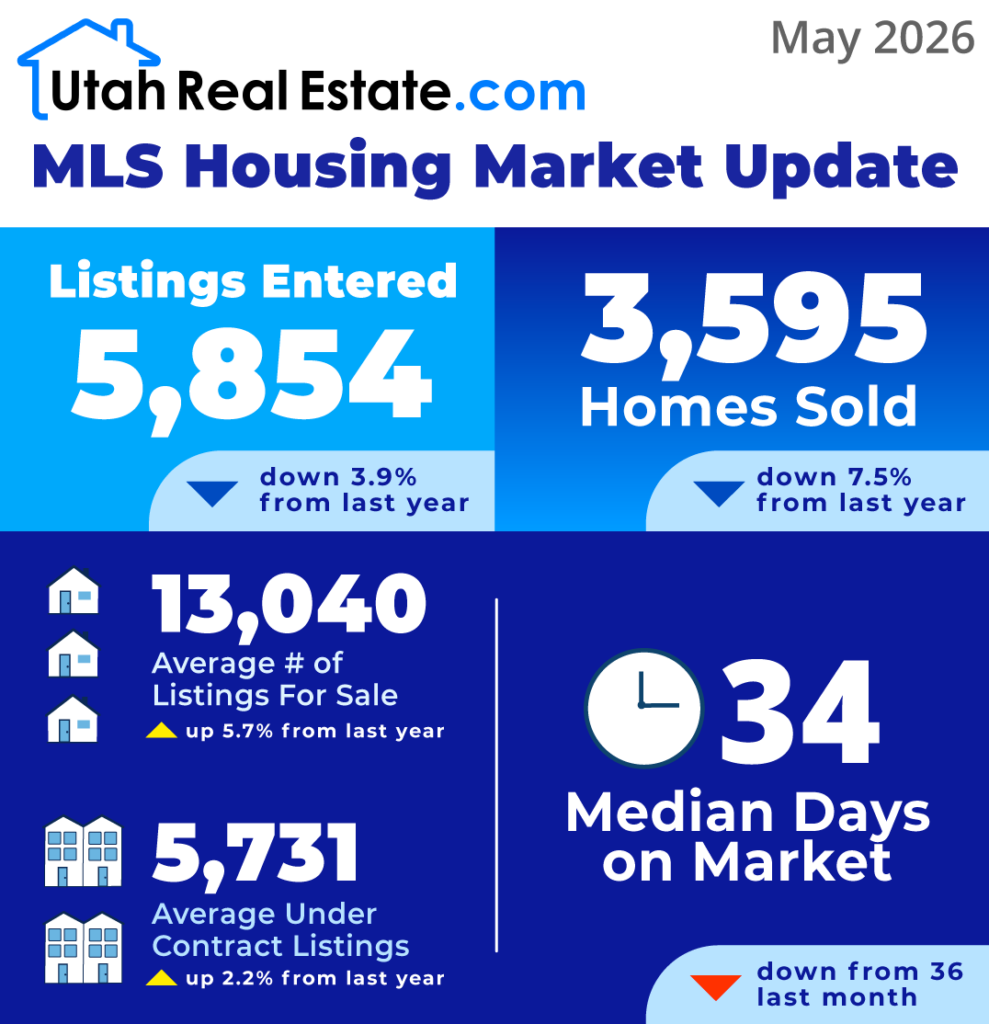
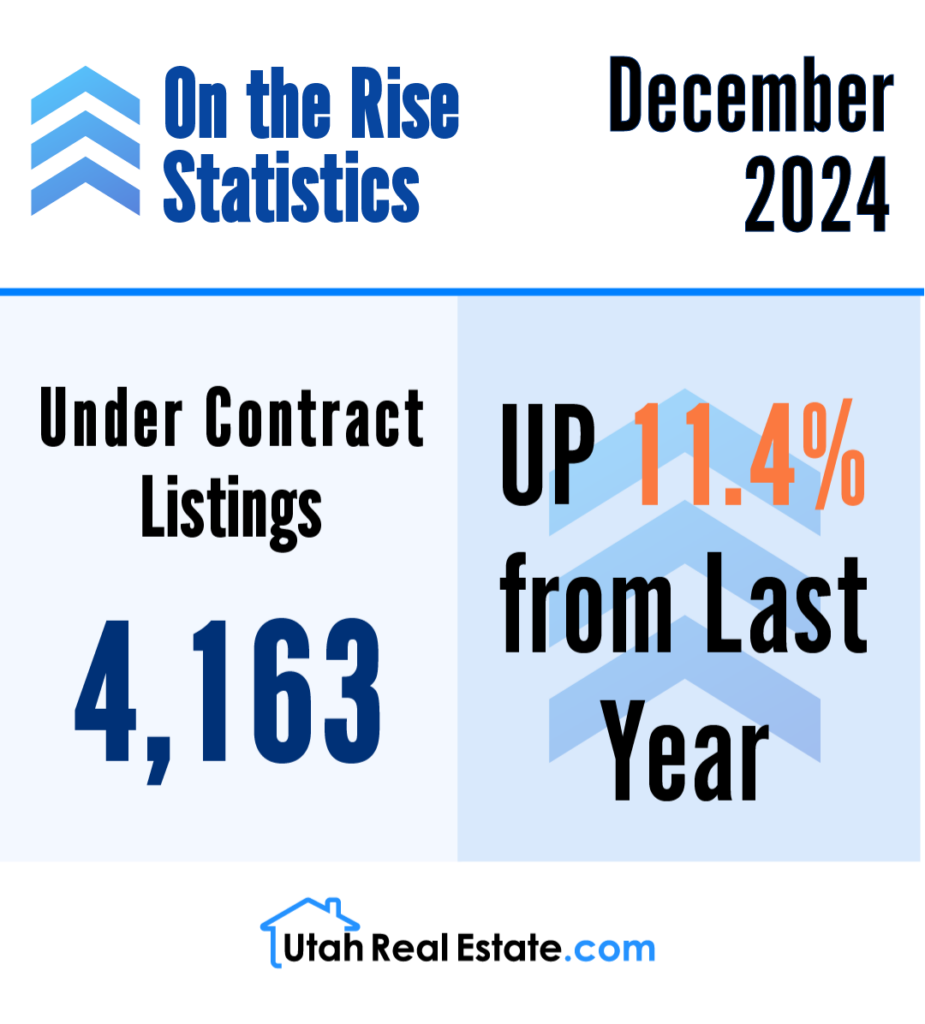
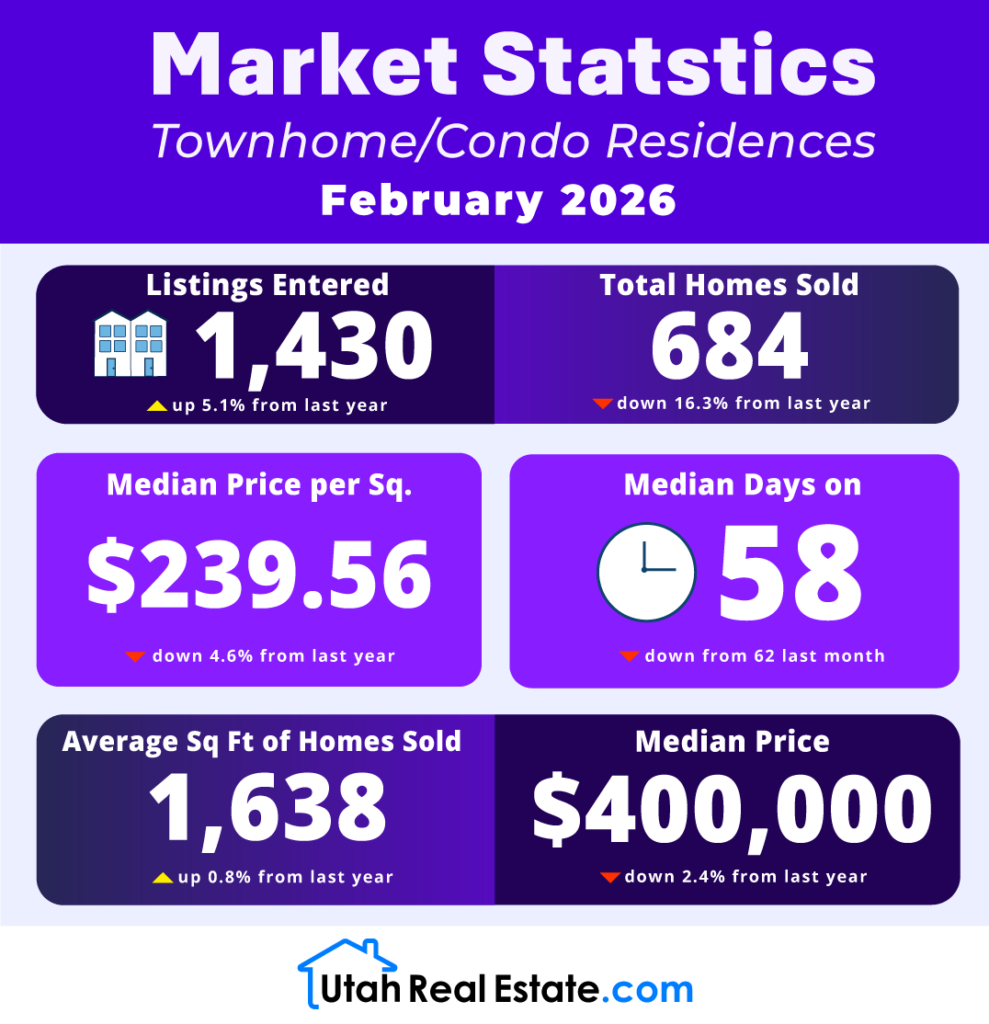
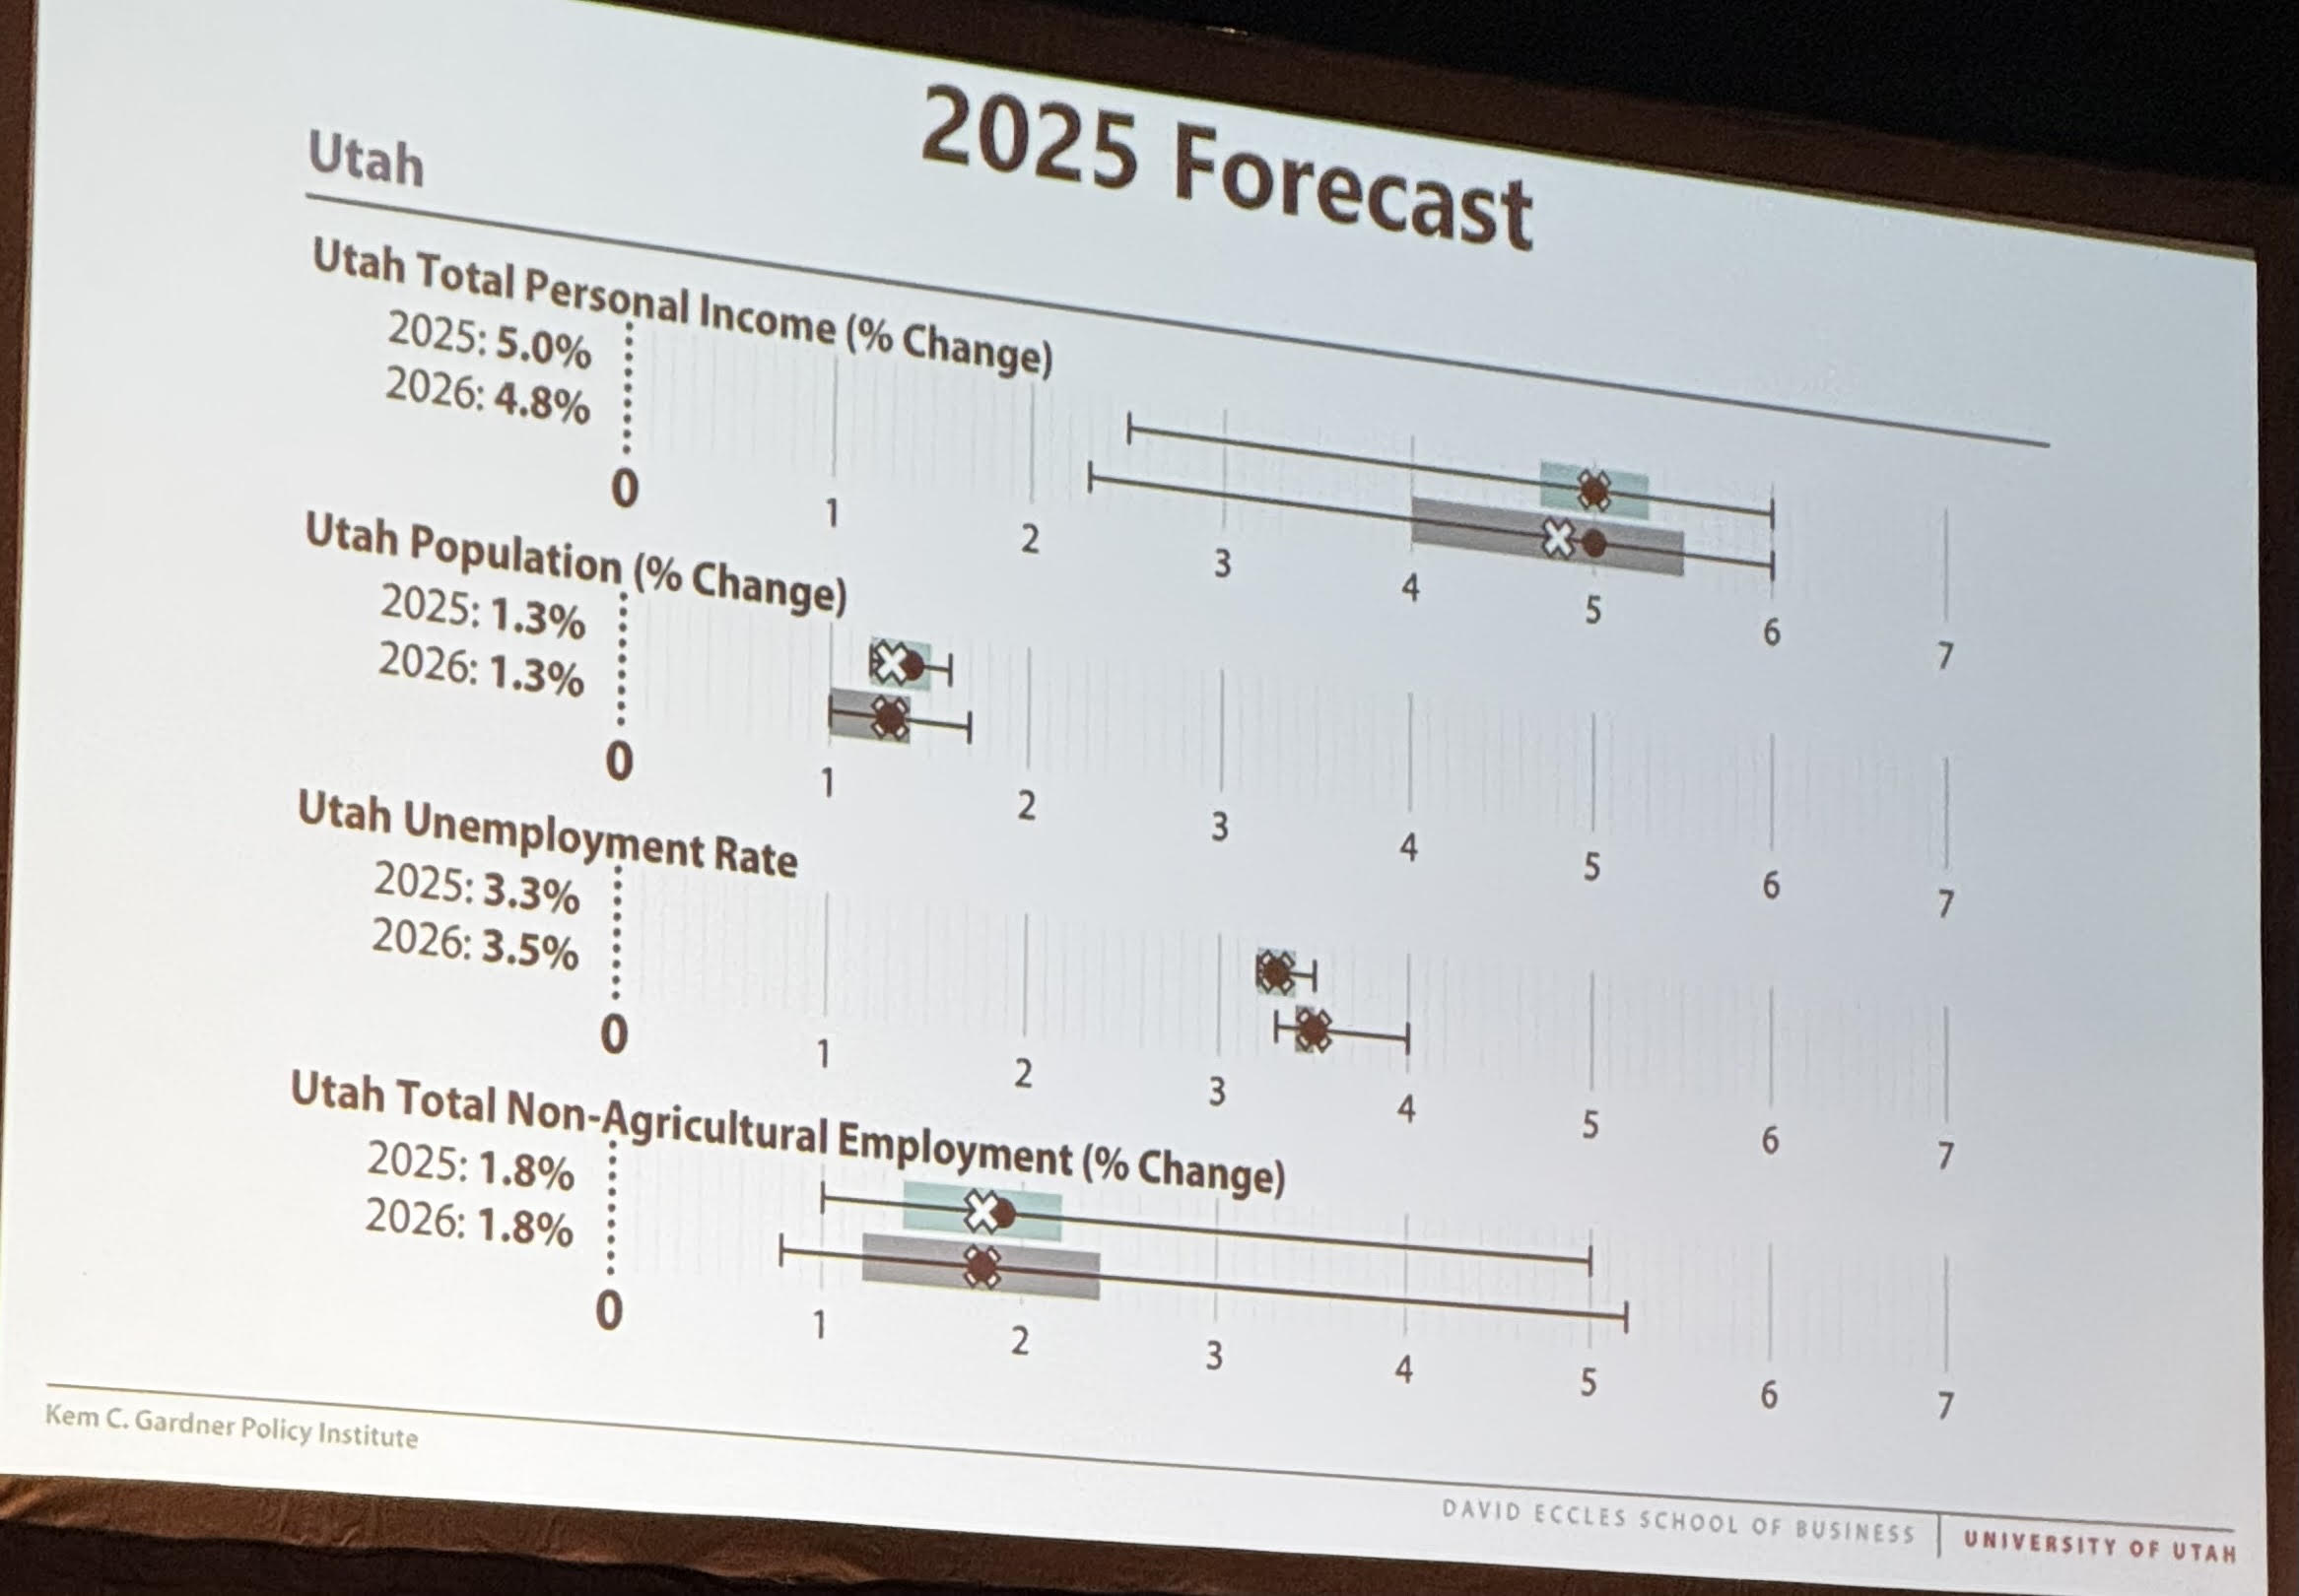
Utah isn't just a state with nice mountains. It has become one of the most studied housing markets in the country, and for good reason. The population has been growing at roughly 1.8 to 2 percent annually over the past decade, which is well above the national average. That kind of sustained demographic pressure creates market conditions that don't follow normal assumptions. I'm going to walk through what's actually happening right now, the numbers behind it, and how to read the data without falling for noise. Let me start with the raw numbers. As of mid-2025, the median home price in Utah sat somewhere in the $470,000 to $510,000 range depending on which source you trust. That represents a year-over-year increase of roughly 4 to 7 percent in most metro areas. Salt Lake County leads the pack, with neighboring counties like Utah County and Davis County showing slightly different trajectories. Utah County has been running hotter, partly because younger families are priced out of the Salt Lake market and are pushing further east. West Valley City and South Jordan are the kinds of micro-markets that move fast and can flip from seller-favorable to balanced within a single quarter. Inventory remains the central problem. Months of supply across the state hovers around 1.5 to 2 months, which is well below the six-month threshold that economists consider balanced. In practical terms, that means a typical home in a desirable area will see multiple offers within its first two weeks on the market, especially if it's priced correctly from day one. Overpriced listings sit and stagnate, and then they get renegotiated down to where a fair market price should have been from the start.
Demographics matter more than most people give them credit for. Utah has the youngest median age of any state at roughly 31 years old. That creates a long runway of household formation. People are buying homes earlier and in greater numbers than the national pattern would predict. The out-of-state migration piece is also significant. During the pandemic era, Utah absorbed substantial net domestic migration, particularly from California and Washington. That wave has slowed considerably in 2024 and 2025, but it wasn't a blip. Those buyers entered the market at elevated price points and they're still influencing certain submarkets, particularly in the northern Wasatch Front corridor. Interest rates changed the calculus dramatically. When mortgage rates pushed past 7 percent in 2023 and stayed elevated through much of 2024 and 2025, purchase volume dropped. Most estimates put transaction volume somewhere in the 55,000 to 65,000 range annually for the state, down from peaks near 80,000 in 2021. But here's the thing that people miss: price didn't drop proportionally with volume. The market didn't crash. It adjusted through slower turnover and tighter supply. Existing homeowners who locked in rates below 4 percent simply aren't selling. That's the lock-in effect, and it's the single biggest structural factoring supply right now. It's not that builders aren't building. They are, but new construction accounts for only about 15 to 18 percent of total transactions in Utah, and even that pace has moderated.
The Data Sources You Should Actually Trust
I've spent years sifting through housing data, and most people pull from the wrong place or interpret it incorrectly. The Utah Department of Commerce is a solid starting point. Their monthly housing dashboard breaks out permit activity, closing counts, and median prices by county. It's not the flashiest presentation, but it's accurate and it's free. The Salt Lake Board of Realtors publishes regional reports that tend to be more granular on metro-level trends. Utah Regional Multiple Listing Service is the actual MLS data, which is the most reliable source for listing and sales activity, though it requires a subscription. Be careful with Zillow's Zestimate and similar automated valuation models. They lag behind actual transaction data, especially in fast-moving markets like Utah where conditions can shift within a quarter. I've seen Zestimates off by 8 to 12 percent on individual properties in areas where there haven't been recent comparable sales. For rough market direction, they're fine. For decision-making, they're not reliable enough. One thing I wish more people understood is how to read the difference between list price and sale price. In Utah, the ratio of final sale price to original list price has been sitting around 98 to 101 percent depending on the month and the county. A ratio above 100 percent means homes are selling over ask, which signals a seller's market. Below 97 percent suggests buyers are gaining leverage. Right now, most of the state is clustered near that 99 to 100 percent range, which is a fairly tight equilibrium for a market this active.
Get the Full Details
What the Numbers Don't Tell You
Here's something that doesn't show up in any report: the way Utah's housing market behaves differently depending on whether you're looking at owner-occupied versus investor activity. In counties like Salt Lake and Weber, investor purchases have pulled back noticeably since 2022. Cash offers are less common than they were during the pandemic peak. But in outlying areas like Cache County or San Juan County, investor activity still represents a meaningful share of transactions, and those markets move on completely different fundamentals tied to local employment and energy sector cycles. Another blind spot is the rent-to-own and lease-option activity that exists in the shadows of official statistics. I've personally dealt with a situation where a buyer thought they were getting a straightforward purchase deal on a home in Riverton, only to discover the seller had already entered into a lease-option agreement with another party six months earlier. The contract was recorded but not obvious from a casual title search. That scenario is rare but it happens, and it's one reason I always recommend doing a full chain-of-title review before making an offer, not just a standard preliminary title report. It added about two days to the due diligence period but saved us from a potential legal mess. The other counterintuitive thing about Utah real estate is how local school district boundaries disproportionately drive pricing. A home in the same neighborhood but on the other side of a school district line can command $30,000 to $60,000 more simply because of the assigned elementary school. This isn't anecdotal. I've pulled comparables from both sides of district boundaries in Lehi and Pleasant where the only meaningful difference was the school assignment, and the price spread was consistent and measurable. Buyers who ignore this factor end up overpaying for location advantages they don't actually need or underpricing homes they're willing to accept lower-quality schools for.
How to Use This Data in Practice
If you're trying to make a decision based on these trends, the first step is to pick the right geographic level. Statewide averages are almost useless for individual decisions. You need county-level data, and ideally submarket data if your county is large enough. Salt Lake County alone contains dozens of distinct micro-markets that don't move in sync. Orem operates differently from Holladay, which operates differently from Taylorsville. When evaluating whether a neighborhood is heating up or cooling down, track three metrics together: days on market, the list-to-sale price ratio, and the inventory count month over month. If all three are moving in the same direction, you're seeing a genuine shift. If they're sending mixed signals, the market is in transition and you should be cautious about drawing conclusions from a single month of data. One month is noise. Three to six months is a trend. For prospective buyers, the practical takeaway is that waiting for a market correction isn't a strategy. The structural shortage of homes combined with continued population growth means prices are more likely to appreciate slowly or hold steady than to decline significantly. The better approach is to focus on affordability within your budget, get pre-approved with a lender who understands Utah's conforming and Jumbo loan thresholds, and be ready to move quickly when you find a property that fits. hesitation costs more than a slightly higher interest rate in this market.
For sellers, pricing correctly on day one is the single most important decision. The data consistently shows that overpriced listings in Utah end up selling for less than they would have if they'd been priced competitively from the start. The market punishes stubborn pricing with extended days on market, which signals to buyers that something is wrong with the property even when it isn't. A professional comparative market analysis from someone who actually tracks local transactions, not just someone who pulls automated reports, will save you tens of thousands of dollars. One more thing worth noting about Utah specifically: the state's lack of a broad-based local property tax in many areas and its relatively favorable overall tax environment continue to be pull factors for relocation. That demographic tailwind isn't going away soon. It changes the long-term demand curve in a way that short-term interest rate fluctuations can't fully offset. Anyone analyzing Utah housing without accounting for migration flows is missing a key variable.
Where the Data Falls Short
I should be honest about the limitations too. Utah's housing statistics have real gaps.Off-market transactions, particularly in the luxury segment, are poorly captured. Foreclosure and pre-foreclosure data is available but the timelines are slow, and Utah's non-judicial foreclosure process means those properties can move faster than the statistics reflect. Affordable housing and first-time homebuyer program data is scattered across multiple agencies with no centralized reporting system. If you're researching those topics, you'll spend considerably more time pulling from separate sources than you would for conventional market data. The permit data from the Department of Commerce tracks new construction starts but it doesn't reliably differentiate between speculative builder inventory and custom orders. A county might show strong permit activity, but that doesn't necessarily mean more homes are hitting the resale market. Some of that new supply goes directly to pre-sold custom builds that never enter the MLS. This disconnect between construction activity and available resale inventory is something I've had to explain to clients more than once when the numbers seemed to contradict each other. Ultimately, Utah's housing market is definable by a combination of strong population growth, constrained supply, and demographic patterns that favor sustained demand. The statistics tell a clear story when you look at the right level of granularity and cross-reference multiple sources. The people who make good decisions in this market are the ones who understand both the numbers and the structural forces behind them, and who don't mistake a temporary rate environment for a permanent market condition.