How to Track, Verify, and File Claims on USPS Money Orders
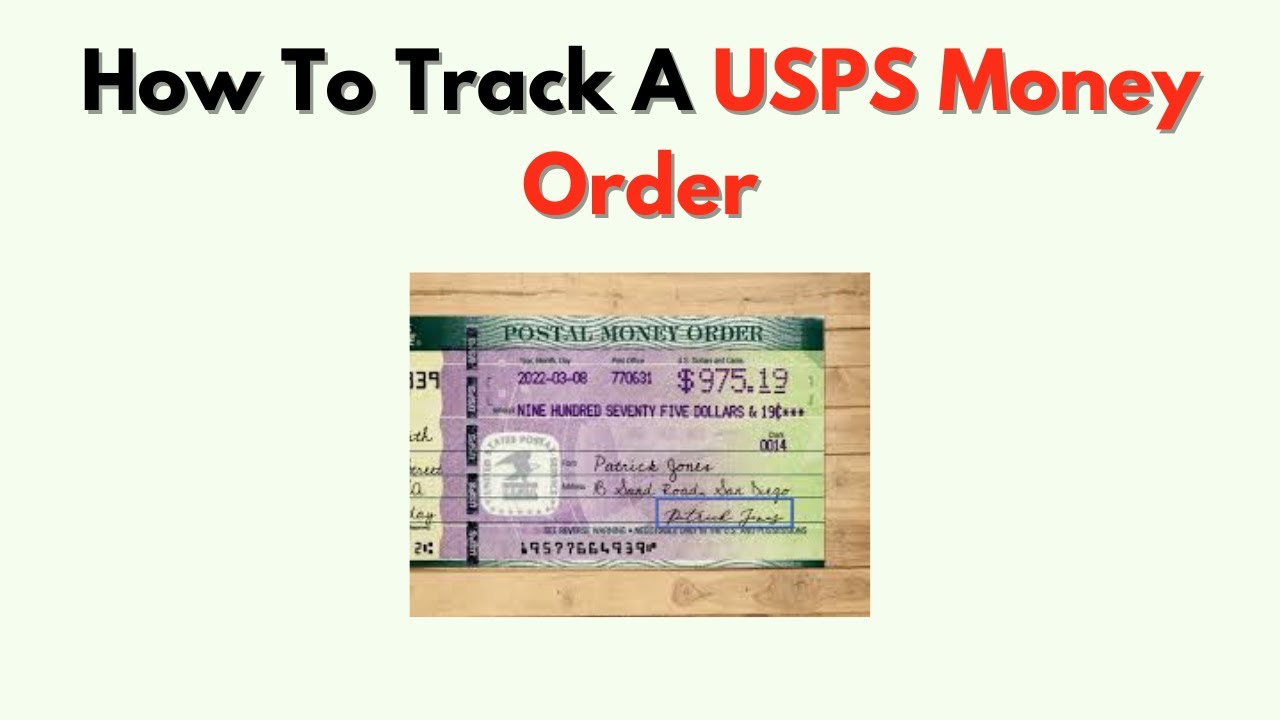
USPS money orders work a lot like cashier's checks from a bank. You get a receipt with a tracking number. That number is everything. Without it, you're in a much worse position than you realize. The tracking page is at usps.com. Look for "Money Order Services" in the tracking section. Enter the 18-digit money order number. The format is usually nine digits, a space, then nine more digits. Some older money orders have different formats, but those are extremely rare now. If the system says the number isn't found, double-check you typed it correctly. Mistakes happen more often than you'd think. Once you enter the number, the system shows whether it's been cashed. If it shows as cashed, you'll see the date, the city and state of the cashing location, and sometimes the name of the cashing entity. That's it. No detailed photo of the endorsed signature. No amount confirmation beyond what's printed on the face of the money order. Don't expect more than that.
I ran into a situation where someone sent me a money order through the mail, and the tracking showed it had been cashed in a different state than where I lived. The recipient claimed they never received the money order. The USPS tracking system had already closed out the item as delivered. Getting the original sender involved and reissuing the full amount took about three weeks. The key lesson is: always verify the tracking status on your end before assuming anything, and keep the purchaser's copy of the money order forever, not just until the transaction closes. I used to throw mine away after confirming delivery. That was a mistake. Here's what most people don't know about the verification side. The tracking system only updates when the money order is presented for cashing at a postal facility or certain authorized locations. If someone photocopies your money order and tries to cash it elsewhere, the system won't flag that attempt. There is no real-time fraud alert embedded in the tracking database. The verification is purely based on whether the physical item was scanned at a cashing point. Another thing nobody warns you about: if a money order is lost in transit before it reaches the recipient, the purchase receipt is your only proof. The USPS tracking system will show no record of delivery because the money order itself was never scanned into their system as a received item. In these cases, the sender has to file a claim directly. The claim process is painful, but it's the only path forward.
Step by step claim process for lost or stolen money orders
If you've lost your money order or it was stolen, your first move depends on whether you still have the original purchase receipt. If you have the receipt, go to usps.com and look for the "Claim for a Lost, Stolen, or Damaged Money Order" form. You can fill it out online or request a paper form. The online form is faster, usually processed within five to seven business days if everything is in order. Paper forms can take significantly longer because they get routed through a regional processing center first. You'll need to provide the money order number, the original purchase date, the exact amount, and the name and address of the person or entity you purchased it from. If you're the purchaser filing for a replacement, you may also need a copy of your government-issued ID. For stolen money orders, the situation is harder. USPS doesn't automatically replace stolen items without some level of police documentation, especially if the amount is over $250. It's not a hard rule, but that's how it tends to play out in practice. There is a fee structure you need to understand. Filing a claim costs nothing. Getting a replacement money order costs $0.60 for a new issuance. But here's the catch: if you're filing a claim on behalf of the payee rather than the purchaser, USPS requires additional verification. The payee needs to provide a notarized statement confirming they never received the money order. This is where people get stuck. I've seen it repeatedly. A person receives a money order from a relative overseas, loses the physical paper, and tries to get USPS to reissue it. Without that notarized statement, the claim stalls for weeks. Get the notarization done before you start the claim to avoid that delay.
Get the Full Details

Common pitfalls that slow everything down
One major mistake people make is confusing the USPS tracking number with the money order serial number. They're different. The tracking number on your receipt refers to how the mail item was delivered. The money order serial number is what you enter for tracking the monetary instrument itself. Entering the wrong number into the tracking system gives you nothing useful and wastes time. Make sure you're using the money order number, which is always 18 digits and printed separately on the receipt. Another pitfall is waiting too long to file a claim. The statute of limitations for USPS money order claims is one year from the date of purchase. After that, the claim is essentially dead. I once watched someone try to file a claim eight months after purchasing the money order because they'd been waiting to see if the recipient would somehow produce it. The money order never resurfaced, and the claim was filed right at the edge of the window. It went through, but barely. Don't test the timing. File as soon as you confirm the item is genuinely lost or stolen. There's also the issue of partial losses. If a money order was intercepted and only partially cashed, USPS will typically treat it as a total loss claim. They won't reimburse you for the unused portion separately. You file one claim for the full amount and move forward from there. It sounds counterintuitive, but the system isn't designed to handle fractional recoveries on money orders.
What the tracking system actually tells you
When you look up a money order on the USPS tracking page, you get a status and possibly a location. The status options are basically: not yet cashed, cashed, or claim pending. That's it. If the status shows "cashed," you need to cross-reference the location and date against your own records. If the cashing location doesn't match where you expected the recipient to be, you have a potential fraud situation. Document everything at that point. Take a screenshot of the tracking result. Write down the date and time you checked. These details matter if you end up disputing the cashing with the postal inspector. Some money orders will show a "delivered" status if they were mailed to the purchaser and scanned at the post office. That doesn't mean the money order itself was cashed. It means the physical piece of mail was delivered to the address on file. Confusing these two statuses is another common error that leads to false assumptions about whether a money order has been redeemed.
When to escalate beyond the standard process
If USPS denies your claim or the tracking shows the money order was cashed under suspicious circumstances, you can escalate to the Postal Inspection Service. This is not a fast process. It typically takes several weeks to months, and you should not expect a resolution within a reasonable timeframe for urgent matters. However, for significant amounts, it's worth pursuing. The Inspection Service has more tools for investigating fraud than the standard claims department does. They can request financial institution records, trace cashing patterns, and in some cases coordinate with law enforcement if criminal activity is suspected. The downside is that this path requires patience and documentation. Every email, every claim number, every phone call reference code should be logged. Without a complete paper trail, the Inspection Service won't take your case seriously. I learned this the hard way after calling customer service three times about a disputed cashing and not writing down any reference numbers. When I finally tried to escalate, I had no way to prove I'd already pursued the standard channels. The whole effort collapsed because of missing reference codes. One final note: USPS money orders are guaranteed by the U.S. government. That means even in worst-case scenarios where the claim process goes sideways, there is a backstop. But relying on that backstop takes time and persistence. The system works if you give it enough energy. It does not work if you expect it to be quick or forgiving of mistakes. Plan accordingly.