Accessing Your TIAA Account Is Not As Straightforward As You Might Expect
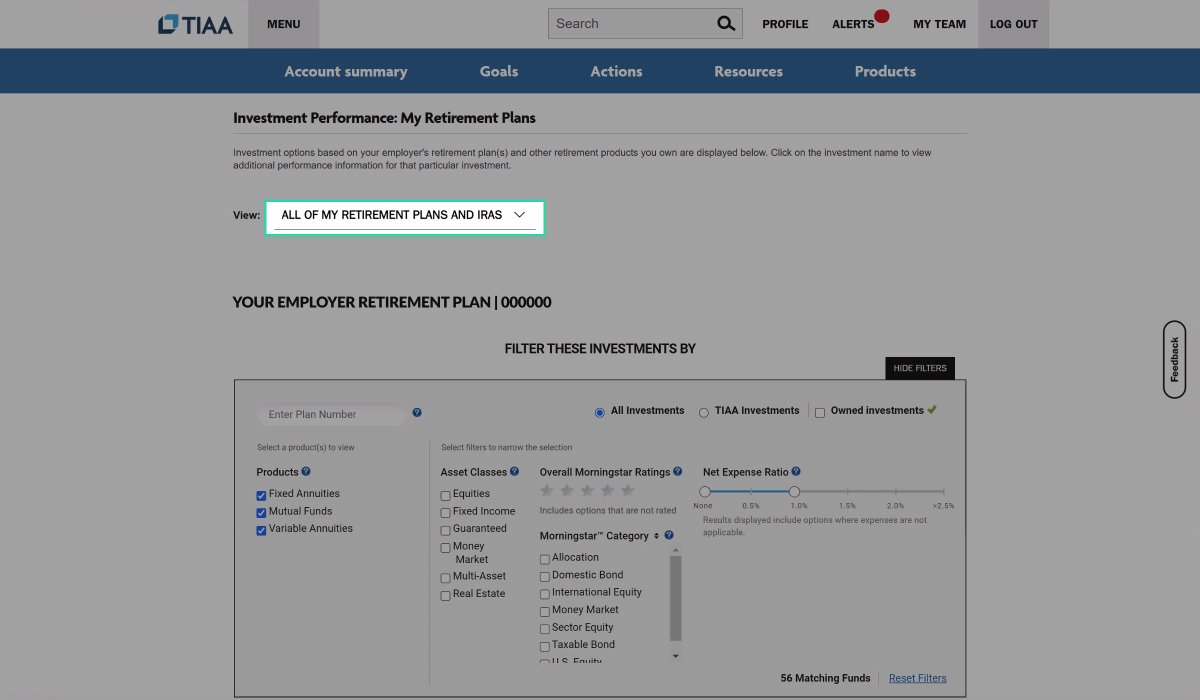
TIAA Create is the portal they direct you toward when you want to actually see what your account is doing. It is not the most polished interface I have worked with, but it does give you access to things you cannot find anywhere else without logging in. The balance you see on a quarterly statement tells you nothing about your distribution choices, your loan repayments, or the tax implications sitting in your RMD calculations. That detail lives in TIAA Create. First, go to the TIAA website and select the option to create or access your online account. You will need the email address tied to your employer or institution. If you are accessing through a university or research institution, you may need your institutional credentials rather than a standard login. This distinction matters more than people expect because it determines whether you end up on the right login page the first time. I spent twenty minutes last year bouncing between the corporate and institutional sign-in pages before realizing I had mixed up which one my old employer used. Stick with the login link your HR department or benefits office sent you. They send those for a reason. Once you are in, the dashboard shows a summary of your holdings across all account types. The real value comes from drilling into each account separately. Your retirement account, your annuity, your salary deferral plan — they are not all aggregated in a way that makes sense for decision-making. Pull up each one individually and look at the expense ratios, the percentage going to each fund, and the current value versus your contributions. Most people stop at the total number and move on. That is where they miss the problems.
Here is something most tutorials do not mention. Your TIAA traditional annuity, if you have one, does not fluctuate with the market the way your CREF accounts do. The rate is set quarterly by TIAA. When interest rates are rising, that annuity can become attractive. When rates drop, it locks you into a below-market return compared to the stock funds. I found this out the hard way during the 2022 rate hike cycle. My annuity was sitting at 2.3% while my CREF Stock fund had dropped significantly, and I was about to make a reallocation that would have locked in bad timing if I had only looked at the numbers together instead of separately. Check the current annuity rate on their site before moving money around in there. It changes every quarter and the timing can matter. The investment change feature is straightforward if you know where it hides. Go to your account, select the specific fund portfolio, and look for the option labeled change investments or similar. There is a daily cutoff time, usually around 4 PM Eastern, after which your request processes the next business day. Weekend requests do not jump the queue. They wait. If you are trying to move a large sum before a market move, plan ahead and do not assume urgency gets you priority. It does not. One thing people consistently trip over is the Beneficiary designation section. You can update this online, but if you have a trust as a beneficiary, TIAA requires additional documentation. I once tried to update a beneficiary form for a client who had a complex trust setup and got stuck in a loop because the system would not accept the trust name without the federal tax ID on file. The fix was calling their support line, having the tax ID ready, and submitting the form again. It took five minutes once I knew what was missing. The online system does not tell you that upfront.
You also have access to your contribution history, employment history if you have moved between institutions under TIAA, and any outstanding loans against your account. If you are retired and taking required minimum distributions, the RMD calculator in TIAA Create uses IRS tables but does not account for state-specific rules. Factor that in yourself. It does not hurt to call and confirm the amount they calculated is correct for your situation before the withdrawal hits. The mobile app exists and it mirrors the web version for most functions. It is less useful for detailed analysis because the screen real estate makes comparing fund performance across years nearly impossible. Use the desktop version for anything that requires actual review. The app is fine for checking balances and making quick changes. That is it. A couple of limitations worth noting. TIAA does not offer real-time intraday pricing on most of their mutual funds. You submit a request and get the next calculated net asset value. If you are trying to time a market event, this is not the platform for it. Also, certain institutional plans have restricted investment options. If your employer negotiated a specific menu, you cannot add funds outside that menu through the portal. Sometimes this limitation is a protection. Sometimes it is just a constraint that slows you down. You deal with it.
Get the Full Details

If you are managing multiple TIAA accounts from different employers over a long career, the consolidation feature can help you see everything in one place after you roll them into a single account. Before that, you log into each one separately and that is exactly as annoying as it sounds. Start consolidating sooner rather than later. The administrative overhead adds up across years. The login itself uses multi-factor authentication now, which is standard but means you should have your phone or backup codes accessible before you start your session. I have lost time before because I had changed phones and had not updated the MFA settings. TIAA support can walk you through it, but it is easier to have it ready. There is no chat feature for account questions. You call or you email. The phone support wait times vary by season. Call mid-week mid-morning if you need to talk to someone. Avoid the end of the quarter when everyone is simultaneously dealing with rebalancing and RMD questions. The hold times stretch significantly during those windows.
Read through your account statements even if you think you know what is in there. TIAA has been known to adjust fee structures and fund lineups, and those changes sometimes appear in footnotes rather than front-and-center notifications. A few people I work with missed a fund merger that moved their money into a higher-expense share class without reading the notice. It happened on their watch for eighteen months before anyone caught it. The statements are not exciting but they are the primary source of truth for what is actually happening in your account.