The Reality Of Card Payments In Turkey
I spent three weeks in Istanbul last year and learned more about Turkish payment infrastructure than I ever wanted to know. Most travelers assume their card works everywhere because it works everywhere at home. That assumption costs people money and creates stress at checkout counters. Credit cards work fine in Turkey, but the system behaves differently than what you are used to. The core difference is not that cards are rejected everywhere. It is that terminal behavior, currency conversion logic, and merchant preferences combine to produce surprises if you do not understand the plumbing underneath.
Using Credit Cards In Turkey What You Need To Know
Let me explain the process first because that is where most mistakes happen. When you tap or insert your card at a Turkish point-of-sale terminal, the machine asks whether you want to pay in Turkish lira or your card currency. This is called dynamic currency conversion, and selecting your home currency is almost always the wrong choice unless you are being reimbursed immediately and do not care about the spread. Turkish terminals run on networks similar to the rest of Europe, but the local acquiring banks apply their own markup rules. If you choose foreign currency at the terminal, the merchant's acquirer sets an exchange rate that includes a hidden surcharge. I have seen that surcharge run between three and five percent on a single lunch bill. Paying in lira routes the conversion through your card issuer, which typically offers a rate much closer to the interbank midpoint. The practical workaround is simple. Always decline DCC. If the terminal insists, ask the cashier to switch the transaction to lira settlement. They can usually do it without calling anyone, though it takes ten to fifteen seconds longer and sometimes requires a manager override at smaller merchants.
Network And Terminal Realities
Visa and Mastercard are accepted at the vast majority of card-enabled merchants in urban areas. American Express works, but coverage drops sharply outside major cities and tourist districts. Discover has its own network agreement through Alliance Data in Turkey, which means it processes fine in hotels and larger retailers, but you will hit dead ends at independent restaurants and transit kiosks. Contactless payments are widely available in Istanbul, Ankara, and Izmir. However, the contactless limit is lower than in some European countries. I have watched terminals reject a two-lira coffee because the contactless threshold was tripped by a system glitch. When that happens, you insert the chip and enter your PIN or sign, depending on the terminal setup. Turkish terminals almost never request a signature anymore. The PIN pad exists, but many locals pay without a PIN for small amounts because the merchant has set zero-PIN thresholds to speed up queue movement. You should carry a chip-enabled card. Magnetic stripe cards are technically still accepted at some older terminals, but many merchants have stopped supporting them due to fraud pressure. A friend of mine had his magnetic-stripe card declined at a gas station in Bursa last spring. The terminal simply showed an error code that translated to something like unsupported card type. He ended up paying cash for fuel and had to figure out a mobile banking transfer to reimburse himself later.
Get the Full Details
The ATM Situation You Should Not Ignore
ATMs in Turkey charge fees, and not all of them are created equal. State-owned banks like Ziraat and Halkbank tend to have lower fees than private banks. The fee range sits somewhere between eighty and two hundred fifty lira per withdrawal, depending on the machine and your card issuer's policy. Your home bank may also add its own foreign transaction fee. Here is a detail most guides omit. Some ATMs in tourist zones display ads in English and seem welcoming, but they route through less favorable clearing paths. I found this out the hard way when I withdrew cash from a machine outside a hotel in Kadikoy. The transaction posted with an unexpected fee that did not match the standard rates I had seen at Ziraat machines nearby. After checking the receipt, the ATM operator was clearly a private bank sub-leased terminal. It happened twice in one trip, and both times I lost roughly forty dollars to extra fees I could have avoided by walking four blocks to a branch-owned ATM. The workaround is to use ATMs attached directly to bank branches, preferably during business hours. If something goes wrong, you can speak to a teller instead of emailing support and waiting three days for a reversal.
Online Purchases And Identity Verification
Turkish e-commerce uses a system called 3D Secure, which sends a one-time code via SMS or a banking app to verify purchases. This is standard practice now, but it creates a friction point for foreign cards. Some Turkish websites only support 3D Secure verification through Turkish-issued cards. If your card issuer does not participate in the local 3D Secure gateway, the payment fails even though your card is perfectly valid. I encountered this when trying to buy a flight insurance add-on from a Turkish airline. The checkout page accepted my Visa card initially, then rejected it during the 3D Secure step. I called my card issuer, confirmed international e-commerce was enabled, and tried again. It failed a second time. The third attempt worked after I specifically asked my bank to whitelist the Turkish payment gateway identifier, which is something they can do if you provide the three-digit code from the error message. That whole process took about forty minutes and required patience I did not have at the time. Another common issue is address verification. Turkish checkout forms sometimes do not accommodate foreign addresses properly, especially if the form expects a Turkish postal code format. You can usually work around this by entering your home postal code in the zip field and leaving the province field blank or entering a placeholder like 00000. Most payment processors accept it, but a few poorly configured sites will hard-reject the transaction.
Cash Is Still King Outside The Tourist Core
Even though card acceptance has grown rapidly, cash remains dominant in many everyday transactions. Small neighborhoods, rural towns, street markets, ferries, and budget accommodations frequently operate on a cash-only basis. I have seen card terminals sitting on counters in Izmir that nobody ever used because the shop owner preferred cash to avoid the merchant discount fee. Carrying a mix of cards and cash is the only sane approach. Withdraw enough lira to cover daily expenses, keep a backup card in a separate location, and store emergency cash separately from your wallet. This is basic travel advice, but it matters more in Turkey than in many European countries because card infrastructure gaps appear in unexpected places.
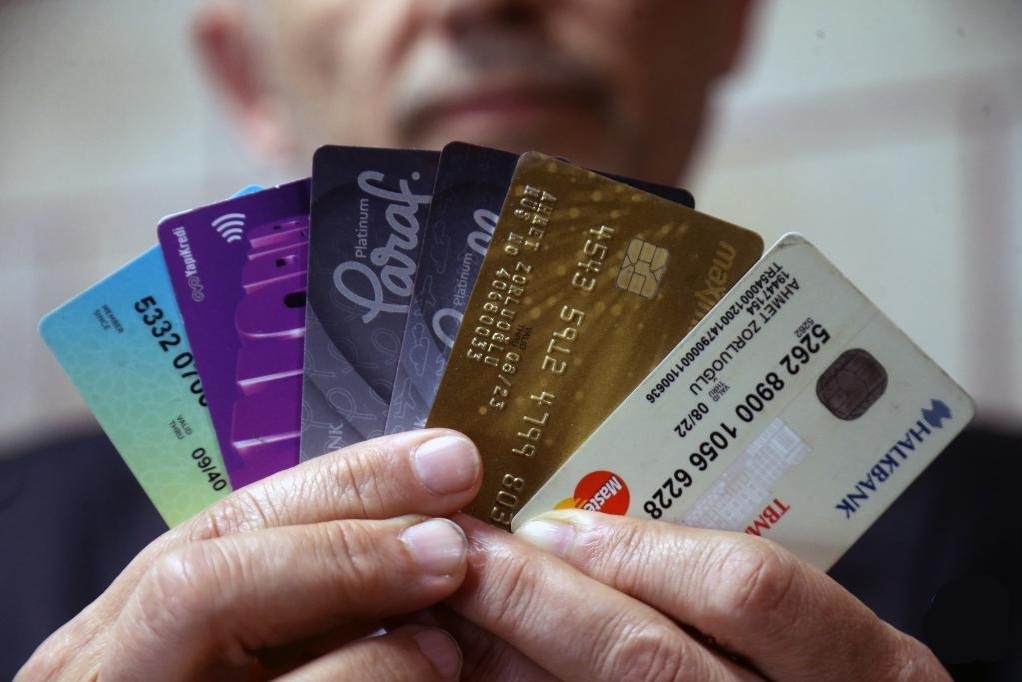
Fees, Foreign Transaction Charges, And Currency Selection
Most major card issuers charge a foreign transaction fee of one to three percent. If your card does not charge one, use it. If your card does, calculate whether the benefit of rewards points outweighs the fee. For short trips, the fee is usually manageable. For longer stays, it adds up quickly. Some travel cards offer zero foreign transaction fees and better exchange rates. I switched to a no-foreign-transaction-fee card for a six-week trip and saved approximately sixty dollars in fees alone. That is a concrete number, not a vague estimate. The difference mattered more than the reward points from my previous card. Again, always choose to pay in Turkish lira. Never let the terminal convert the amount for you. The exchange rate they offer is worse than what your bank provides, and the markup is not trivial. On a fifty-lira bill, the difference might look small. On a thousand-lira restaurant bill, it becomes a noticeable chunk of money.
Edge Cases And What To Do When Things Break
Card declines happen. They happen for reasons that have nothing to do with your balance. Turkish fraud detection systems flag unfamiliar transaction patterns aggressively. If you travel from Istanbul to Cappadocia and then immediately make a purchase in Antalya, the system may block the card. I experienced this firsthand when a dinner bill in Ankara was declined twice before I realized the fraud team had locked the card. I called my bank, verified my location and recent transactions, and the card was unblocked within twenty minutes. The merchant was patient, but the next restaurant in line was not. Another edge case involves prepaid travel cards. Some prepaid cards do not work reliably in Turkey because the Turkish payment gateway does not recognize the issuer type. I tested two different prepaid cards during a trip, and neither processed at a mid-range hotel. The hotel had no problem accepting a standard Visa credit card from the same bank. The issue was specifically with how the prepaid product was categorized in the acquiring system. If you rely on prepaid cards, test them at a low-value merchant first. A coffee shop or metro ticket is enough to confirm functionality before you commit to a larger purchase.
Practical Setup Checklist
Before you travel, enable international use on all cards you plan to bring. Notify your bank of your travel dates if your issuer requires it. Carry at least two cards from different networks. Have a backup payment method that is completely separate from your primary wallet. Know your bank's international customer service number and keep it accessible offline. Download your bank's mobile app and confirm it works abroad, since you will likely need it for one-time passwords or fraud verification. Pick up some lira before you arrive or withdraw from an ATM at the airport upon landing. Airport ATMs are convenient but expensive. If you have a choice, wait until you reach a city-center branch and withdraw from there. Use cards for larger purchases where you want a paper trail. Use cash for small daily transactions where merchants prefer it and where cards may cause unnecessary delays. Do not feel guilty about preferring cash at small shops. The merchant fee structure makes it a rational choice for them, and your cooperation reduces friction for everyone.