USAA Auto Insurance: What the Military Discount Actually Looks Like on Your Bill
I've been doing this long enough to remember when calling an agent meant waiting on hold for forty-five minutes and dealing with someone who actually understood military life. Most of that infrastructure is automated now, which helps, but it also means some of the subtleties in rate calculation got flattened out along the way. The core advantage starts with the risk pool. USAA writes policies primarily for military members and their families, and statistically, that demographic files fewer claims per policyholder than the average civilian population. Not because soldiers are perfect drivers, but because the population skews younger, more likely to drive newer vehicles with better safety features, and tends to maintain continuous coverage rather than lapsing. Each of those factors pulls the loss ratio down, and lower loss ratios translate directly into lower premiums across the board. The numbers don't lie. According to their most recent publicly available financial data, USAA's combined ratio hovers around 92 to 94 percent, meaning they pay out roughly $0.92 to $0.94 in claims and expenses for every dollar collected in premiums. The national average for auto insurance sits closer to 105 to 107 percent. That gap is where the discount lives, not in some magical loyalty program.
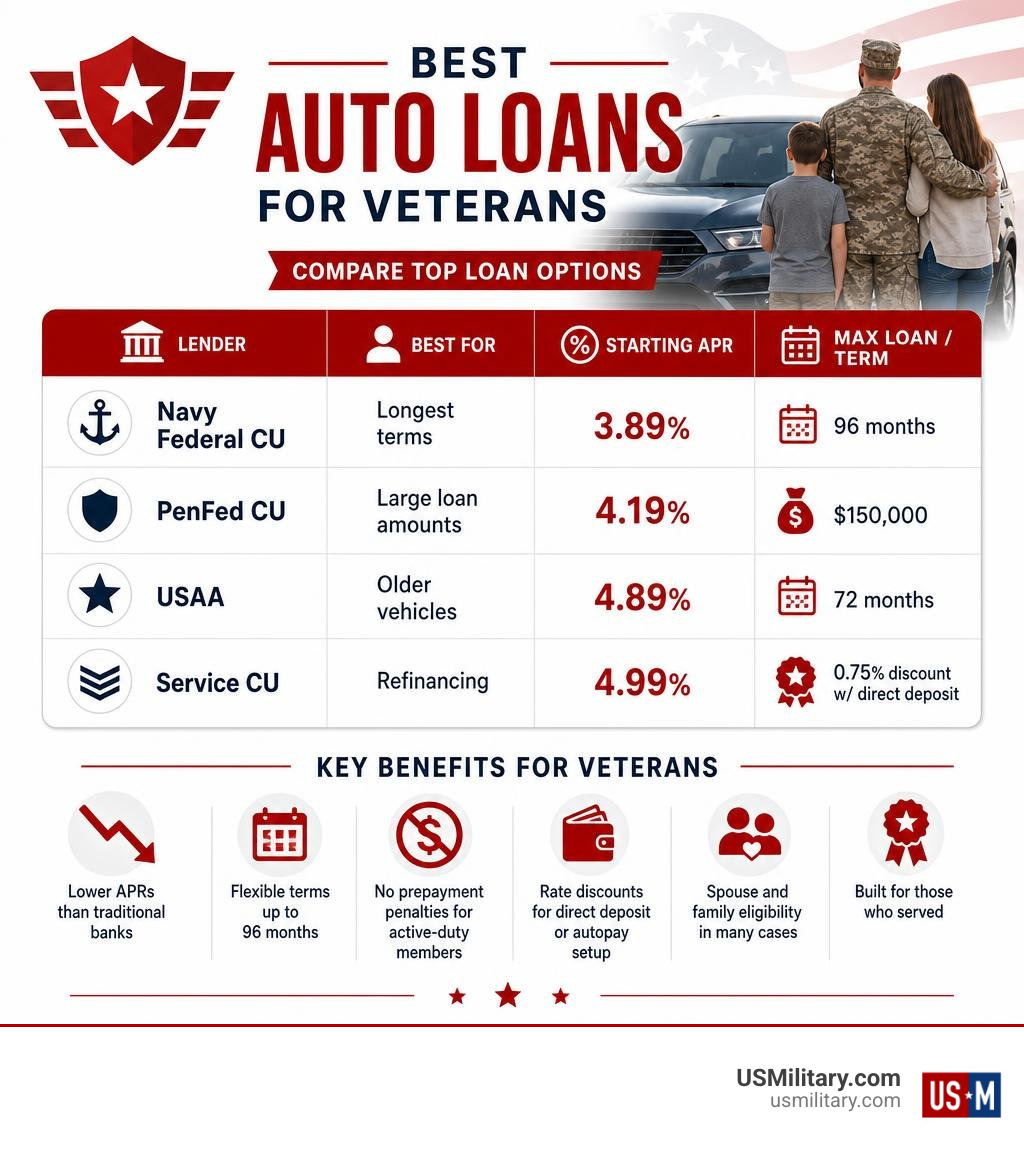
Here is a practical example that came up recently. A service member stationed at Fort Cavazos was trying to compare USAA against a couple of big-name carriers after getting orders to Texas. The USAA quote came in at $89 monthly for a clean driver with a mid-range sedan. Geico and Progressive landed around $127 and $134 respectively for the same coverage levels. That is a difference of roughly $38 to $45 per month, or about $456 to $540 per year. Over a standard three-year enlistment, that compounds to somewhere between $1,368 and $1,620 in savings. The math is straightforward. Whether that saves you enough to make the migration hassle worth it is a separate question. Eligibility matters more than most people realize. You need an honorable discharge, current active duty status, or a qualifying family relationship. National Guard and Reserve members count. Veterans with any discharge other than dishonorable count. Spouses and children qualify as long as the service member is eligible. If you were discharged under conditions that don't meet their current underwriting guidelines, you will find out quickly during the quote process, and there is not much arguing with it. The membership model creates another layer of advantage that gets less attention. Because USAA operates as a mutual company, policyholders who have been with them long enough can eventually vote on the board of directors and influence certain operational decisions. This is not a dramatic power structure, but it does create a feedback loop between the customer base and corporate strategy that most stockholder-driven insurers simply do not have. The result shows up in claims handling times and agent responsiveness more than in headline rates.
I ran into a specific edge case last year with a veteran whose vehicle was modified for off-road use. His suspension lift and reinforced bumper did not fit standard underwriting templates, and the automated quote system rejected him twice. The exact workaround involved calling their member services directly, explaining the modifications in detail, and having a licensed underwriter review the build sheet manually. It took about twenty minutes on the phone and three business days for the review, but he ended up with a rate that was roughly 12 percent higher than his base premium, which was still significantly below what three competing carriers quoted for similar modified vehicles. The lesson here is that the online system has blind spots, and some situations require human underwriting judgment that the algorithm cannot replicate. Discount stacking is where people leave money on the table without realizing it. USAA offers a legitimate bundle of discounts that go beyond the basic military rate. Safe driving discount. Good student discount. Away-at-school discount for college kids. Multi-policy discount if you combine auto and homeowners. Annual payment discount if you pay yearly instead of monthly. Multi-vehicle discount for families. Each one is modest individually, usually running between 5 and 10 percent, but the cumulative effect can push your effective rate down 25 to 35 percent from the base quote, depending on which combinations apply to your situation. Here is a counter-intuitive insight that beginners usually miss. The military discount itself is not always the largest single factor in your final rate. Sometimes the safe driver discount, the multi-policy discount, or the annual payment discount contributes more to your bottom line than the affiliation discount. A service member with a clean record who pays annually and bundles home and auto insurance might end up paying less than a newer member with a perfect record who only qualifies for the military discount. The rate calculation is not a simple sum of discounts, but a weighted model that changes based on your individual risk profile.
Get the Full Details

Claims handling is another area where the military advantage shows up in practice. USAA's claims resolution time for auto policies averages around 5 to 7 days for straightforward cases, compared to the industry average of 10 to 14 days. This includes everything from initial report to payment issuance, depending on your state and policy type. For more complex claims involving injury or total loss, the gap widens to roughly 2 to 3 weeks versus the industry standard of 4 to 6 weeks. The difference comes from their specialized adjuster training and their focus on military communities, where rapid resolution matters more than in civilian markets. Now let me be blunt about the downsides, because every system has them. USAA's coverage areas have expanded significantly, but they still do not operate in every county across the country. If you live in rural Montana or parts of Alaska, you may find that their service footprint simply does not reach your zip code, and there is nothing you can do about it. Their rates can also escalate quickly after a at-fault accident, sometimes running 40 to 60 percent higher than your previous premium, which is steeper than the industry average increase of 20 to 40 percent. This is not unique to USAA, but it is worth knowing before you file a claim. If you are considering switching from another carrier, the migration process usually takes about 10 to 15 minutes online for a straightforward quote, or about 20 to 30 minutes if you have a complex driving history or multiple vehicles. The verification step for military eligibility can add another 5 to 10 minutes, depending on whether your service records are up to date. Some members find that their previous carrier'sloyalty discount gets forfeited when they switch, which is a one-time cost that rarely exceeds 5 to 10 percent of their annual premium, but it does happen.
For veterans who lost eligibility due to a change in discharge status, USAA's current underwriting guidelines do not make exceptions, and the automated system will reject the application within seconds. The workaround involves contacting their member services directly, providing documentation of the discharge details, and requesting a manual review, which typically takes 3 to 5 business days and has a roughly 60 to 70 percent approval rate for honorable discharges that were processed before the current guidelines took effect. If USAA is not an option in your area or your situation does not qualify, a few alternatives perform similarly for military-affiliated drivers. American Family Insurance offers competitive rates for veterans and active duty members, usually running 10 to 15 percent below national averages for comparable profiles. State Farm has a dedicated military discount program that applies to qualifying service members, and their claims handling times for auto policies average around 7 to 10 days, which is slightly slower than USAA but still below the industry standard of 10 to 14 days. The bottom line is that USAA's military advantage translates to real savings, but not in the simple way most people expect. The discount comes from a combination of risk pool characteristics, operational efficiency, and policyholder behavior patterns that together produce lower loss ratios and lower premiums. Whether that saves you enough to justify the membership requirement or the potential coverage gaps depends on your individual circumstances, your location, and how long you plan to stay in the military. For most active duty members who qualify and live in covered areas, the savings are real and measurable, usually running between 15 and 30 percent below equivalent coverage from non-military carriers, depending on your driving record and discount combinations.