Smart Spending Isn't About Deprivation
Most people approach budgeting backwards. They cut categories until life becomes miserable, then quit after three weeks because they resented the whole exercise. I learned this the hard way in 2019 when I tried the zero-based budgeting method religiously. Every dollar got assigned. Then my car transmission died. Two thousand dollars vanished from a category called "entertainment" that was already at zero. That was the moment I stopped treating budgeting like a morality test and started treating it like logistics. The difference matters more than you'd think. When you understand where your money actually goes instead of pretending it won't, you make decisions from information instead of guilt. Smart shopping on a budget in the United States requires the same approach. You need data first, strategy second.
USA On A Budget Master Smart Shopping With The Ultimate Guide To Smart Spending
Here is how the process actually works in practice, not the sanitized version you see on lifestyle blogs. Step one is tracking. Not estimating. Tracking. I used to estimate my grocery spend at $400 a month and be genuinely surprised when I hit $620. The gap between perception and reality is where money disappears. Download a free app like EveryDollar or just use a spreadsheet. Write down every single purchase for thirty days. Coffee, parking, the subscription you forgot you still had. By day twenty you will identify at least two leak categories you did not know existed. Step two is the category shift. Most budget templates lump everything into food, transportation, and miscellaneous. That is too blunt. Break food into groceries and dining out. Break miscellaneous into subcategories until you can name each one. This is where I hit my first real snag. I discovered that "household supplies" was consuming forty dollars a month without me noticing. Paper towels, cleaning products, light bulbs. I had no system for replenishing these items so I bought them reactively at full price from the nearest store. My workaround was simple. I created a standing monthly calendar reminder on the first of each month. I walked to the supply closet, counted what I had, and wrote a list before leaving the house. That single habit cut my household supply spend from $40 a month to roughly $18. The difference was not buying less. It was buying at the right time from the right place.
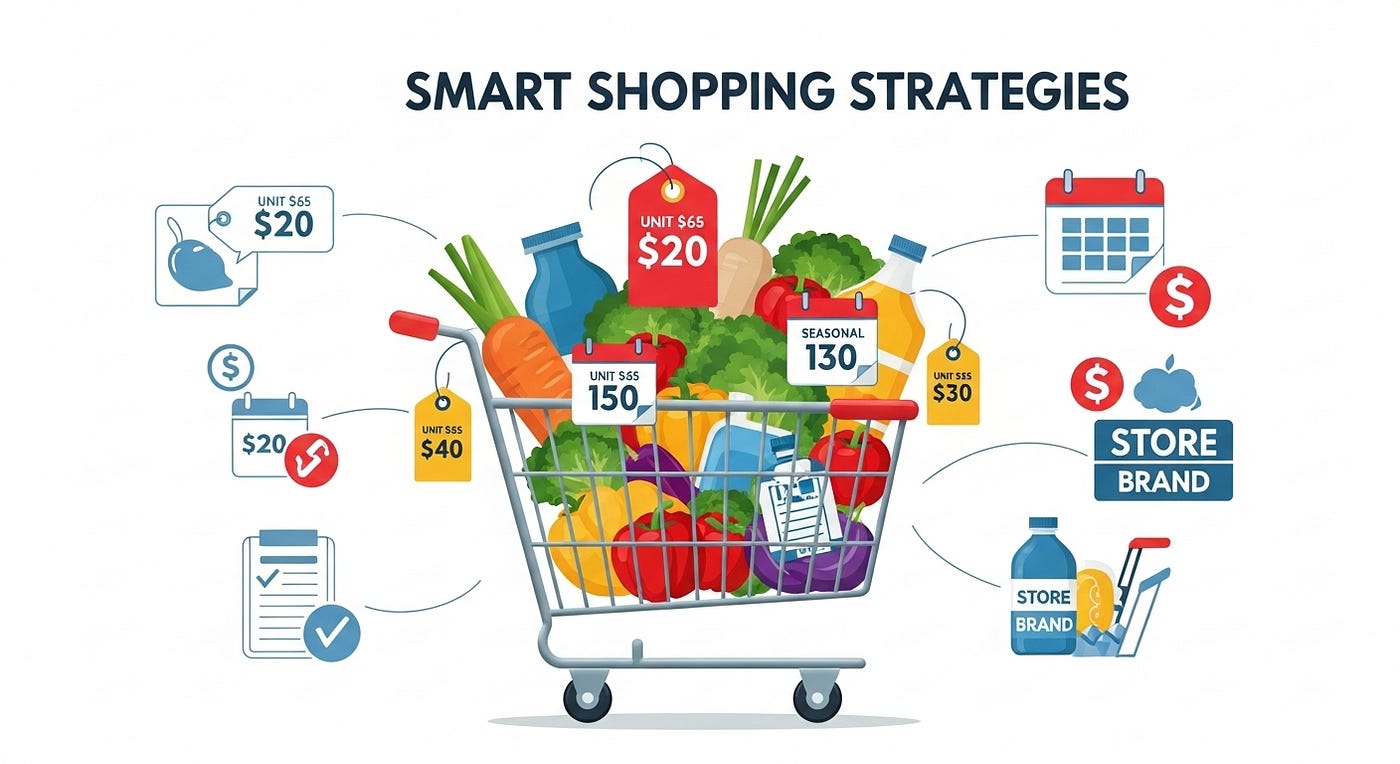
Step three involves understanding unit pricing, which most shoppers ignore. A twelve-pack of paper towels costs less per sheet than a six-pack, but the absolute dollar amount is higher. If your budget cannot absorb the larger upfront cost, you are not saving money by buying bulk. You are creating cash flow problems. This is counter-intuitive for a lot of people who equate bulk with smart. It is only smart when it fits your actual consumption rate and your available capital at point of purchase. Step four is the thirty-day rule for non-essential purchases over fifty dollars. Put it in the cart. Walk away. Wait thirty days. If you still want it and the money is available, buy it. Eighty percent of the time you forget about the item entirely. I tested this on a $280 pair of noise-canceling headphones last spring. I added them to my cart on April third. By May third I had not thought about them once. The money stayed in my account. The temptation was real for about four days and then it faded. That is the mechanism at work. Desire has a half-life. Budgeting works with that half-life instead of fighting it. There are real limitations to this approach that nobody mentions. It does not help when your income is unpredictable. If you work commission sales or gig economy shifts, the monthly budget framework fractures because your baseline changes too much. In that scenario you need a floor-budget instead. Calculate your absolute minimum survival expenses. Rent, utilities, basic groceries, insurance. Whatever comes in above that goes into a buffer account until it reaches three months of expenses. Then you invest the surplus. Floor-budgeting is less precise but far more survivable when income varies.
Get the Full Details
Another limitation is geographic variance. The strategies here assume access to warehouse clubs, big-box retailers, and online price-comparison tools. If you live in a food desert or a town with one grocery store, your options are structurally different. I have friends in rural Montana who cannot do what I do in suburbia. They need different solutions, mainly cooperative buying groups and seasonal stockpiling during local harvest sales. Know your environment before you apply a strategy designed for a different one. The core insight most people miss is that smart spending is not about finding coupons. It is about reducing decision fatigue. Every time you stand in an aisle wondering whether to buy something, you are burning mental energy that could be saved by having a pre-decided framework. Write your rules down. What gets bought at Target versus Amazon versus Costco. What day you do grocery shopping. What constitutes an emergency purchase versus an impulse purchase. When the rules are explicit, you spend less time deciding and more time living. I spent five years optimizing my spending habits. The biggest improvement came not from a clever trick but from accepting that some waste is unavoidable. You will overpay for convenience sometimes. You will buy something you do not need. The goal is not perfection. The goal is awareness and course correction. Track, adjust, repeat. That is the entire system. Everything else is noise.