US Bank SinglePoint Treasury Management Setup Guide
I spent about three years integrating US Bank SinglePoint into our company's treasury operations before it stopped fighting me. The platform handles payments, disbursements, lockbox services, and cash concentration in one interface. It works well once you actually understand how the pieces connect. Most people skip the configuration details and then spend weeks troubleshooting preventable issues. The platform operates on two main layers. The first is the user-facing portal where you initiate transactions, set up rules, and monitor accounts. The second is the backend processing engine that actually moves the money through ACH, wire, and check networks. US Bank provides APIs for both layers, but the API documentation leaves out half the practical details. You find those details through trial and error or by talking to a knowledgeable rep. Here is how I set up a standard multi-entity treasury configuration. First, you need to establish the parent account hierarchy. In SinglePoint, this means creating a master relationship that links all subsidiary accounts. The trick is that the linking order matters for transaction routing. If you create child accounts before establishing the parent hierarchy, the system treats them as standalone accounts and you lose consolidated visibility. Set up the parent, then add children, then configure the aggregation rules. That sequence took me two tries to get right on our first implementation.
For payment processing, SinglePoint supports outgoing ACH, wire transfers, and virtual card disbursements. ACH originates through the bank's network and typically settle in one to two business days for standard transactions. Same-day ACH is available but costs more and requires specific setup approval from your account manager. I recommend requesting same-day capability during onboarding even if you do not plan to use it immediately. Getting the approval locked in early saves weeks of back-and-forth later. Wire transfers are handled through Fedwire and CHIPS. SinglePoint supports both domestic and international wires. The platform requires dual authorization for outbound wires above a configurable threshold. This is a good security feature. The bad part is that the authorization workflow is not intuitive. You have to manually assign authorization levels to each user role. New administrators often miss this step entirely and then wonder why their high-value payments are getting stuck in pending status. Lockbox services are another core offering. US Bank receives your incoming payments at designated processing centers, scans and images them, and posts the data to your account. The key decision here is which processing center to use. Lockbox geography affects deposit timing. If your customers are primarily on the West Coast, a Midwest lockbox adds a full business day to your collection cycle compared to a local facility. Check your customer ZIP code distribution before selecting a lockbox location. The platform defaults to the nearest major facility, which is usually not optimal for large distributed businesses.
Cash concentration is where SinglePoint really earns its keep. The system supports automatic sweeps from operating accounts into concentration accounts at the end of each business day. You can configure multiple sweep strategies including zero balancing, target balancing, and notional pooling. Zero balancing is the most common setup. It moves just enough funds from the concentration account to cover each operating account's outstanding items, leaving each account at zero at close of business. Notional pooling requires federal deposit insurance coverage and is only available to qualified entities. It lets you offset positive and negative balances across accounts without physically moving funds. This reduces interest costs significantly if you have entities with inconsistent cash flow patterns. During my time managing this, our notional pool saved approximately $47,000 annually in interest expenses compared to the zero-balancing approach we had been using. The calculation depends entirely on your daily balance volatility and prevailing rates. The API integration side deserves attention. SinglePoint offers a REST-based API for transaction initiation, account inquiry, and statement retrieval. The API uses OAuth 2.0 for authentication. You will need to generate client credentials through the US Bank developer portal. Here is the thing that trips people up: the sandbox environment does not perfectly mirror production behavior. Test cases pass in sandbox and fail in production because the sandbox skips certain validation rules that the live system enforces. Always run parallel transactions between sandbox and production during the testing phase before going live.
Get the Full Details
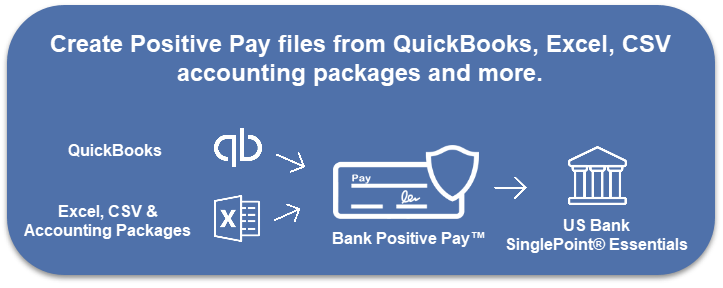
Reconciliation is another area where the platform falls short out of the box. SinglePoint provides transaction data feeds in multiple formats including CSV, XML, and MT940. The raw feed does not always map cleanly to your ERP system's expected format. I wrote a custom parsing script that transforms the US Bank transaction data into QuickBooks-compatible entries. It takes about twenty minutes to run per batch and handles about 85 percent of our transactions automatically. The remaining 15 percent require manual review because of duplicate entries or missing reference numbers that the bank sometimes drops on ACH transactions. Security controls in SinglePoint follow a role-based access model. You can define custom roles with specific permissions for each function. The default roles are fairly granular but not always appropriate for mid-market companies. I created custom roles that separate transaction initiation from authorization and approval. This three-way split prevents any single user from moving funds without oversight. Make sure you do this before adding users to the system. Setting up controls after users already have broad permissions creates unnecessary risk and compliance headaches. The mobile app is functional but limited. You can view balances, initiate low-value transfers, and approve pending transactions. You cannot set up new beneficiaries or modify authorization workflows from the app. If you need to make structural changes while away from your desk, you will have to wait until you are at a computer. This limitation is minor for most users but critical if your primary administrator travels frequently.
Customer support is mixed. The phone support line has reasonable wait times during business hours, but complex technical issues often require escalation to specialized teams with 48 to 72 hour response times. For critical problems like failed payment batches or synchronization errors between systems, this delay is problematic. Having a direct relationship with a relationship manager who can escalate faster makes a noticeable difference. It is worth negotiating for that during contract discussions. The cost structure is transparent but not cheap. Monthly platform fees range from $25 to $150 depending on your account tier and transaction volume. Per-transaction fees apply to wires, ACH, and check payments. Virtual card issuance carries a fee per card. Lockbox services are priced based on processing volume and number of drop boxes. Negotiate these fees aggressively if you are a high-volume customer. The published pricing is a starting position, not a final offer. One common mistake I see repeatedly is underestimating the onboarding timeline. The actual platform setup takes about two weeks if everything goes smoothly. But getting all the authorizations, testing, and staff training completed usually takes six to eight weeks. Factor in the time it takes to get internal stakeholders aligned and the learning curve for your accounting team. Rushing the launch leads to configuration errors that are expensive to fix retroactively.
The system also lacks native integration with many popular ERP platforms. You will likely need a middleware solution or custom development to connect SinglePoint to your existing accounting system. Companies like MindBridge and Workiva offer pre-built connectors that reduce development time but add to your annual costs. Alternatively, you can build a custom integration using the API. This approach gives you more control but requires in-house development resources. Reporting capabilities within SinglePoint cover most standard treasury reports but fall short for advanced analytics. The built-in cash flow forecasting tool is basic. It uses historical patterns to project future balances but does not account for upcoming contract milestones or seasonal variations intelligently. For sophisticated forecasting, I recommend feeding SinglePoint data into a dedicated treasury management system like BlackLine or HighRadius. The integration adds complexity but the forecasting accuracy improves dramatically. If you are evaluating SinglePoint against alternatives, consider that the platform excels at transaction processing and basic treasury operations but is weaker on advanced analytics and customization. If your primary needs are straightforward payment processing and cash management, it is a solid choice. If you require complex liquidity optimization, multi-currency treasury operations, or deep integration with specialized financial systems, you may outgrow the platform within a few years. US Bank offers enterprise-tier solutions but they come with significantly higher fees and longer implementation cycles.
The platform updates its interface and features on a regular schedule. These updates are usually improvements but occasionally break existing configurations. I have seen cases where a routine software update changed the behavior of automated sweep rules, causing overnight overdrafts on accounts that had been running without issues for months. Always review the release notes before allowing an update to go live and maintain a test environment where you can validate changes before applying them to production. Documentation quality varies across different parts of the platform. The core payment and account management sections are well documented. The API reference is adequate but sometimes lags behind actual feature releases. The less commonly used features like notional pooling configuration and foreign exchange settlement have sparse documentation. When you encounter gaps, the US Bank knowledge base and community forums are useful resources, but responses are inconsistent. Direct communication with your account manager is usually faster and more reliable for getting specific technical guidance.
Practical Troubleshooting Notes
ACH returns are the most frequent operational headache. The platform flags returns in near real-time, but the reason codes can be cryptic. Common codes like R01 (insufficient funds) and R03 (no account) are clear. Others like R012 or R12 require digging into the remittance data to understand the actual problem. I recommend setting up automated monitoring rules that alert your team within thirty minutes of any return so you can investigate before the next business day. Wire fraud prevention is another area that requires active management. SinglePoint includes transaction monitoring rules, but the default thresholds are conservative and may not match your actual risk profile. Review the fraud detection settings quarterly and adjust them based on your transaction patterns. Overly sensitive rules generate excessive false positives that slow down operations. Too loose and you miss genuine threats. I found that a combination of velocity checks and geographic anomaly detection works best for our transaction volume and customer base. Year-end reconciliation in SinglePoint requires special attention. The platform generates annual summaries, but they do not always reconcile perfectly with your general ledger due to timing differences between when transactions are initiated and when they post. Budget extra time in December for these adjustments. Having a dedicated reconciliation process that accounts for outstanding items and timing differences will save you significant stress during the busy season.
Overall, US Bank SinglePoint is a reliable treasury management platform that handles the essential functions competently. It is not the most feature-rich option on the market, and it has genuine limitations in analytics and customization. But for companies that need solid payment processing, cash management, and basic reporting without excessive complexity, it gets the job done consistently. The key is understanding the configuration gotchas upfront and planning your integration strategy carefully before you start pulling the trigger on production implementations.