Us Bank CDs Right Now: What Actually Works
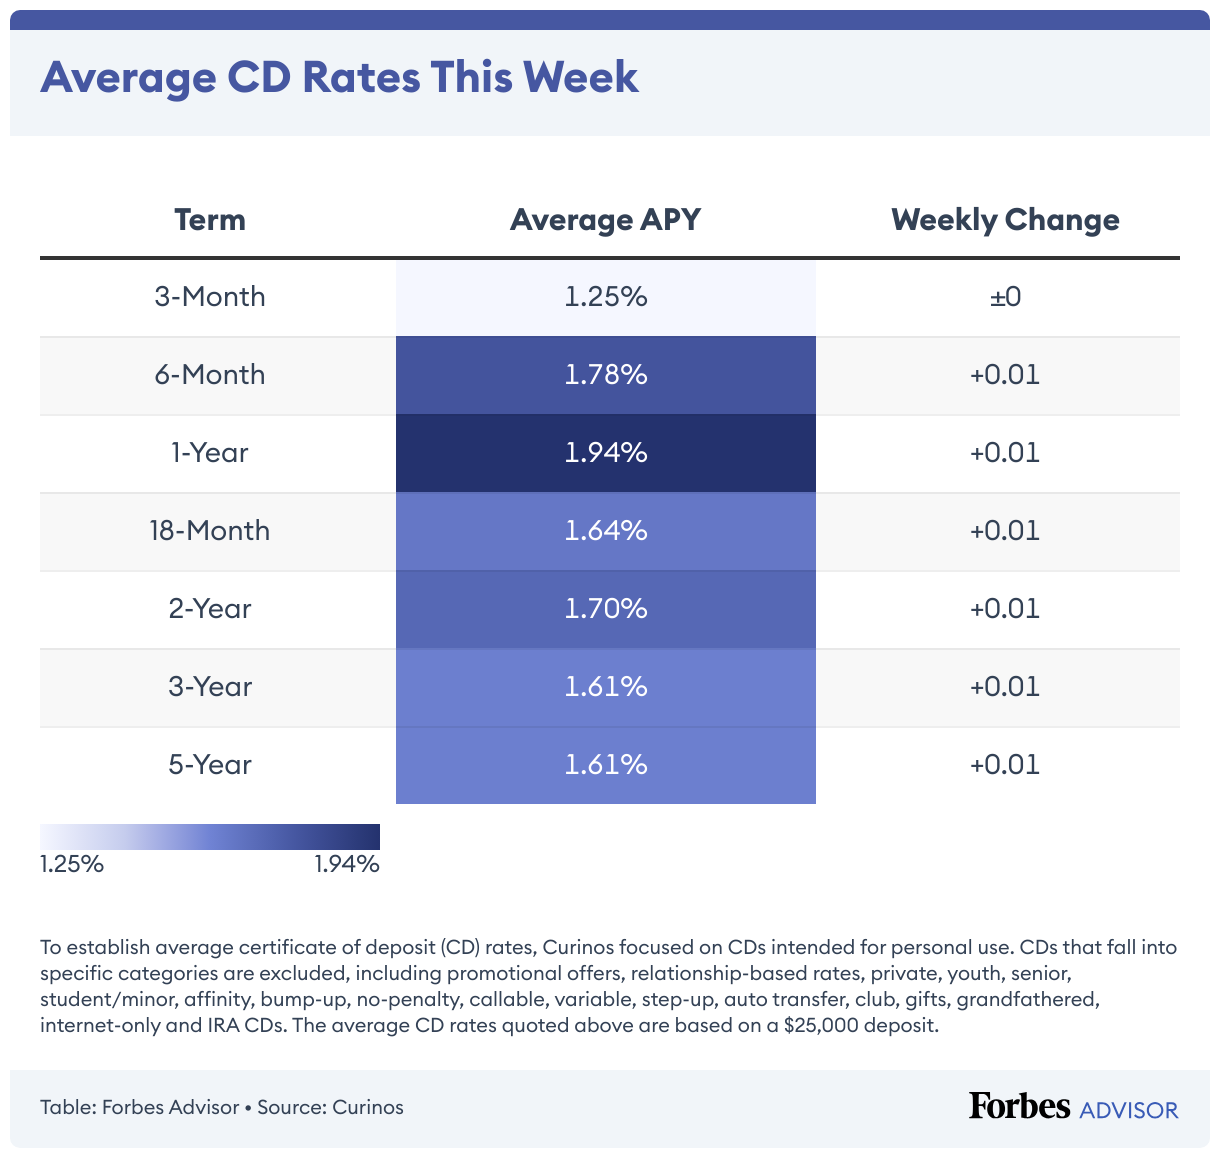
I opened a Us Bank CD last spring for $50,000 at 4.85% APY with a 12-month term. The rate was not terrible but it was nowhere near the 5.30% or 5.50% range that online institutions like Ally and Marcus were offering at the same time. I kept half my money there because I wanted the convenience of being able to walk into a branch and talk to someone if something went wrong. The rest went to online banks. This split turned out to be the right call. As of mid-2026, Us Bank's standard CD offerings generally sit in the 4.25% to 5.10% APY range depending on term length. The longer you lock up, the slightly higher the rate tends to be, but the difference between a 6-month and a 5-year CD is usually only about 25 to 40 basis points at Us Bank. Compare that to the 75 to 150 basis point spreads you see at direct online banks and the gap becomes a real problem over time. I calculated this once with $100,000. At 5.00% versus 5.40% over 12 months, the online bank earns $400 more. Over three years of rollovers, that compounds to roughly $1,200 in additional interest. Not a huge amount but it adds up if you have meaningful deposits. Us Bank does occasionally run promotional CD rates that jump above their standard offerings. These promos typically require setting up a new savings account first and sometimes opening the CD through their mobile app rather than a branch. The promo rate usually expires after 90 days so if you see one listed, act on it the same week. I have seen people miss these windows because they were waiting to visit a branch in person. The best approach is to check the rates online on a weekday morning and open the account digitally before calling your relationship manager to ask about any unadvertised promotional codes they might apply to larger balances.
How Us Bank CD Rates Actually Work
A CD at Us Bank works like most bank CDs in the United States. You deposit a minimum amount, typically $1,000 for standard CDs and $500,000 for their Preferred Rate tier, and the bank guarantees a fixed interest rate for a set term. Terms range from 30 days to 60 months. Interest compounds daily and pays out monthly, quarterly, or at maturity depending on what you select. The key detail that trips people up is the difference between APY and the nominal annual percentage rate, or APR. Us Bank quotes APY, which already includes the effect of compounding. If a rate table shows 5.00% APY, your actual return after one year on $10,000 is $509.45. If you only look at the nominal rate and assume simple interest, you will underestimate your earnings by about $9.45 per $10,000 deposited. The other detail that matters is how Us Bank handles early withdrawal penalties. For terms under 18 months, the standard penalty is 90 days of interest. For terms of 18 months or longer, it jumps to 180 days of interest. I learned this the hard way when I needed $8,000 for a home repair at month eight of a 12-month CD. The penalty cost me about $200 in foregone interest and I had to take a partial withdrawal that reduced my principal going forward. Us Bank allows partial withdrawals but each one triggers a pro-rated penalty calculation based on the remaining term and current rates. The workaround I use now is to keep an equivalent amount in a Us Bank high-yield savings account as a buffer before locking money into a CD. This way I can pull from savings instead of breaking the CD.
The Laddering Strategy That Actually Works
CD laddering means splitting one large deposit across multiple CDs with staggered maturity dates. Instead of putting $60,000 into one 12-month CD, you put $20,000 into a 12-month CD, $20,000 into a 24-month CD, and $20,000 into a 36-month CD. Each year a portion matures and you can reinvest it at whatever the current rate is. This protects you from rate drops and gives you liquidity every 12 months. Here is what I do specifically with Us Bank. I maintain a three-ladder structure: one tranche matures every year at 12, 24, and 36 months. When one matures, I roll it into a new 36-month CD at the back of the ladder. This keeps the entire ladder intact indefinitely. The trick is timing the rolls to coincide with rate environments. In a rising rate cycle, I shorten the new CD to 12 or 24 months to capture faster rate increases. In a stable or falling cycle, I extend to 36 or 48 months to lock in current rates before they drop further. I track the Federal Reserve funds rate and the 2-year and 5-year Treasury yields every Tuesday morning. If the Treasury curve is steepening, I lean shorter. If it is flattening or inverting, I lean longer. One edge case you should know about: Us Bank does not allow you to add money to an existing CD after opening it. Each new deposit requires a brand new CD account. This means if you want to increase your ladder, you must open additional CDs and manage them separately. I used to open all my CDs in a single online session and just kept a running spreadsheet. Now I use a shared Google Sheet with color-coded rows for each CD, showing term start date, maturity date, current APY, penalty schedule, and next review date. It took me about 45 minutes to set up and now takes 5 minutes to update each quarter.
Get the Full Details

When Us Bank CDs Make Sense and When They Do Not
Us Bank CDs are reasonable if you value branch access, automatic renewal convenience, and the ability to set up direct deposit or payroll deductions that feed into your CD schedule. They also make sense if you already have a checking relationship and qualify for a higher tier rate by combining accounts. Us Bank offers rate bumps for customers who meet certain balance and activity thresholds in their banking products. I receive a 0.10% APY bump on my CDs because I maintain a Us Bank checking account with direct deposit and over 10 transactions per month. Without that, my rate would have been 4.95% instead of 5.05%. But Us Bank CDs are a poor choice if you are purely rate-driven and have no need for in-person banking. Online-only banks routinely offer rates 30 to 80 basis points higher on identical terms. The FDIC insurance coverage is the same either way since Us Bank is an FDIC-insured institution. There is no safety advantage to choosing Us Bank over Ally, Marcus, or Discover. The only real advantage is convenience and the occasional promotional rate bump. If your priority is maximum yield, the math is straightforward. Go online, compare the top 10 CD rates from FDIC-insured institutions, and pick the best one that fits your timeline. Us Bank should only be your first choice if the convenience premium is worth the yield difference to you personally. Another limitation worth noting: Us Bank does not currently offer a no-penalty CD product. If you want the flexibility to withdraw without penalty at any time, you need to look elsewhere. Capital One and Synchrony both offer no-penalty CDs with competitive rates. I use a Capital One no-penalty CD for the portion of my CD portfolio that I might need to access within 90 days. This gives me liquidity without sacrificing a rate that is still above 5.00% APY as of mid-2026.
Practical Steps to Open a Us Bank CD Today
Go to the Us Bank website and navigate to the CD rates page. Compare the current APY for the term you want, making sure you select the correct tier. Check whether you qualify for a rate bump by reviewing the balance and activity requirements for your existing Us Bank accounts. Log in to your online banking portal and select the CD product you want. You can open a CD with as little as $1,000 using funds already in your Us Bank checking or savings account, or you can fund it with an external transfer from another institution. External transfers take 1 to 3 business days to clear, so plan accordingly if you want the CD to start accruing interest immediately. Once the CD is open, set up automatic rollover instructions if you want the funds to renew at the same term. I recommend turning off automatic rollover and instead setting a calendar reminder for 14 days before maturity. This gives you time to compare the renewed rate against current market rates and decide whether to roll over, change the term, or move the money elsewhere. Automatic rollovers often renew at the prevailing rate at that moment, which could be significantly lower than what you locked in originally. I have seen this happen twice with Us Bank. In both cases, the renewed rate was 50 to 75 basis points lower than my original rate, and I lost hundreds of dollars in interest because I did not review the renewal terms in time.
The Bottom Line
Us Bank CDs are a solid option for customers who want a familiar bank with branch support and do not mind accepting slightly lower rates for that convenience. They are not the best option for pure yield seekers. The laddering strategy works with Us Bank CDs just as well as with any other CD product, and the partial withdrawal workaround I described earlier can prevent costly early withdrawal penalties. The most important thing is to stay active in monitoring your CD terms, especially around renewal dates, and to compare Us Bank's rates against online competitors before locking in a new CD. Rate environments change frequently and the spread between Us Bank and direct online banks can widen or narrow within a single quarter.