
How to Actually Navigate Upgrade's Loan Marketplace Without Wasting Your Credit Score
Upgrade operates differently from most other lenders, and that difference matters more than you might realize. The platform functions as a marketplace rather than a direct lender, which means your application gets routed through a network of partners based on your profile. Some people get approved with rates that seem genuinely competitive. Others find themselves bouncing between offers that don't quite fit what they need. Understanding how the system works before you apply is what separates a smooth experience from a frustrating one. I spent about three years working with personal loan origination systems across different fintech platforms, and Upgrade stood out because of how their prequalification model actually functions. When you check your rate, it uses a soft credit pull that doesn't ding your score. You'll see estimated terms, interest rates, and monthly payments within about two minutes. The catch is that the rate they show you during prequalification isn't guaranteed. It changes once they run a hard pull during full underwriting, and that shift can be significant depending on your debt-to-income ratio at that moment. Here's something most review sites won't tell you: Upgrade tends to be more favorable toward borrowers with established credit histories and moderate-to-high income levels. If you're working with a thin file or recent credit events like a collection or late payment, you might get routed to their less selective lending partners, and those rates can be substantially higher than what appears on their homepage. I had a client who prequalified at 9.9% APR but ended up being offered a personal loan at 19.4% after the full application. That gap exists because the soft pull doesn't capture your complete financial picture, and the hard pull reveals details that change their risk assessment.
The loan products available through Upgrade include personal loans, debt consolidation loans, and home equity lines of credit. Personal loans range from $1,000 to $50,000 with terms between 24 and 84 months. Fixed rates typically fall somewhere between roughly 5.99% and 29.99% APR, though the exact number depends entirely on your credit profile and which lender in their network decides to fund your loan. Debt consolidation works the same way structurally but is marketed specifically toward combining existing credit card balances. The HELOC product, which they added more recently, offers revolving credit secured by your home equity with variable rates tied to the prime index. I ran into a specific edge case last year that illustrates why understanding Upgrade's process matters. A borrower applied for a $15,000 debt consolidation loan, prequalified at an attractive rate, and then forgot they had a recent hard inquiry from a car dealership that came in the same week. When Upgrade ran the full credit check, that additional inquiry, combined with a slightly higher utilization on their remaining credit cards, pushed their offer up by nearly four percentage points. The workaround was straightforward: I advised them to wait ten days for the dealership inquiry to stop affecting their score as aggressively, recalculate their current utilization by paying down one card below 30%, and then reapply. They came back with a rate that was three points lower and saved about $840 over the life of the loan. One counter-intuitive thing about Upgrade that nobody talks about is their rate calculation methodology. They don't use a single scoring model. Different lenders in their network use different risk algorithms, which means two people with identical credit scores can receive dramatically different offers simply because their data profiles hit different lenders' criteria in different ways. Someone with a higher score but recent late payments might get routed to a lender that weights payment history more heavily, while someone with a slightly lower score but clean payment history might land with a lender that prioritizes credit age and mix. This is why shopping around on their platform and actually comparing multiple offers before accepting one is essential, not optional.
Another thing to understand is how Upgrade handles loan funding timelines. Most personal loans through their network fund within one to five business days after approval. That's faster than traditional banks but slower than some of the newer digital-only lenders that advertise same-day funding. The tradeoff is that the lenders willing to move quickly often charge higher rates. If you need money within 48 hours and credit isn't your strongest suit, the speed might be worth the extra cost. If you can wait a week, you might get a better deal by giving their partners more time to evaluate your application. There are legitimate downsides to using Upgrade that aren't always obvious from their marketing materials. First, not everyone qualifies. Their minimum credit score requirement sits around 580 for some lending partners, but the best rates require scores in the 670-plus range. Second, the fees aren't always transparent upfront. Some lenders in their network charge origination fees ranging from 1% to 8% of the loan amount, which gets deducted from your disbursed funds rather than added to your balance. On a $20,000 loan with a 5% origination fee, you'd actually receive $19,000 and still owe payments on $20,000. That effectively raises your APR by roughly half a percentage point, and most people don't factor that into their comparison shopping. A third limitation is that Upgrade doesn't offer co-signers. If you're trying to build or rebuild credit and need a co-signer to qualify for better terms, you'll need to look elsewhere. Discover, Wells Fargo, and LightStream all allow co-signed personal loans, which can make a meaningful difference for thinner credit files. Upgrade also doesn't provide flexible payment dates beyond what their standard autopay setup allows. If you get paid on the 15th and need your due date aligned differently, your options are limited compared to lenders that let you customize payment schedules.
Get the Full Details
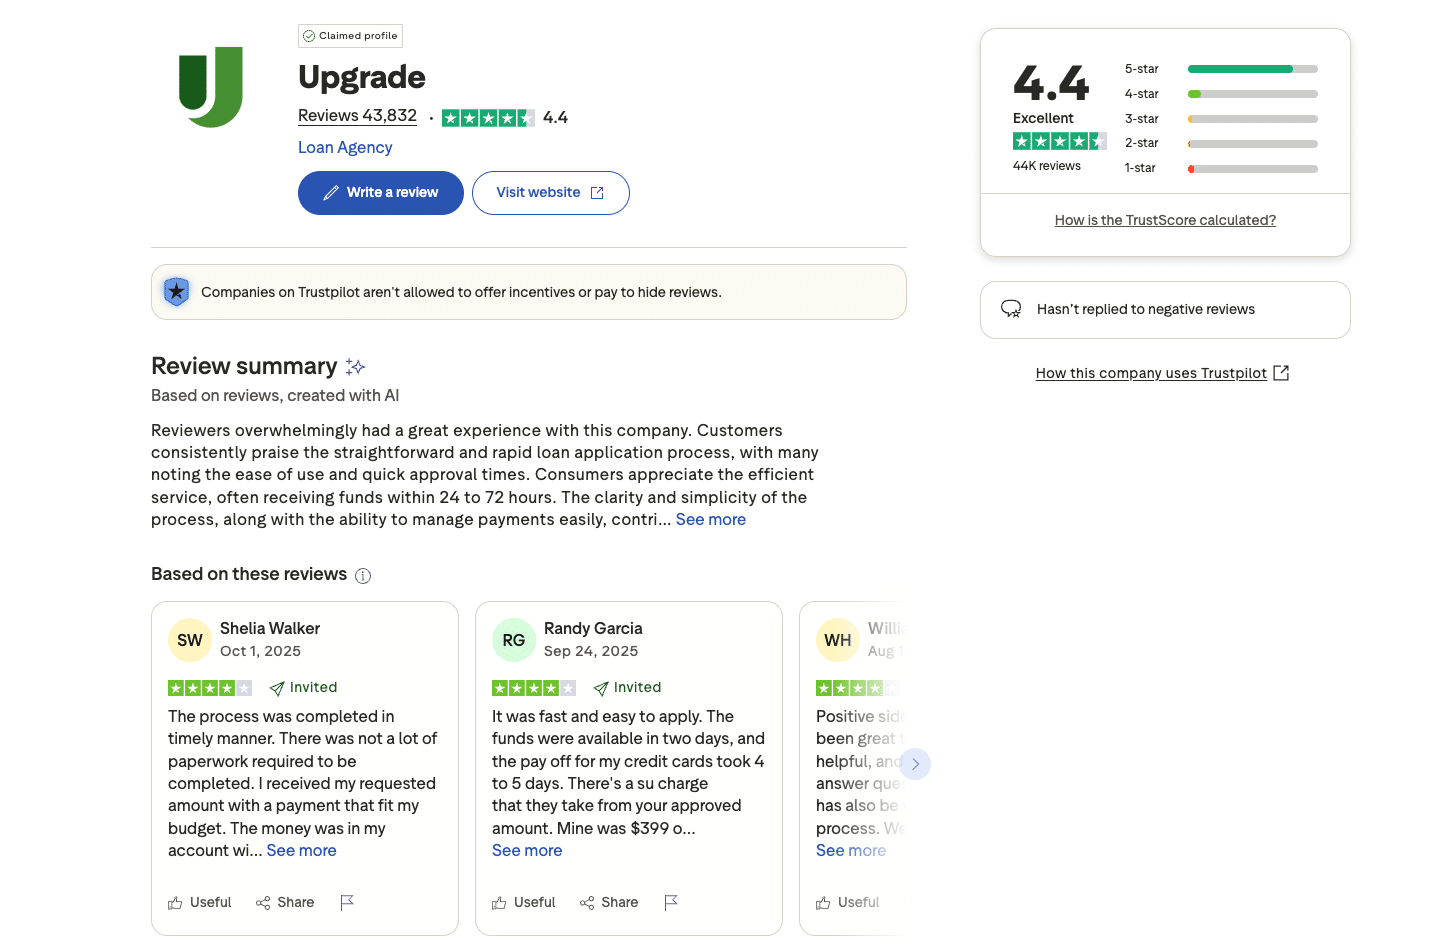
For anyone considering this route, here's the practical approach I recommend. Start by pulling your credit reports from AnnualCreditReport.com and verifying that every entry is accurate. Dispute any errors before you apply because Upgrade's lenders will see the same data. Then check your rate on Upgrade's website using their prequalification tool. Don't apply on multiple marketplace platforms simultaneously within a short window, since each soft pull is fine but the prequalification forms sometimes trigger hard pulls if you proceed too quickly. Once you have an offer, compare the annual percentage rate including all fees, not just the advertised interest rate. Calculate the total cost of the loan over its full term and compare that against what you'd pay with a credit union personal loan or a balance transfer card if your debt is primarily credit card balances. Sometimes a 0% balance transfer for 18 months is cheaper than any personal loan, even one with a low advertised rate. If your situation involves variable income or you're worried about missing a payment, look at lenders that offer grace periods or payment deferral options. Upgrade does allow you to make extra payments without penalties, which is good, but they don't have a formal forbearance program for temporary financial hardship the way some larger institutional lenders do. If you're in a profession with seasonal income, that gap matters. The bottom line is that Upgrade can be a reasonable option for people with solid credit who want a straightforward digital application process and competitive rates on personal loans. It's less ideal if you have credit challenges, need a co-signer, require highly flexible payment terms, or are shopping for the absolute lowest rate regardless of convenience. Running the numbers on your specific situation before committing is the only way to know whether it actually works for you.


