How The Torrid Comenity Bank Partnership Actually Works
Comenity Bank issues store credit cards for a lot of retail brands, and Torrid is one of them. The program itself isn't anything special, but understanding how it functions day to day matters more than the marketing copy on their website. When you apply for the Torrid card through Comenity, you get a retail-specific credit line. It works at checkout, both online and in-store. The rewards structure is built around Torrid purchases. That is about the scope of it.
Unwrapping The Benefits Of Torrid Comenity Bank A Retail Partner Like No Other
The main benefits are straightforward: financing promotions, a rewards cadence tied to Torrid spending, and occasional member-only discounts that stack with sales. The financing offers are usually the big draw. They run periodic promos like no interest if paid in full within six months on purchases above a certain threshold. Those offers shift constantly, so checking your account dashboard before checkout is worth doing. The rewards side typically gives you points or a discount percentage back on Torrid purchases. It is not a general cash-back card. You will not earn meaningful returns buying groceries or gas with it. That is by design. The card is meant to keep your spending inside Torrid.
What To Expect On The Application Side
The application runs through Comenity's portal. They do a soft pull to start, then a hard inquiry once you accept the offer. Credit score requirements tend to sit around fair to good range, usually 640 to 699 based on what I have seen across similar retail cards. Credit limits on these cards are often low at the start. Mine came in around two hundred dollars. That is normal for a store card. It scales up over time if you pay on time. I would not expect a high limit upfront, and it does not matter much if you are only using it at one retailer.
Get the Full Details

Financing Promotions And How To Actually Use Them
This is where most people mess up. The deferred interest offers sound generous until you miss a single payment or do not pay the full balance by the promo end date. Then the interest backs up from the original purchase date. That is not a grace period issue. That is deferred interest, and it is brutal. My workaround has been to set calendar reminders for the promo end date thirty days out. Then again seven days out. I also calculate the exact monthly payment needed to clear the balance, not just the minimum. The minimum will keep you from defaulting, but it will not save you from the interest trigger. For example, if you put a four hundred dollar purchase on a six month no-interest offer, you need to budget roughly sixty-seven dollars per month to finish it clean. Anything less and you risk triggering the interest clause. Set up automatic payments for that exact amount. Do not rely on remembering to pay manually each month.
Rewards That Actually Add Up
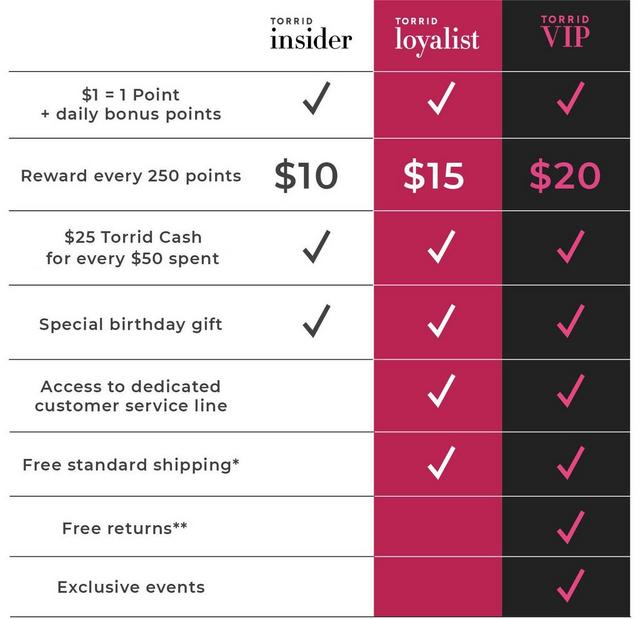
The point system is simple enough. You earn a percentage back on Torrid purchases. The rate fluctuates with promotions. Sometimes it is five percent. Sometimes it is ten during a targeted event. It rarely stays constant for long. What people miss is that rewards often come as merchandise credits, not statement credits. That means you have to shop at Torrid to use them. If you only buy there anyway, that is fine. If you got the card hoping to earn something usable elsewhere, you are looking at it wrong. Another nuance: rewards may have expiration windows. Some programs let points sit indefinitely. Comenity affiliated cards have varied on this over the years. Check your terms periodically. I lost about thirty dollars in rewards once because I assumed they rolled over and they did not. Worth noting.
The In-Store Experience
Using the card at a Torrid register is the same as any other credit card swipe. Nothing unusual there. The real value shows up during checkout when you see exclusive member pricing. These are not always advertised floor-level. You sometimes have to ask or check your account for available offers before you go in. I ran into a specific edge case once where a sale price was not stacking with my card rewards at a physical location. The associate rang it up at full sale, and the rewards did not apply to the discounted portion. I had to call customer service, explain the transaction, and get a goodwill adjustment posted to my rewards balance. It took about twelve minutes on the phone and they credited it within forty-eight hours. Not ideal, but fixable if you catch it quickly.
Downsides And Where This Falls Apart
The biggest downside is the narrow utility. This card only helps you at Torrid. If you shop there a couple times a year, the card earns you almost nothing relative to the effort of managing it. You are better off paying with a general rewards card and skipping the credit inquiry. The interest rates after any promo period are steep. I have seen APRs in the twenty-five to thirty percent range on these retail cards. That is standard for subprime-adjacent products, but it punishes people who carry balances. You should never carry a balance on this card unless you fully understand the cost. Customer service is another friction point. Comenity handles support for dozens of retail partners, and the experience is generic. You will not get a dedicated Torrid concierge. When issues arise, you navigate a standard call center flow. Response times vary, but expect hold times between ten and twenty minutes during business hours.
Alternatives To Consider
If your goal is just saving money at Torrid, some general cash-back cards offer rotating category bonuses that include department stores or clothing retailers. A card giving you three percent back at Torrid with no annual fee and no single-retailer lock-in might actually serve you better than the store card. You get the discount without the deferred interest trap or the low credit limit. If you are a frequent Torrid shopper and you are disciplined about paying off balances monthly, the store card makes sense. The rewards and financing promos add up. If you are not disciplined, do not get it. The interest mechanics will cost you more than any rewards ever will.