Understanding Executive Compensation at Major Airlines
CEO pay at public companies like Delta Air Lines isn't just a salary number. It's a structured package built from base pay, performance bonuses, and stock awards that vest over time. When you're looking at how much someone is actually worth, you need to separate what they earn from what they own. Ed Bastian took over as Delta's CEO in January 2017. Before that, he spent 34 years at the company in various leadership roles, including Chief Operating Officer. His total compensation reflects both his long tenure and the performance-based structure common in aviation.
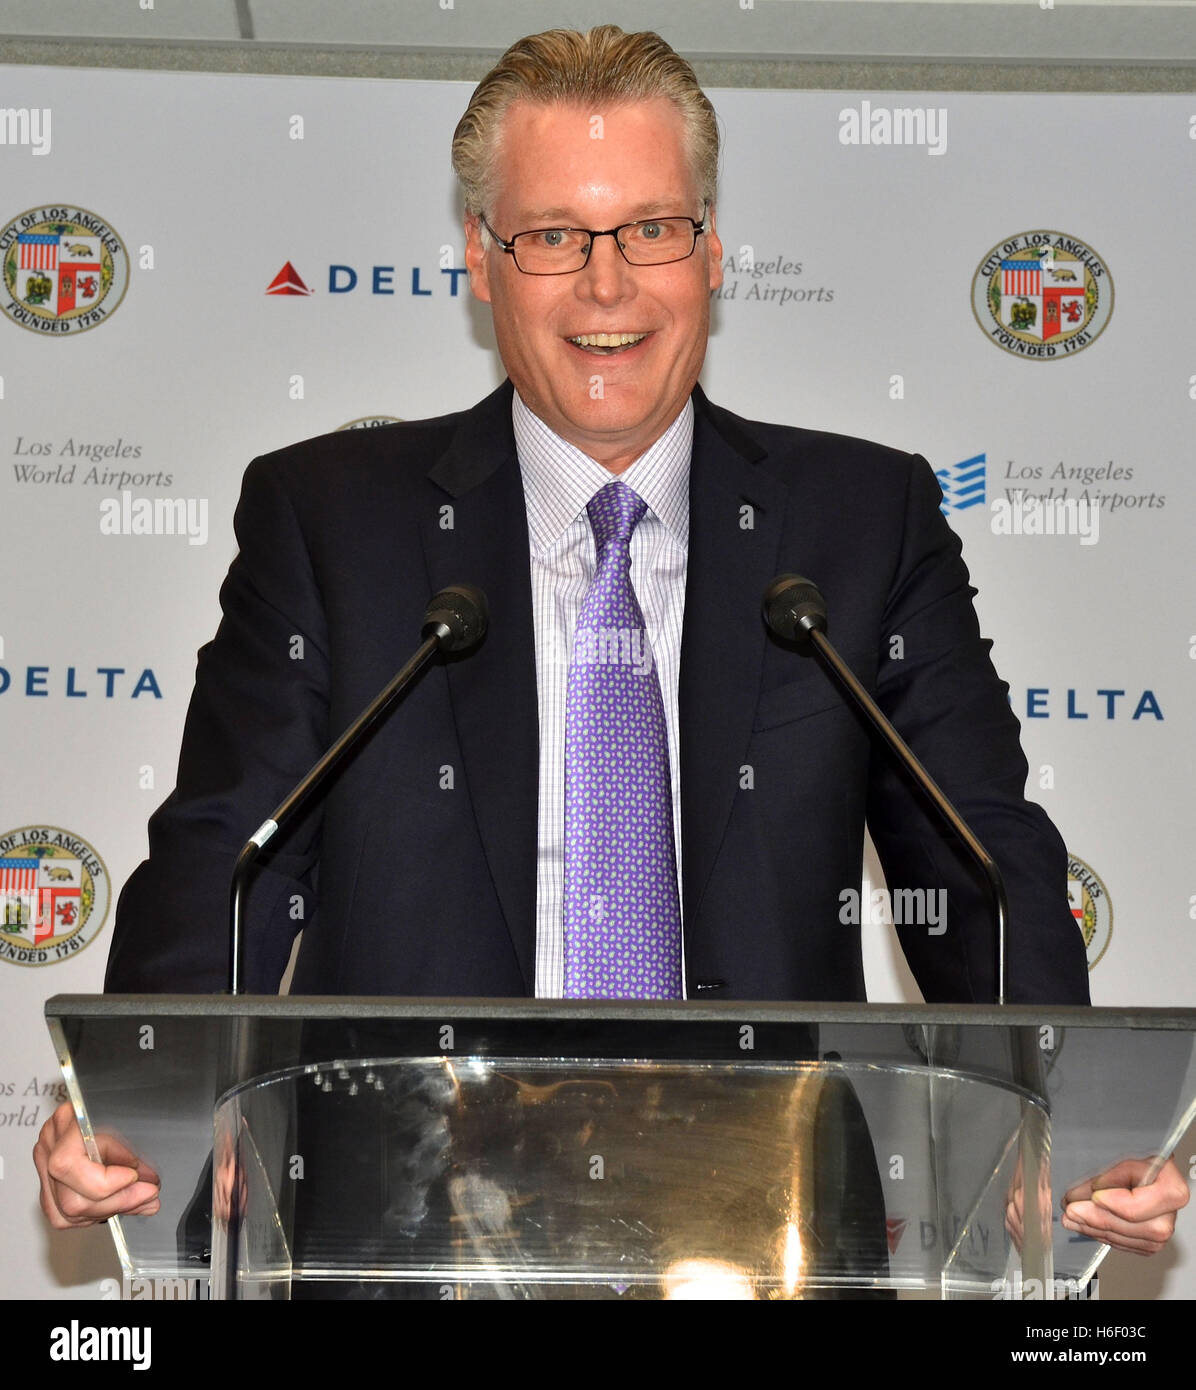
Unveiling The True Wealth Of Ed Bastian How Much Is The Delta Air Lines CEO Worth
Looking at SEC filings and proxy statements gives you the most accurate picture. Delta's annual proxy filing for 2023 shows Bastian received approximately $14.7 million in total compensation. That figure breaks down into roughly $1.15 million base salary, a performance bonus around $5.9 million, and the rest in stock awards and option grants. The stock component matters most for long-term wealth. Bastian holds substantial Delta equity that appreciates or declines with the company's performance. Delta's stock has been volatile over the past few years due to pandemic recovery, fuel costs, and labor negotiations. When the stock performs well, his net worth picture changes significantly year over year. Estimating his total net worth is tricky. Most public reports place it in the range of $40 to $80 million, depending on how you count unvested stock options and how you value his Delta shares. The lower end assumes conservative stock valuations; the higher end factors in years of accumulated equity grants that may have appreciated substantially.
How Airline CEO Compensation Actually Works
Most people don't realize how much of CEO pay is deferred and tied to stock performance. At Delta, Bastian's equity awards vest over multiple years, which means the compensation you see in a single year's proxy isn't fully realized income. Some of it won't even be mineable if the stock drops. Delta uses a mix of restricted stock units and performance share units. RSUs are simpler — you get shares after a time period. Performance shares depend on metrics like revenue growth, customer satisfaction scores, and operational efficiency targets. If Delta misses those goals, the payout shrinks. I've seen this play out with several airline CEOs during earnings seasons. When the stock is under pressure, management talk about "long-term value creation" starts sounding less like inspiration and more like justification for compensation that might not materialize the way it's reported. Delta's board has been transparent about tying pay to performance, but the structure still favors executives when targets are met.
Get the Full Details

The Bigger Picture of Executive Wealth
Bastian's wealth isn't just from Delta stock. Like most C-suite executives at major corporations, he likely has diversified investments, real estate holdings, and possibly stakes in private companies. Public proxy filings only show what's compensation-related. They don't capture personal investment portfolios or family wealth transfers. His father, also named Ed Bastian, was a successful businessman in Georgia. Family connections and inherited assets probably contribute to the lower end of net worth estimates. That doesn't diminish the career earnings, but it adds context. One counterintuitive thing about airline CEO pay: base salaries at major carriers are surprisingly flat. The real money is in equity, which creates misalignment sometimes. Executives might push for short-term stock bumps through cost cuts or buybacks while ignoring long-term investments in fleet renewal or customer experience. Delta has been gradual about retiring older aircraft and investing in newer, more fuel-efficient planes, which pays off over decades but drags on quarterly margins.
The downside of this compensation model is that it rewards financial engineering more than operational excellence. Stock-based pay incentivizes executives to time option exercises and manage earnings per share rather than build sustainable competitive advantages. It's a known problem in corporate governance, and airline boards have been slower to fix it than many other industries. If you're trying to understand executive wealth, the cleanest approach is reading the proxy statement, tracking stock performance over a multi-year period, and remembering that reported compensation numbers are accounting figures, not cash in the bank. The real picture emerges only when you follow the equity vests and option exercises through filing cycles.