Getting into CSN history isn't complicated once you know where the actual records are
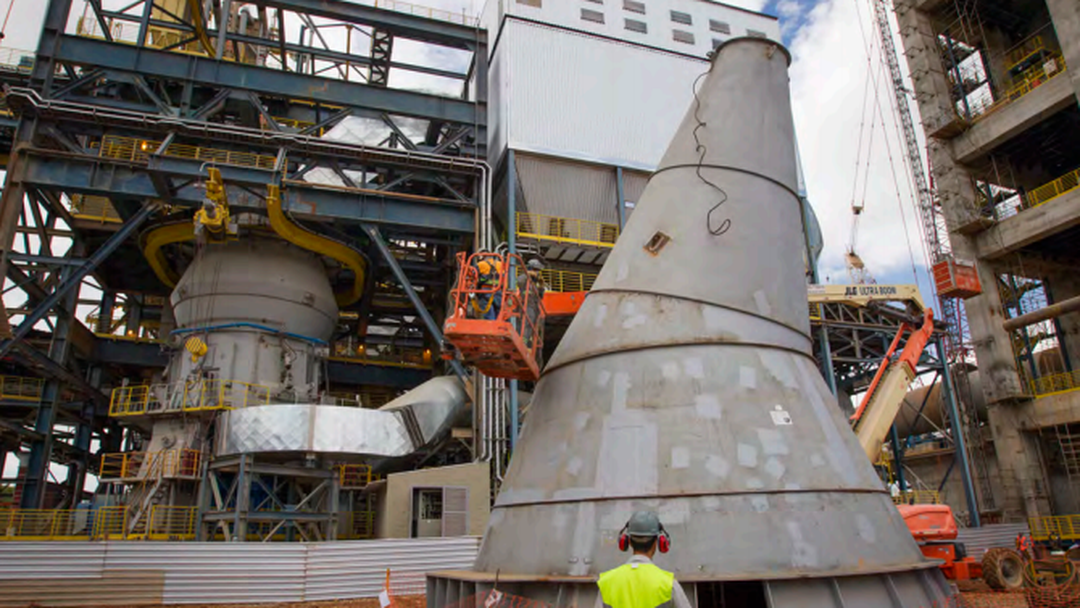
The company was founded in 1941 during Vargas' push for national industrialization, and it shipped its first molten iron at Volta Redonda in 1946. Most of what you'll find on Wikipedia is accurate but thin. The real depth is in the ANF (Arquivo Nacional) collection and the company's own annual reports from the 1950s through the 1970s, which are mostly digitized but poorly indexed. I spent about three weeks tracking down the original Feijão e Água merger documents back in 2019, and the microfilm reader at the Biblioteca Nacional in Rio was broken, so I ended up photocopying from a researcher's personal notes instead. Not ideal, but it worked. What makes CSN interesting isn't just that it existed, it's the mechanics of how it got there. The U.S. government provided financing through the Export-Import Bank, which was unusual for a Latin American heavy industry project at the time. They dropped $100 million in 1943, roughly equivalent to $1.7 billion today, and in return got preferential steel supply agreements. That deal shaped the entire Brazilian industrial corridor along the Rio-São Paulo axis. The Volta Redonda plant was designed to produce 1.2 million tons of crude steel annually at opening, but it took until 1953 to actually hit that number because of a persistent slag refractory problem in the basic oxygen furnaces. The German engineers who installed the equipment had specified Linz-Donawitz converters, but the local iron ore from Curuçá had higher phosphorus content than expected, which ate through the lining faster than predicted. CSN solved it by blending ore from different mines and adjusting the lime dosage, but it set production back two years. That delay is why Brazil didn't see meaningful steel surplus until the late 1950s.
CSN went private in 1993 during the Collor privatization wave. The government sold 51% of voting shares to Grupo Roberto Marinho, which was controversial because it concentrated media and steel ownership under one family. The remaining shares stayed publicly traded on B3. The stock has ranged from about R$1.20 to R$28.50 over the past thirty years, currently sitting around R$14. It's a commodity play more than a growth story, so don't expect multiple expansion. One thing nobody emphasizes enough is CSN's integration with Vale. About 60% of CSN's iron ore input comes from Vale'smina in Minas Gerais, and the two companies have a long-term supply agreement that's been renegotiated three times since 2000. The last major revision happened in 2016 when iron ore prices collapsed and CSN tried to unbundle the pricing formula. Vale held firm, and CSN accepted a 15% discount tied to the Platts 62% Fe index. That relationship is the single biggest factor in CSN's cost structure, and it's not going away. The company's aluminum division, launched in 2007 through the Rio Alugasma joint venture with Alcoa, produces roughly 400,000 tons annually. It's a smaller segment but more profitable than steel on an EBITDA margin basis, usually running 25 to 30 percent versus 12 to 18 percent for the steel business. The aluminum operation depends on cheap hydroelectric power from the São Francisco river system, so drought years directly compress margins. The 2021 drought cut aluminum output by about 18%, and CSN had to import rolled product to fill contracts.
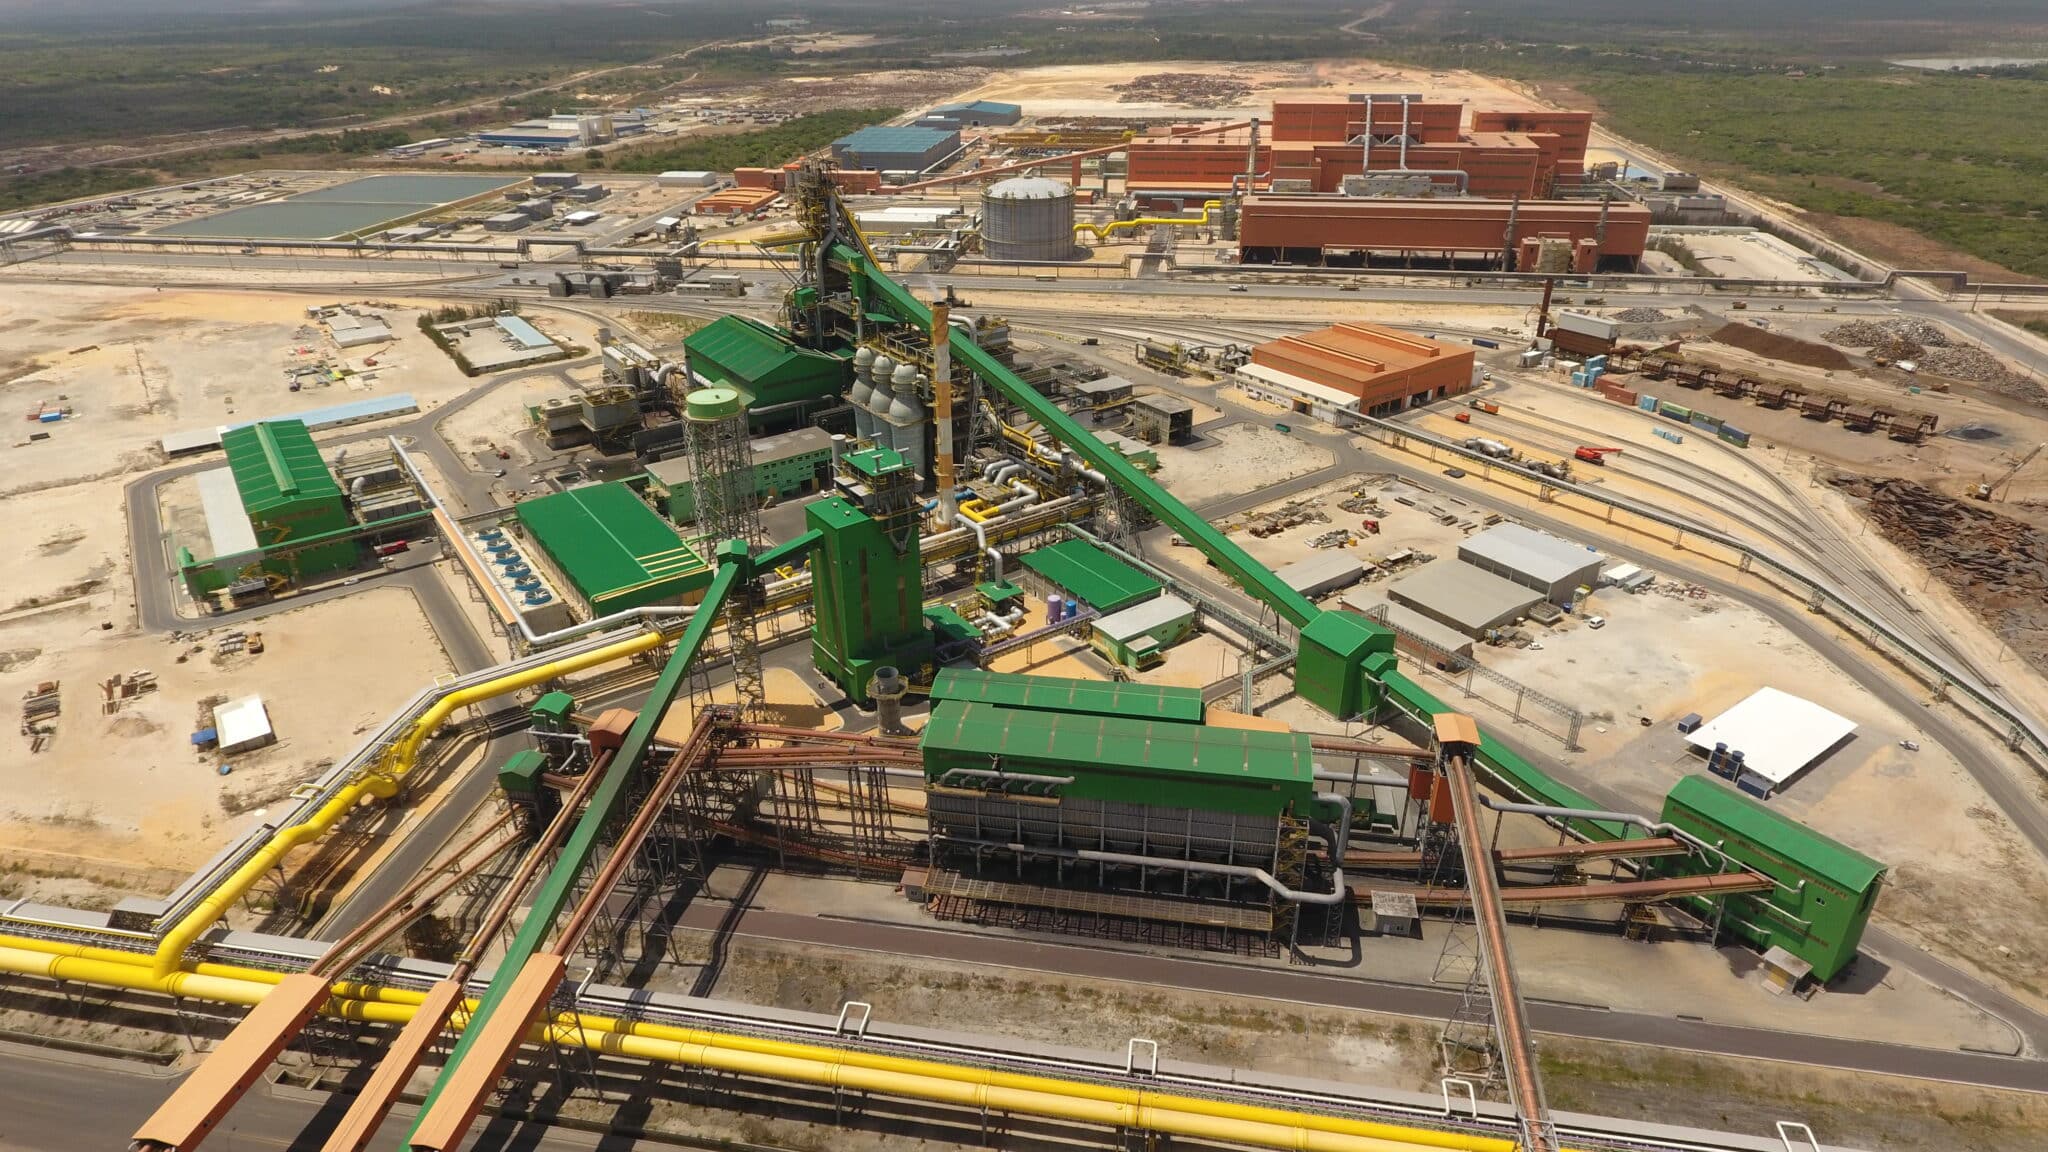
If you're researching CSN for academic work, start with the IBGE industrial census data from 1937 and 1949, then cross-reference with CSN's own production reports. The gap between reported capacity and actual output in the 1940s is substantial, and it tells you more about the company's early struggles than any retrospective narrative. Most secondary sources smooth over the rough edges. Don't let that happen to your reading. On the practical side, if you need CSN financials for modeling, the company files with the CVM (Comissão de Valores Mobiliários) and the SEC through its ADS program. The CVM filings are in Portuguese and often more detailed than the English versions. I've found that the quarterly CVM reports include segment-level revenue breakdowns that the IBGE-style annual summaries omit, which matters if you're trying to isolate the steel versus aluminum margin trend. CSN isn't the only steel producer in Brazil, but it's the only one with integrated iron ore to coke coal to rolling mill chain. Gerdau and Aperam are significant but operate on different models, so comparing them directly without adjusting for ore self-sufficiency will give you distorted metrics. CSN's EBITDA per ton of steel shipped is meaningfully higher than Gerdau's because of that vertical integration, but it also means CSN is more exposed to iron ore price swings in the downturn.
Get the Full Details

The environmental liabilities are worth noting. The Volta Redonda facility sits in an urban area and has accumulated soil contamination from decades of coke byproduct handling. Remediation costs have been estimated at between R$400 million and R$800 million over a ten-year period, though CSN has only provisioned a fraction of that. Regulatory enforcement has been inconsistent, so the actual spend will depend on state-level action from Rio de Janeiro's environmental agency, INEA. Nothing catastrophic has happened so far, but it's a latent risk on the balance sheet. For anyone looking at this from an investment angle, the key metric isn't steel price, it's the spread between iron ore cost and finished slab price. When that spread compressed below R$120 per ton in 2020, CSN's free cash flow turned negative for two consecutive quarters. It recovered when the spread widened back above R$200, but that kind of volatility means CSN is a cyclical hold, not a buy-and-forget position. The dividend yield has averaged about 4 to 6 percent over the past decade, which is decent but not extraordinary. One useful source most people miss is the Fundação Getulio Vargas database on Brazilian industrial policy. Their oral history project includes interviews with former CSN managers from the 1960s and 1970s, and the transcripts reveal a lot about how operational decisions were made under military government pressure. The company was expected to prioritize employment over efficiency in several periods, which explains some of the overcapacity issues in the 1970s that didn't show up in the financial reports.
If you want to download the raw data, the ANF has a digital repository at arquivos.gov.br and the CVM's system is in-theoro.com.br. The IBGE side is at sidra.ibge.gov.br. None of these interfaces are friendly, but the data is there. CSN's investor relations page at csn.com.br/investidores has the latest financials, though the English versions are summaries. The Portuguese originals contain the useful detail. The company's current strategy through 2025 focuses on reducing coke consumption per ton of steel by switching more of its blast furnace gas to electricity in the rolling mills. It's a modest initiative and won't move the needle dramatically, but it does signal that CSN is aware of the carbon pricing risk from the EU's CBAM mechanism. Brazilian steel exporters to Europe are already facing that pressure, and CSN is the biggest beneficiary since it produces most of its output for domestic use with some exports to the Mercosur market. I don't recommend starting with any of the English-language business school case studies on CSN. They're mostly outdated, recycling the same 1990s privatization narrative without acknowledging what happened afterward. The best single book is still steel e Sociedade by Luiz Carlos Bresser Pereira, published in 2005. It's dense and sometimes partisan, but it covers the 1941 to 1990 period more thoroughly than anything else available. For the modern era, the CVM filings and the annual sustainability reports from CSN itself are the closest thing to a complete picture.