Why Your Mortgage Payment Looks Lower Than It Actually Is
I have been reviewing home purchase numbers for over twelve years, and I still see buyers walk away from Zillow's calculator convinced they can afford a house that costs roughly $400 to $700 more per month than they realized. The tool itself is not malicious. It is just missing half the equation. The calculator asks for four inputs and gives you one output: a monthly principal and interest figure. That single number is technically correct for what it calculates, but most people treat it like the total housing payment. It is not. It is only the debt service piece. Everything else gets left out unless you add it yourself. I used to let the default view sit on the page and just move on. Then I ran into a situation where a client was pre-approved for $385,000 and put 20 percent down. The calculator showed $1,842 per month. Close enough on paper. What the page did not surface without extra clicking was that his property tax in that county came to $4,200 annually, homeowners insurance at roughly $1,650 a year, and an HOA fee of $280 monthly. The real total payment landed around $2,960. That gap is not trivial. It changes qualification brackets on its own.
What The Calculator Actually Shows and What It Leaves Out
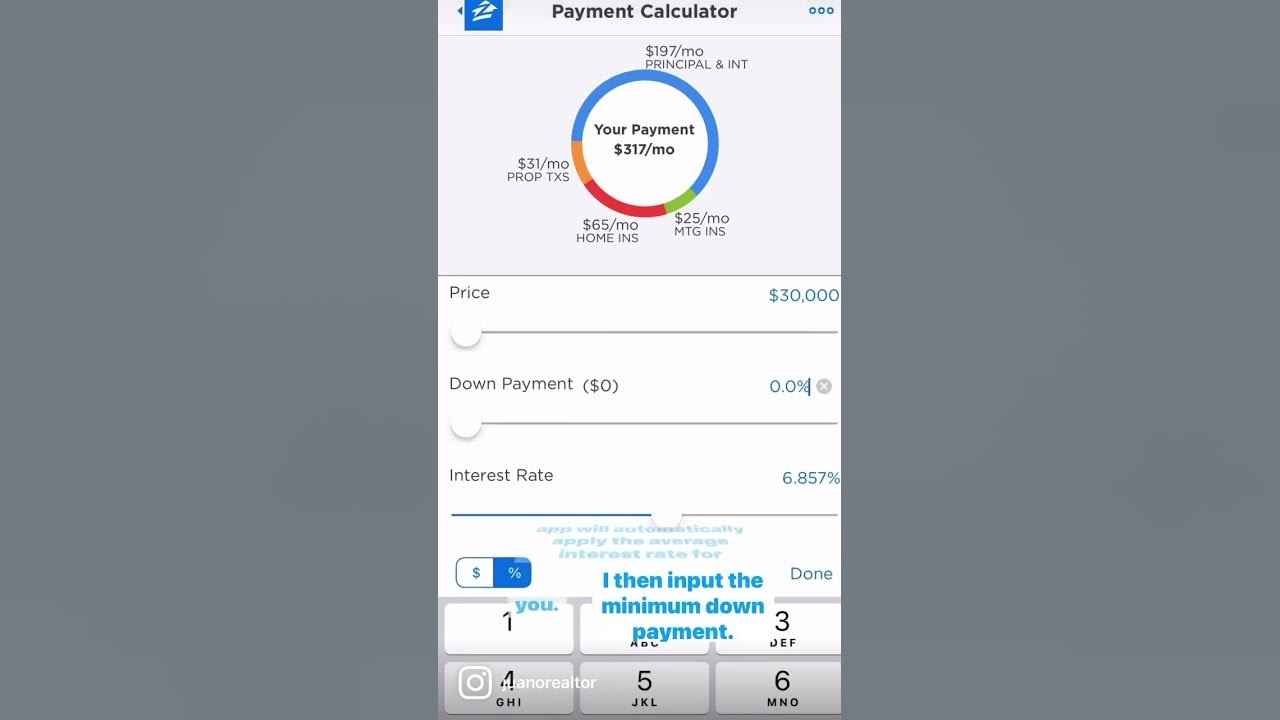
The standard mortgage calculator breaks down into principal, interest, property tax, homeowners insurance, and sometimes HOA or PMI. Zillow's default view emphasizes principal and interest because that is what drives the headline payment most buyers picture. The other line items exist in toggles or a second table most people never open. You have to scroll or click "See estimated monthly payments" to get the full breakdown. Here is the practical list of what typically gets hidden or buried: Property taxes. These vary wildly by zip code and are rarely pulled accurately into the default view unless the listing includes that data. In some counties, annual taxes equal 2.5 percent of assessed value. In others, they sit closer to 0.8 percent. The calculator does not always know which you are dealing with until you type in a manual estimate.
Private mortgage insurance. This appears once you drop below 20 percent equity, but the calculator sometimes shows a monthly PMI number that underestimates what lenders actually charge. Lenders base PMI on credit score, loan type, and combined loan-to-value ratio. A single monthly figure from a web calculator can be off by $30 to $90 compared to a lender's actual quote. HOA fees. These are listing-specific and completely absent unless you enter them manually. Condos and planned developments often carry monthly fees ranging from $150 to $600 depending on amenities. That is a hard number to ignore when you are budgeting. Maintenance and reserve costs. The rule of thumb most inspectors use is 1 percent of the home value per year for basic maintenance. On a $400,000 house, that is $333 monthly. Roof replacements, HVAC service, water heater swaps, and foundation patches do not show up in any online tool. They show up in your bank account instead.
Get the Full Details
Closing costs. These range from 2 to 5 percent of the purchase price depending on location, loan program, and lender fees. A $350,000 purchase might cost you $7,000 to $17,500 at closing. The calculator does not factor this into the monthly payment because it is a one-time expense, but it absolutely affects how much cash you need on day one.
How To Use The Tool Without Getting Misled
The fastest way to get closer to reality is to open the calculator, enter your numbers, then expand the full payment breakdown before you share the result with anyone else. Do not stop at the headline figure. Scroll or click through to the line-item table. If the tool does not pull local tax data automatically, you need to enter a manual estimate based on recent sales in that area. I usually do three things before I hand a buyer a number from any online calculator: First, I look up the actual tax rate for the county using the assessor's site. Most counties publish annual assessment data publicly. A quick search for the zip code plus "property tax rate" usually surfaces the effective rate within two minutes.
Second, I check the HOA schedule if the property is part of a community association. These fees change occasionally and the listing may not reflect the current amount. I call the management office directly when the listing data seems vague. A five-minute phone call saves a lot of embarrassment later. Third, I run the number through a lender's built-in calculator instead. Bank of America, Wells Fargo, and local credit unions all have internal tools that factor in your exact credit score, loan program, and debt-to-income ratio. The difference between a generic web calculator and a lender's quote averages around 4 to 8 percent on the total monthly payment. That gap matters when you are sitting at the margin of qualification.

Edge Cases Where The Calculator Breaks Completely
I ran into a case last spring involving an ARMs seller's market where the calculator completely fell apart. The listing showed a 5/1 adjustable-rate mortgage at 5.75 percent. The monthly payment looked manageable. The problem was that the rate was only fixed for the first five years. After that, it adjusted annually based on the SOFR index plus a lender margin. By year six, the rate had climbed to 7.9 percent. The payment jumped roughly $210 per month. The calculator had no way to predict that adjustment because it does not pull live index data or assume future rate movements. Another issue shows up with FHA loans. The minimum down payment is 3.5 percent, but FHA requires mortgage insurance premiums that last the life of the loan if you put less than 10 percent down. Zillow's calculator sometimes omits the annual MIP or shows a stale monthly figure. The real payment including FHA MIP can be $60 to $120 higher than the default display suggests. I learned this the hard way when a buyer qualified on paper but failed at underwriting because his actual debt-to-income ratio exceeded 43 percent once the full insurance costs were included. Coa signers complicate the math even further. Some buyers bring in a parent or sibling to help with qualification. The calculator does not account for co-ownership structures, gift funds, or non-traditional down payment sources. If you are using a family gift for the down payment, you need a gift letter and the funds must sit in your account for a certain period before closing. The monthly calculator will not flag any of this. Only a lender's underwriter will.
What You Should Do Instead of Trusting a Single Number
I recommend getting a pre-approval letter from a local lender before you fall in love with any listing. A pre-approval tells you exactly what interest rate, loan program, and monthly payment you qualify for based on your actual income, assets, and credit profile. It takes one business day and usually costs nothing. The resulting number is far more accurate than anything a free calculator can generate. If you want to stay within a realistic budget, I suggest adding property tax, insurance, HOA, maintenance, and PMI to the calculator's principal and interest figure manually. Use the actual tax rate for the county, not the listing's guess. Estimate insurance at $80 to $150 monthly for a standard policy on a $350,000 home. Factor in HOA fees if they exist. Add 1 percent of the purchase price annually for maintenance and divide by twelve. Include PMI if your down payment sits below 20 percent. I keep a simple spreadsheet with these line items for every property I review. Column A is the address. Column B is the list price. Column C is the calculator's principal and interest. Columns D through H are tax, insurance, HOA, maintenance, and PMI. Column I sums them into a total monthly payment. This process takes about eight minutes per property and eliminates most surprises before I even schedule a showing.
When to Walk Away From a Deal
If the total housing payment exceeds 30 percent of your gross monthly income, you are already pushing the standard affordability guideline. If it exceeds 38 percent, most lenders will scrutinize your debt-to-income ratio closely and may require a larger reserve or higher credit score. The calculator does not warn you about these thresholds. Only your lender will. I had a client who kept circling back to properties where the calculated payment looked fine on paper but exceeded 42 percent of his income once taxes, insurance, and HOA were added. He was frustrated. I told him to step back and look at homes in the next price bracket down. He did. The monthly payment dropped by $310 and he closed without stress. The lesson was simple. The calculator had sold him on a number that would not have held up in practice.

The Bottom Line
Zillow's mortgage calculator is a starting point, not a final answer. It gives you a rough sense of what principal and interest look like on a given loan amount and rate. It does not replace a lender's approval, a local tax lookup, or a realistic maintenance estimate. Use it to narrow your search. Do not use it to approve a purchase. I still see buyers miss the same traps every quarter. They fall in love with a house because the monthly payment on a webpage looks affordable. They skip the tax check. They forget the HOA. They overlook PMI. They close and realize six months later that their actual housing cost exceeded their budget by nearly $400 monthly. The calculator was never the enemy. Not paying attention to what it leaves out is. If you want a tool that gets closer to reality, ask your lender for a Loan Estimate after you submit a formal application. That document breaks down every fee, every rate assumption, and every monthly line item based on your actual financial profile. It arrives within three business days and carries legal weight. A web calculator will never match that level of precision.


