What Actually Goes on Form 1120
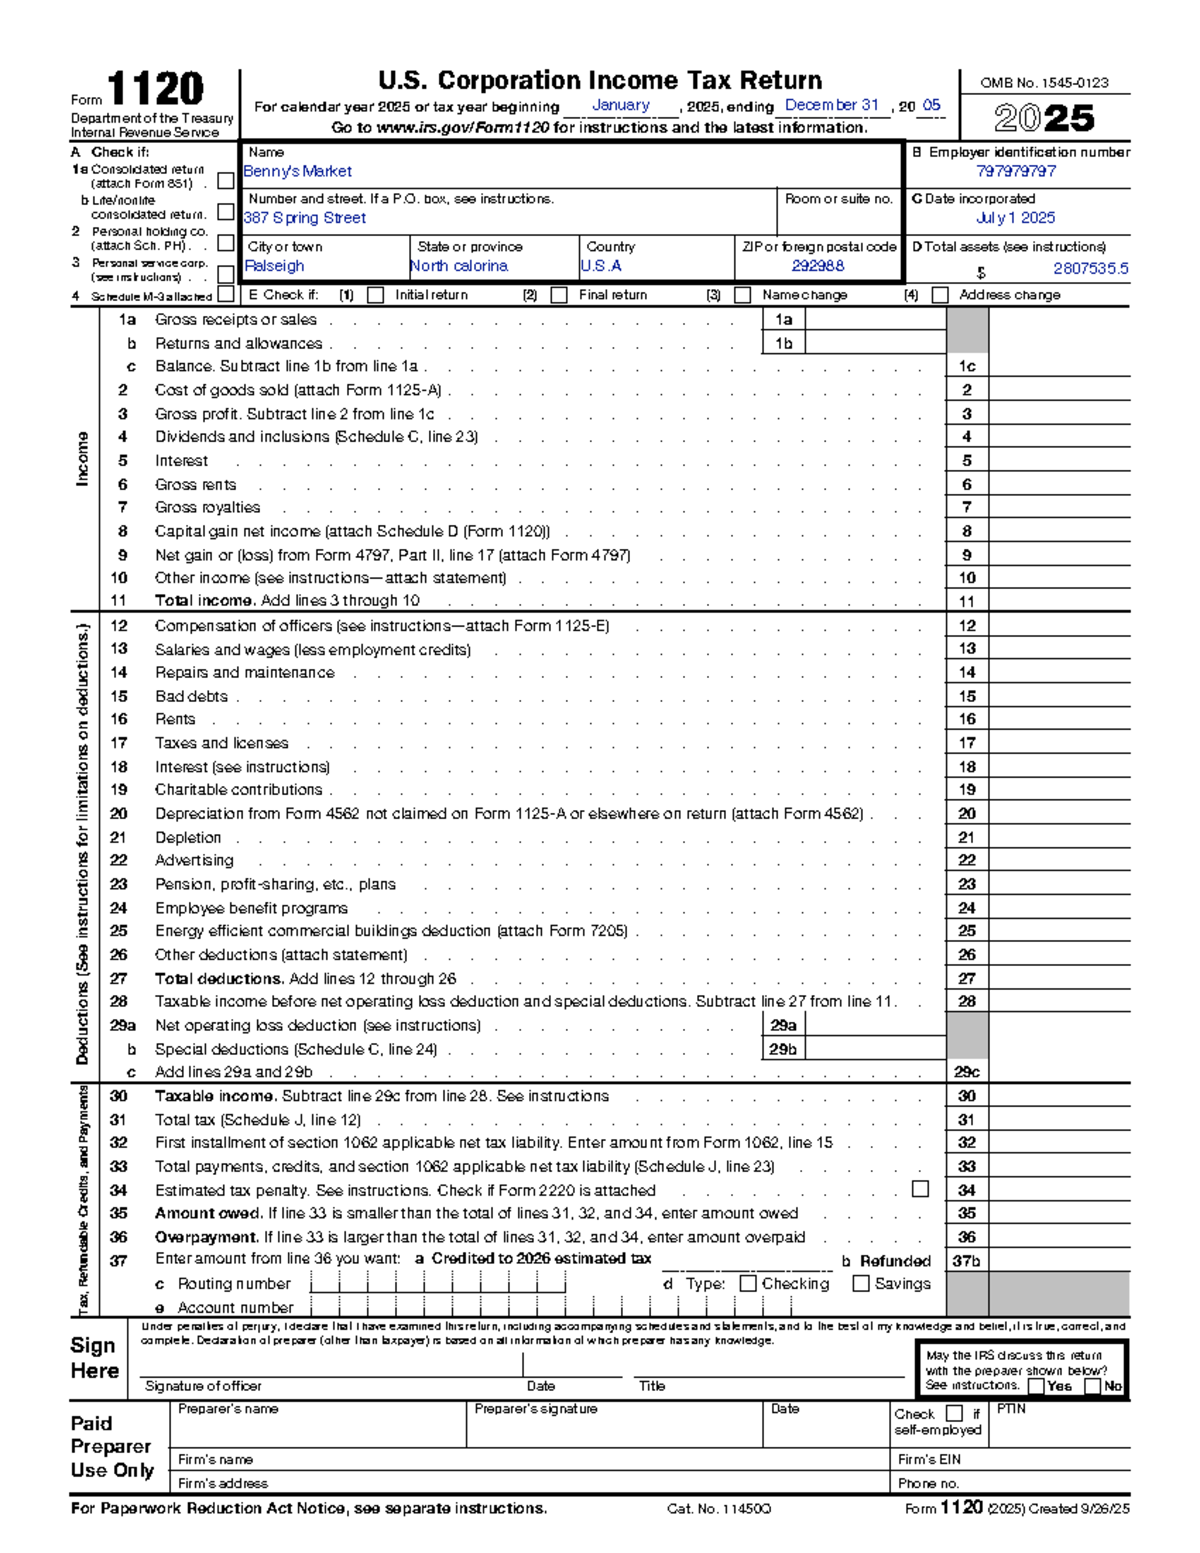
If you run a C corporation in the US, you file Form 1120 by the 15th day of the fourth month after your fiscal year ends — so for a calendar-year corp that's April 15th. Miss it and you're looking at penalties that compound fast. The IRS charges $210 per month or part of a month that a return is late, capped at twelve months. That means one missed deadline on a small business can cost you $2,520 before anyone even files an extension. The form itself is twenty-five pages long, but most of those pages only matter if your situation triggers them. A typical small C corp with straightforward income — sales, cost of goods sold, maybe some interest — fills out Pages 1 through 3 and maybe Schedule K-1 if there are pass-through items from partnerships or S corps they own. Everything after that is conditional. Page 4 gets used when you have depreciation, amortization, or special deductions like the domestic production activities deduction (which some people still look for even though it was replaced by the Section 199A deduction for most filers). Pages 5 through 25 are schedules you attach only when relevant. I spent six years doing corporate tax for mid-market clients and the thing nobody tells you about Form 1120 is that the numbers don't always flow where you expect. Take Schedule M-2, the accumulated earnings and profits reconciliation. You'd think it's just beginning balance plus net income minus distributions equals ending balance. It is, sort of. But if the corporation has preferred stock outstanding or has issued stock in a transaction that wasn't fully taxable, the E&P calculation gets messy fast. I once had a client whose Schedule M-2 didn't tie out because someone in 2019 had converted an S corp back to C corp status, and the S corp had accumulated adjustments not yet taken into account. The IRS notice we got was vague enough that it took us three months of back-and-forth with a technician who had pulled the wrong year's Sch. M-2 from the transcript. The workaround was filing Form 1128 — Application to Adopt, Change, or Retain a Tax Year — retroactively with a letter explaining the re-election, which then allowed us to restate the E&P as of the conversion date.
The Line-by-Line Reality
Line 1 is gross receipts. Line 2 is returns and allowances. Line 3 is cost of goods sold. Line 4 is gross profit. Most people get these right because they're obvious. Where errors show up is on Line 8 — other income. This is where people forget to report foreign currency gain or loss, or they leave off a miscellaneous income item like a lawsuit settlement that isn't tied to physical injury. A $47,000 dispute resolution payout sat unreported on a Schedule 1120 for three years because the CFO thought it was "already taxed at the individual level." It wasn't. The corporation paid the full AMT on it when the statute of limitations was still open, but we had to amend. Line 12 is deductions. This is the schedule where the biggest mistakes happen because people either double-count deductions they already took on Schedule K or they miss entirely separate deductions they're entitled to. The employee health insurance deduction on Line 19, for instance. Many small corps forget this one exists. If your corporation paid 100% of the premiums for employee health insurance, that's deductible even though it's not reported on a W-2 in the same way. It goes straight through to reduce taxable income.
Common Mistakes I See Repeatedly
The most common error is the wrong form entirely. A lot of business owners file Form 1120-S because they have an S election and don't realize the corporate structure itself doesn't change. The S election just shifts the taxation from the corporate level to the shareholders. The form stays 1120-S, yes, but the difference matters enormously for self-employment tax, basis calculations, and distributed gain recognition. If your accountant filed a 1120 for an S corp or vice versa, you're looking at a misclassification that can affect everything from passive activity loss limitations to the built-in gains tax window. Another frequent issue is the book-to-tax reconciliation on Schedule M-1 or M-3. If your corporate books show a net loss but the tax return shows income, or the other way around, the IRS matching program will flag it. Schedule M-1 is the simpler version and it's what most small C corps use. It reconciles book income to taxable income through a handful of adjustments — federal income tax per books, expenses on books not on return, income on return not on books. The trick is that the numbers have to be sourced from your actual financial statements, and a lot of companies that don't prepare formal GAAP financials end up pulling figures from internal management reports that don't match what they'd report on a balance sheet. I learned to ask for the income statement used for bank covenants, not the one the CEO sends to the board.
Get the Full Details
When You Need the Big Schedules
If you're a large corporation — generally defined as more than $250 million in total assets on the last day of the tax year — you have to file Schedule M-3 instead of Schedule M-1. Schedule M-3 is a twenty-three-line beast that breaks the reconciliation into parts for balance sheet items, income statement items, and separate computations. It's designed so the IRS can parse the data in a machine-readable format, and the instructions alone run over a hundred pages. Most smaller companies don't need to worry about this, but if your business has grown past that threshold without anyone noticing, you could be filing the wrong schedule and creating a compliance gap. Schedule J is another one people miss. It's the tax computation schedule and it's where you calculate the actual corporate tax liability using the flat 21% rate (post-TCJA) and then work through any alternative minimum tax or special rates that might apply. Before 2018, the corporate tax rate was graduated — 15%, 25%, 34%, 39% — so older practitioners sometimes still reference those brackets. They don't apply anymore unless you're dealing with a carryback from a pre-2018 year.
The Extension Question
You can get an automatic six-month extension by filing Form 2688 by the original due date. The extension gives you until October 15th for a calendar-year corporation. Important to understand: the extension is for filing, not for payment. If you owe taxes, you should estimate and pay by April 15th or face interest charges starting that day. The IRS charges interest on underpayments at a rate that's set quarterly, currently around 8% annually. For a corporation owing $150,000, that's roughly $10,000 a year in interest if you don't pay by the original deadline. It's cheaper to pay what you owe and file the extension than to wait and get hit with both penalty and interest. Form 1120 goes through an automated review process. The IRS computer checks for mathematical errors, mismatched Social Security numbers on W-2s referenced in the return, and consistency between the total income reported and what third-party forms show. If something doesn't add up, you'll get a notice — usually CP 2000 — proposing changes. These aren't audits in the traditional sense. They're automated discrepancies with an appeals process. Most corporations I worked with resolved them within 90 days by sending the supporting documentation the IRS requested. The key is responding quickly. If you ignore a CP 2000 notice, it becomes a final determination and you lose your right to appeal in Tax Court. Retaining the right paperwork matters more than most people think. The statute of limitations for a corporation is generally three years from the filing date, or two years from the date you paid the tax, whichever is later. If you underreported income by more than 25%, the period extends to six years. Keeping records for seven years isn't overkill — it's exactly what you need to survive the longest possible assessment window. I keep corporate tax workpapers for ten years because the statute can be suspended if the IRS issues a jeopardy assessment, and those occasionally surface years later when a taxpayer leaves the country or the responsible officer dies.