What Healthy Benefits Plus Actually Is
Healthy Benefits Plus is a health wallet card program most people encounter through their employer's benefits portal. It links to your pre-tax dollars from an HSA, FSA, HRA, or wellness reimbursement account. When you shop at a qualified medical provider or retailer, the card pulls from those funds directly instead of paying out of pocket and filing a claim yourself later. Most people think it works exactly like a regular debit card. It does not, which is where things get messy.
How To Use Unveiling The Power Of Healthy Benefits Plus Com Hwp Card Unlocking A Healthier You
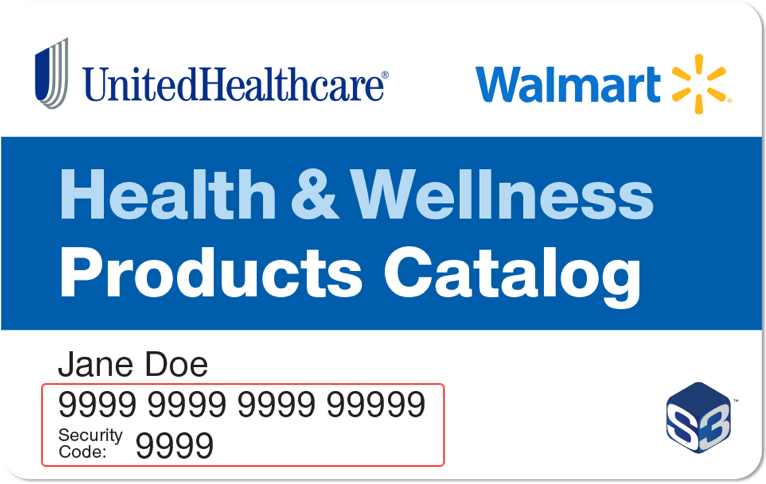
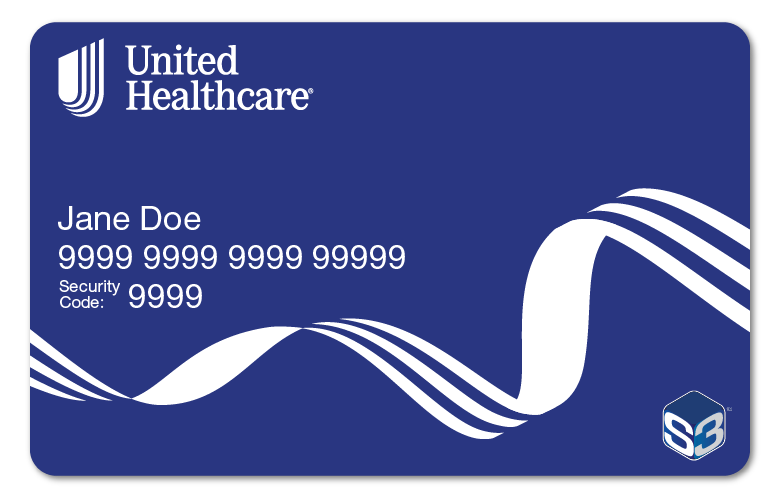
First you need to activate it. After your employer enrolls you, you will get a card in the mail along with instructions, or sometimes you just register online at healthybenefitsplus.com. Enter the card number, set up a PIN, and download the mobile app. The app is where most of your actual management happens. From there you can check balances, see transaction history, and sometimes even upload receipts for reimbursement claims. Using the card is straightforward at the point of sale. Swipe or tap it like any payment card. The system checks whether the merchant category code qualifies for your particular account type and either approves or declines the charge in real time. That automatic MCC check is the main reason people get confused when transactions get rejected at places that seem obviously medical.
Where People Go Wrong
The biggest issue I see is people assuming every health-related purchase goes through the card automatically. Dental offices, vision centers, and pharmacies usually work fine. But if you go to an optometrist who also sells sunglasses at the front counter, the POS system might flag the entire transaction as non-qualified because the merchant code is for a general retail store. The card gets declined and you have to pay cash, then submit a manual claim in the app afterward. It takes about ten to fifteen minutes in the app but most people never figure out how to do it. Another thing nobody tells you: the card balance does not always update immediately. I had a claim where a $200 co-pay was approved on Tuesday, but the updated balance did not show up until Thursday morning. If you are trying to use the remaining funds and the app shows zero, check your bank statement instead of assuming the money is gone. There is usually a one to two business day lag between the provider settlement and the app display.
Get the Full Details

Advanced Details Most Guides Skip
Your HWP card is tied to a specific account type and each one has different eligibility rules. An HSA card will approve prescriptions and medical devices but may reject over-the-counter items unless they qualify under current IRS rules. An FSA card from your employer might have its own additional restrictions beyond what the IRS allows. Some employers set up custom vendor whitelists that only work at certain pharmacies or clinics. This means the card could work at Walgreens one month and stop working the next if your plan administrator changed networks. There is also a subtlety around dependent coverage. If your plan covers your spouse and children, their eligible expenses should run through the same card. But if a family member runs up the balance on non-qualified purchases, it still deducts from your account. I learned this the hard way when my wife bought prenatal vitamins at a grocery store that did not have a pharmacy MCC attached. The charge went through, came out of our FSA funds, and then got flagged during our year-end reconciliation. I had to submit documentation proving the vitamins were not prescribed to reverse the transaction. It took three weeks and two email exchanges with support.
When The Card Will Not Work For You
Healthy Benefits Plus is useful but it is not universal. It does not cover cosmetic procedures, gym memberships (unless your employer has a specific wellness incentive program attached), or most mental health services outside of clinical therapy. If you are using an HRA that requires manual receipt submission anyway, the card might not add much value compared to just paying normally and getting reimbursed on a schedule. In those cases the app becomes just another thing to manage without the point-of-sale convenience. If your employer uses a different benefits platform alongside HWP, you might end up juggling two cards and two apps. I have seen this happen with employers who layer an HSA with a separate dental and vision card program. The overlap in login portals and conflicting balance displays makes it easy to double-spend or misattribute charges.
Practical Steps to Get Started
Log into healthybenefitsplus.com and register your card. Download the mobile app from your device's official store. Verify your identity using the email or phone number linked to your employer's benefits system. Check your balance and review which transactions are pre-approved versus which require manual receipts. Set up notification alerts so you know immediately when a charge posts. Keep your tax documents organized throughout the year, not at April time, because the year-end 1095-D or equivalent statement from HWP needs to match your actual qualified spending. The card itself arrives by standard mail within seven to ten business days after activation. If you need expedited delivery for a planned medical expense, call the number on the back of the card and ask. Some administrators offer overnight shipping if you explain the situation, though it is not guaranteed.