What Capital Adequacy Ratio Actually Measures
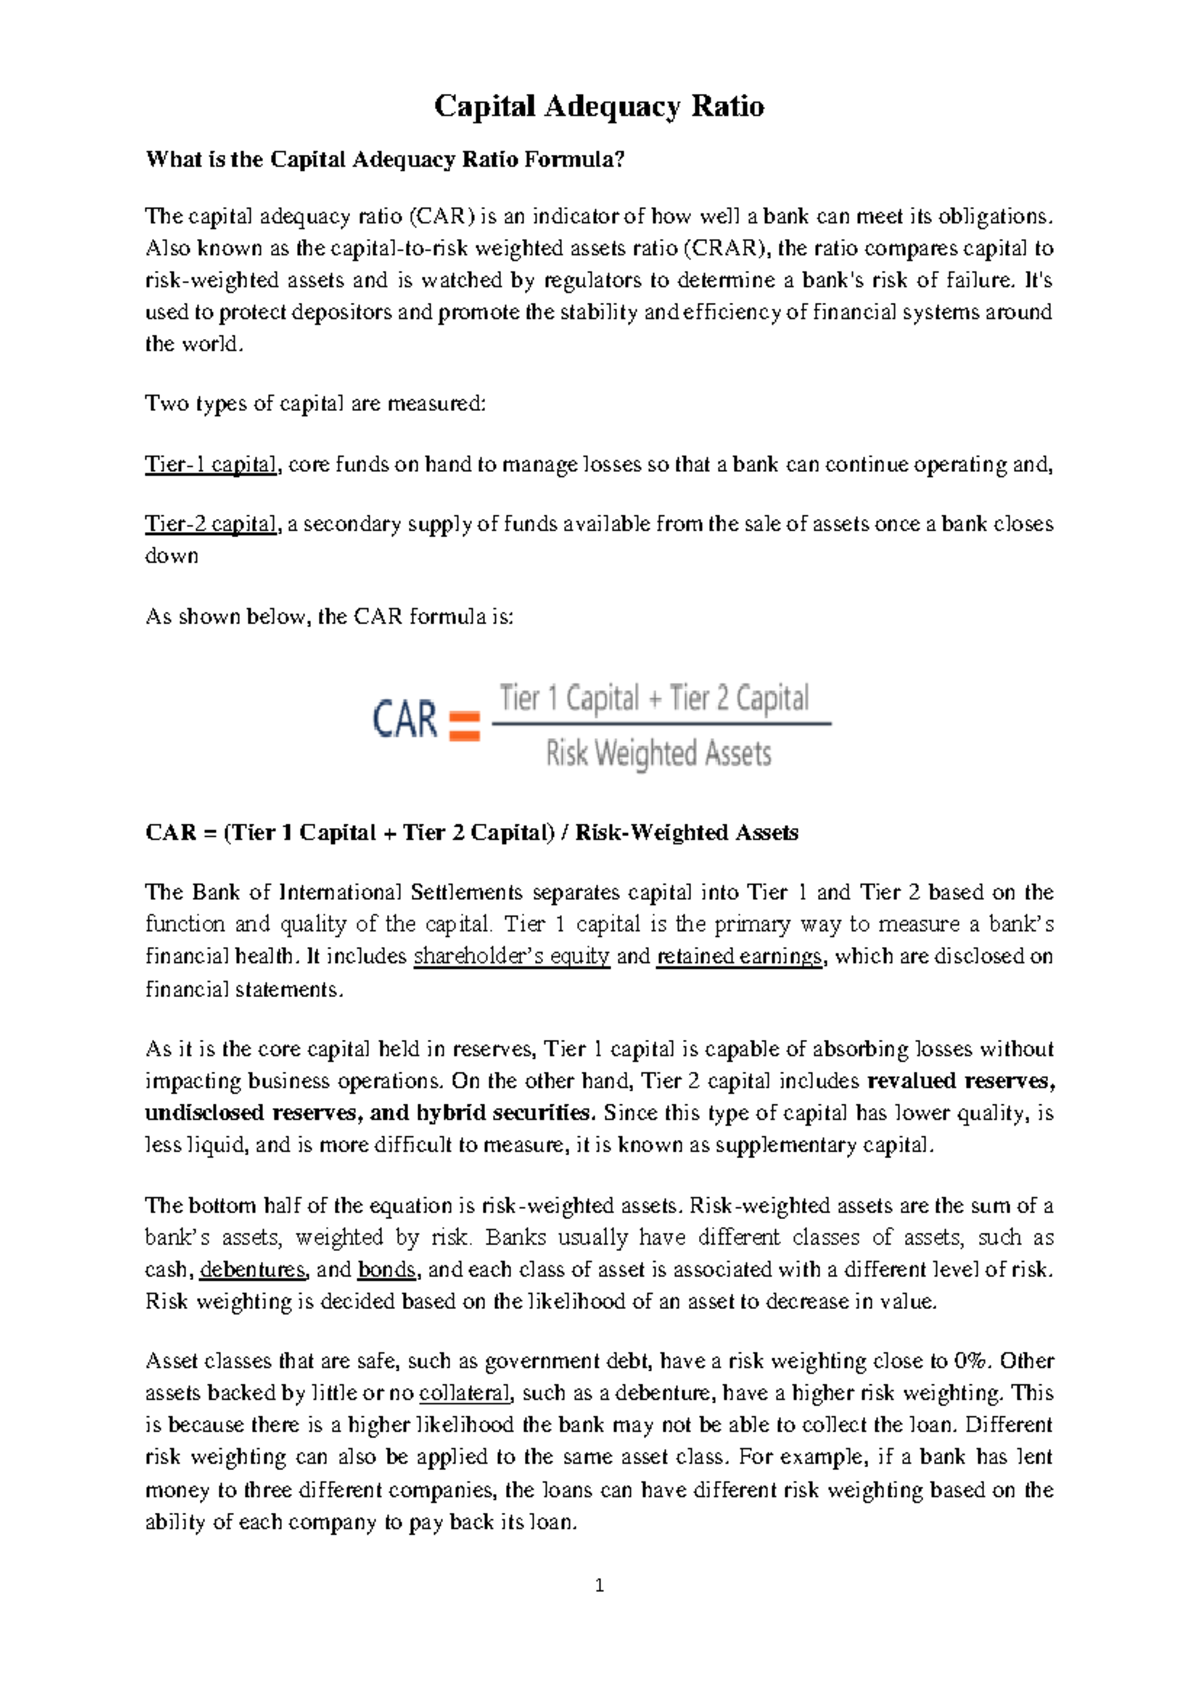
Most people treat CAR as a simple compliance checkbox. It is not. It is a measure of whether a bank has enough high-quality capital to absorb losses before it becomes insolvent. The Basel framework defines it, but regulators enforce it differently depending on where you are sitting. The core formula stays consistent: tier 1 capital plus tier 2 capital, divided by risk-weighted assets. What changes is how each component gets defined and calculated. I spent three years working in a bank's capital planning group, and the first thing I learned was that the textbook definition and the actual regulatory submission are rarely the same document. Regulators require deductions, transitional arrangements, and granular qualifying criteria that the textbook skips entirely. A common mistake beginners make is assuming all equity counts equally. It does not. Common equity tier 1 is the highest quality. Additional tier 1 instruments, like certain perpetual preferred shares, carry limitations. Tier 2 is hybrid debt that absorbs losses only in a resolution scenario. Mixing these tiers up will ruin your capital calculation.
Unveiling The Power Of Capital Adequacy Ratio Understanding Car Definition And Function
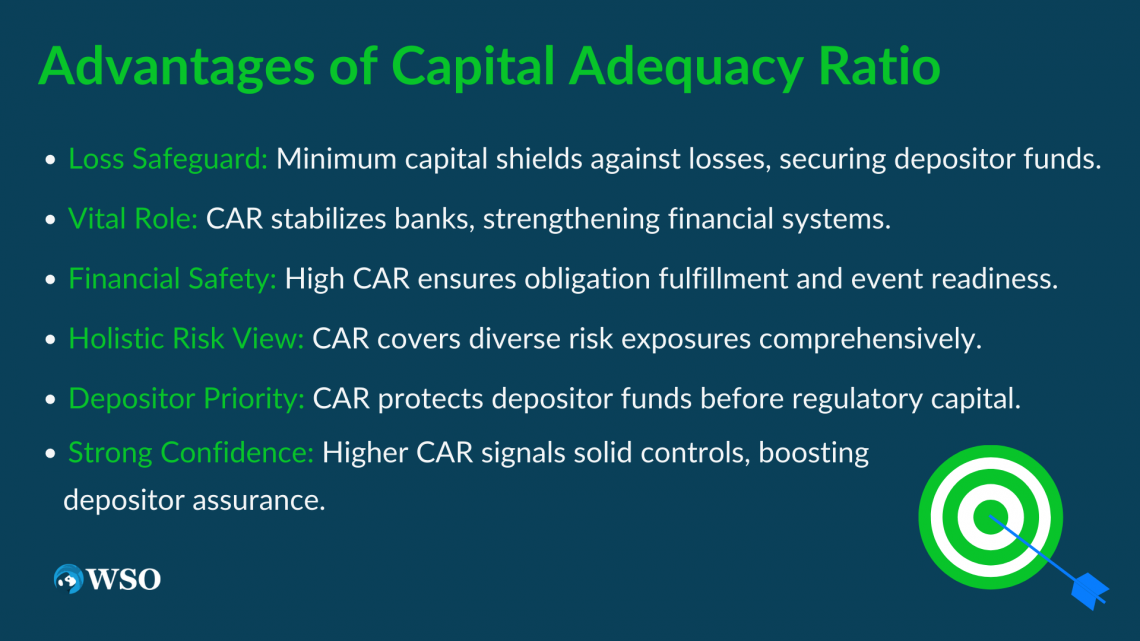
The function of CAR is straightforward in theory: ensure banks hold enough cushion to survive stress. In practice, it governs lending capacity, dividend policy, and strategic decision-making at every level. A bank with a CAR of 14 percent has significantly more room to grow its balance sheet than a bank sitting at the regulatory minimum of around 8 to 10.5 percent once you factor in the conservation buffer. That difference is not theoretical. It determines whether a bank can fund a new loan book or whether it must sell assets to stay compliant. Here is how the calculation works step by step. First, determine your qualifying capital. Start with common equity tier 1. This includes retained earnings, share capital, and accumulated other comprehensive income, minus deductions for goodwill, intangible assets, and deferred tax assets that depend on future profits. Then add additional tier 1 capital, which is limited and strictly regulated. Finally, add tier 2 capital, which includes eligible subordinated debt and allowance for credit losses up to a capped percentage. Subtract any disallowed items from the combined total. That gives you total qualifying capital.
Second, calculate risk-weighted assets. You do not simply sum the balance sheet. Each asset class carries a different risk weight. Cash and government bonds typically carry zero or minimal weight. Residential mortgages sit around 35 to 50 percent depending on the jurisdiction. Corporate loans are usually 100 percent. Equity positions in other companies can range from 100 to 1250 percent under the standardized approach. Credit derivatives and off-balance sheet exposures require conversion through credit conversion factors before risk weighting. The complexity comes from derivatives, securitizations, and counterparty credit risk, which use additional formulas like the current exposure method. Third, divide qualifying capital by risk-weighted assets. Multiply by 100 to express it as a percentage. Compare that percentage against your regulatory minimum plus any buffers applicable to your institution. If you fall below, you face restrictions on capital distributions and potentially corrective action plans.
Get the Full Details

The Practical Problems No Textbook Covers
I remember a specific case where our bank was close to breaching the minimum requirement after a quarter-end shift in asset classifications. We had originated a batch of commercial real estate loans that fell into a higher risk-weight category under the updated standard. The immediate impact was a sudden increase in risk-weighted assets without any change to our capital base. That compressed our CAR by roughly 60 basis points in a single reporting period. We had about ten business days before the next regulatory filing deadline to address it. The workaround was not elegant. We accelerated paydowns on lower-returning corporate loans, shifted some portfolio risk through credit-linked notes, and deferred a proposed dividend. It took about two days of intense coordination between treasury, risk, and finance to model the impact and execute. The process ate approximately 15 hours of senior staff time across three departments. That is the reality of capital management: it is not an annual exercise. It is a continuous pressure test against a moving target. Another counter-intuitive insight that took me a long time to internalize is that increasing CAR is not always the right move. Holding excessive capital has a real cost. It depresses return on equity and signals to the market that the bank lacks profitable lending opportunities. Regulators do not reward banks for holding five percentage points above requirements. The optimal position is usually to operate a few percentage points above the minimum, maintaining a buffer that accounts for earnings volatility and growth plans without dragging down profitability metrics that investors scrutinize.
A pitfall I see repeatedly is the treatment of internal ratings-based models. Banks that use the IRB approach for credit risk can achieve significantly lower risk-weighted assets than those using the standardized approach, sometimes reducing RWA by 15 to 25 percent for the same portfolio. This is legitimate under Basel rules, but it introduces estimation risk. If your internal models are overly optimistic about loss given default or probability of default, your CAR looks healthy while the underlying risk profile is worse than it appears. Regulators apply a floor to IRB-calculated capital requirements precisely because of this. Do not assume your model output is the final word. Always run a standardized-approach cross-check. Off-balance sheet exposures are another area where the math gets obscured. Contingent commitments, letter of credits, and synthetic securitizations all feed into RWA through credit conversion factors and risk weights. A €500 million undrawn corporate credit facility might convert to only €250 million in credit equivalent amount and then receive a 100 percent risk weight, adding €250 million to RWA. These items are easy to overlook when you are focused on the balance sheet, but they carry real capital cost.
Limitations You Need to Accept
Capital adequacy ratio is a point-in-time snapshot. It does not capture liquidity risk. A bank can maintain a comfortable CAR while experiencing a severe funding squeeze, as happened during the 2008 financial crisis and again in 2023 with regional banks in the United States. CAR and the liquidity coverage ratio measure different things, and neither alone is sufficient. Relying on CAR as a standalone health indicator is a mistake that has cost institutions their independence. The ratio also struggles with concentration risk. A bank can have a healthy overall CAR while holding a massive single-name exposure that threatens its viability if that counterparty defaults. Supplementary leverage ratios and large exposure limits address this, but they are separate metrics. CAR alone will not warn you about a concentration that could wipe out a meaningful chunk of your capital in one event. For smaller regional banks or credit unions, the full Basel III standardised framework can be overkill. Some jurisdictions offer simplified approaches that reduce computational burden while maintaining adequate oversight. If your institution falls below certain asset thresholds, investigate whether a proportionality framework applies. It can cut your capital calculation time substantially without sacrificing regulatory compliance. I worked with a community bank that reduced its quarterly CAR preparation from about 40 hours to roughly 8 hours by qualifying for and correctly applying a simplified standardised approach available under local rules.

How to Maintain a Manageable CAR Going Forward
The most effective approach is to integrate capital planning into the strategic decision-making process rather than treating it as a post-hoc compliance exercise. When a new product launches, a significant acquisition is planned, or a major lending initiative begins, run the capital impact analysis before approval. Model the RWA addition, estimate the effect on tier 1 capital through profit retention, and determine whether the resulting CAR remains within your target range. Doing this upfront prevents emergency capital-raising or loan sales under duress. Track your key capital drivers monthly. Core tier 1 ratio, leverage ratio, and risk-weighted asset density should all be monitored on a rolling basis. Use variance analysis to identify which business lines or asset categories are driving movement. This usually takes about 6 to 10 hours per month for a mid-size institution, but it provides early warning of trajectory issues that annual reporting will miss. When preparing your regulatory submission, maintain a detailed reconciliation from GAAP or IFRS equity to qualifying capital. Regulators routinely request this. Having it ready prevents delays and reduces the chance of errors that trigger qualification comments. A proper reconciliation typically requires 2 to 3 days of work for a standard banking organization, but building the template and process upfront reduces repeated effort significantly.
Finally, understand that CAR optimization is a balancing act. Every decision to grow assets, issue capital, pay dividends, or retain earnings shifts the ratio. There is no permanent optimal setting. The goal is to operate within a range that satisfies regulators, supports your business strategy, and maintains market confidence. Anything beyond that is noise.