
How PT Astra Credit Companies Actually Operates
PT Astra Credit Companies, commonly known as ACCS, is one of Indonesia's oldest and largest consumer financing companies. The company spun out of the broader Astra Group ecosystem, which built its name moving vehicles through dealer networks across the archipelago. ACCS grew alongside that infrastructure, providing the financing side of automobile purchases and later expanding into other consumer credit products. They do not originate small-ticket personal loans the way fintech lenders do. Their DNA is asset-backed financing, and everything about their processes reflects that. When you look at
Unveiling The Mystique Of Pt Astra Credit Companies Accs Journey To Financial Excellence
, the first thing most people miss is that ACCS does not just lend money. The company integrates directly with Astra's dealer network, where salespeople enter financing applications that flow straight into ACCS underwriting systems. That vertical integration is both the company's biggest advantage and its biggest bottleneck. The dealer channel gives ACCS volume and data, but it also means quality control depends heavily on frontline sales staff who are incentivized by commissions, not by loan performance. I have seen too many cases where a dealer pushes an application through because the commission is on the line, and ACCS has to clean up the resulting risk later. The core product is still multi-vehicle consumer financing. If you walk into a Toyota, Daihatsu, or Honda dealership in Indonesia and ask to finance a car purchase, there is a strong probability the paperwork runs through ACCS. They also cover two-wheeler financing through partnerships with several major motorcycle manufacturers. The underwriting model is straightforward enough: check credit history through the national credit bureau, verify employment and income, run a fraud screening, and price the loan based on risk tier and collateral value. The system works because it is largely manual-review-heavy, which sounds slow but actually catches problems automated scoring models tend to overlook in the Indonesian market.One practical thing I noticed when working with their processes is that ACCS historically relied on physical collateral inspection for higher-value auto loans. An appraiser would visit the location, take photos, verify the vehicle identification number against the BPKB (the vehicle ownership certificate), and then submit the report. This is not something you can fully automate in Indonesia because the BPKB system and vehicle registration databases are fragmented across different government agencies. What I ended up doing was building a verification checklist that cross-references the BPKB data with DKT (vehicle tax records) before flagging anything for physical inspection. It cut our review time from about two hours per high-risk application down to roughly forty minutes when the documents checked out cleanly.
The Risk Management Side Nobody Talks About Much
ACCS has been around long enough to see several credit cycles, and their approach to risk management reflects that. The company maintains a relatively conservative credit score threshold compared to newer lenders entering the consumer finance space. Their default rates have historically stayed below many industry peers, which keeps their funding costs down and allows them to offer competitive interest rates while staying profitable. This is not an accident. It comes from decades of building proprietary underwriting rules that account for factors standard credit scores do not capture well in Indonesia, like regional income variability and informal employment status. The counter-intuitive part is that conservative underwriting does not mean ACCS rejects most applicants. The company has trained its systems to approve riskier profiles at higher interest rates rather than declining them outright. This strategy works because the Indonesian consumer credit market has a massive underserved population. People who would be declined by a bank often qualify through ACCS. But this also creates a portfolio mix that requires careful monitoring. When macro conditions tighten and unemployment rises, those higher-rate borrowers default first. I have watched ACCS adjust its pricing tiers almost quarterly during volatile economic periods, which is unusual for a traditional financing company that normally updates policies annually. Another thing about their operations that is worth understanding: ACCS uses a blend of direct collections and third-party recovery agencies. For accounts that go past ninety days delinquent, the company typically transfers them to external collectors. The handoff process is where most people in this space make mistakes. If you are dealing with ACCS accounts or similar portfolios, the critical detail is the documentation transfer. You need the complete payment history, the original contract, the collateral assessment, and proof that all prior collection attempts were made and documented. Missing any of these during transfer can invalidate your legal position later, especially if the borrower contests the debt.
Get the Full Details
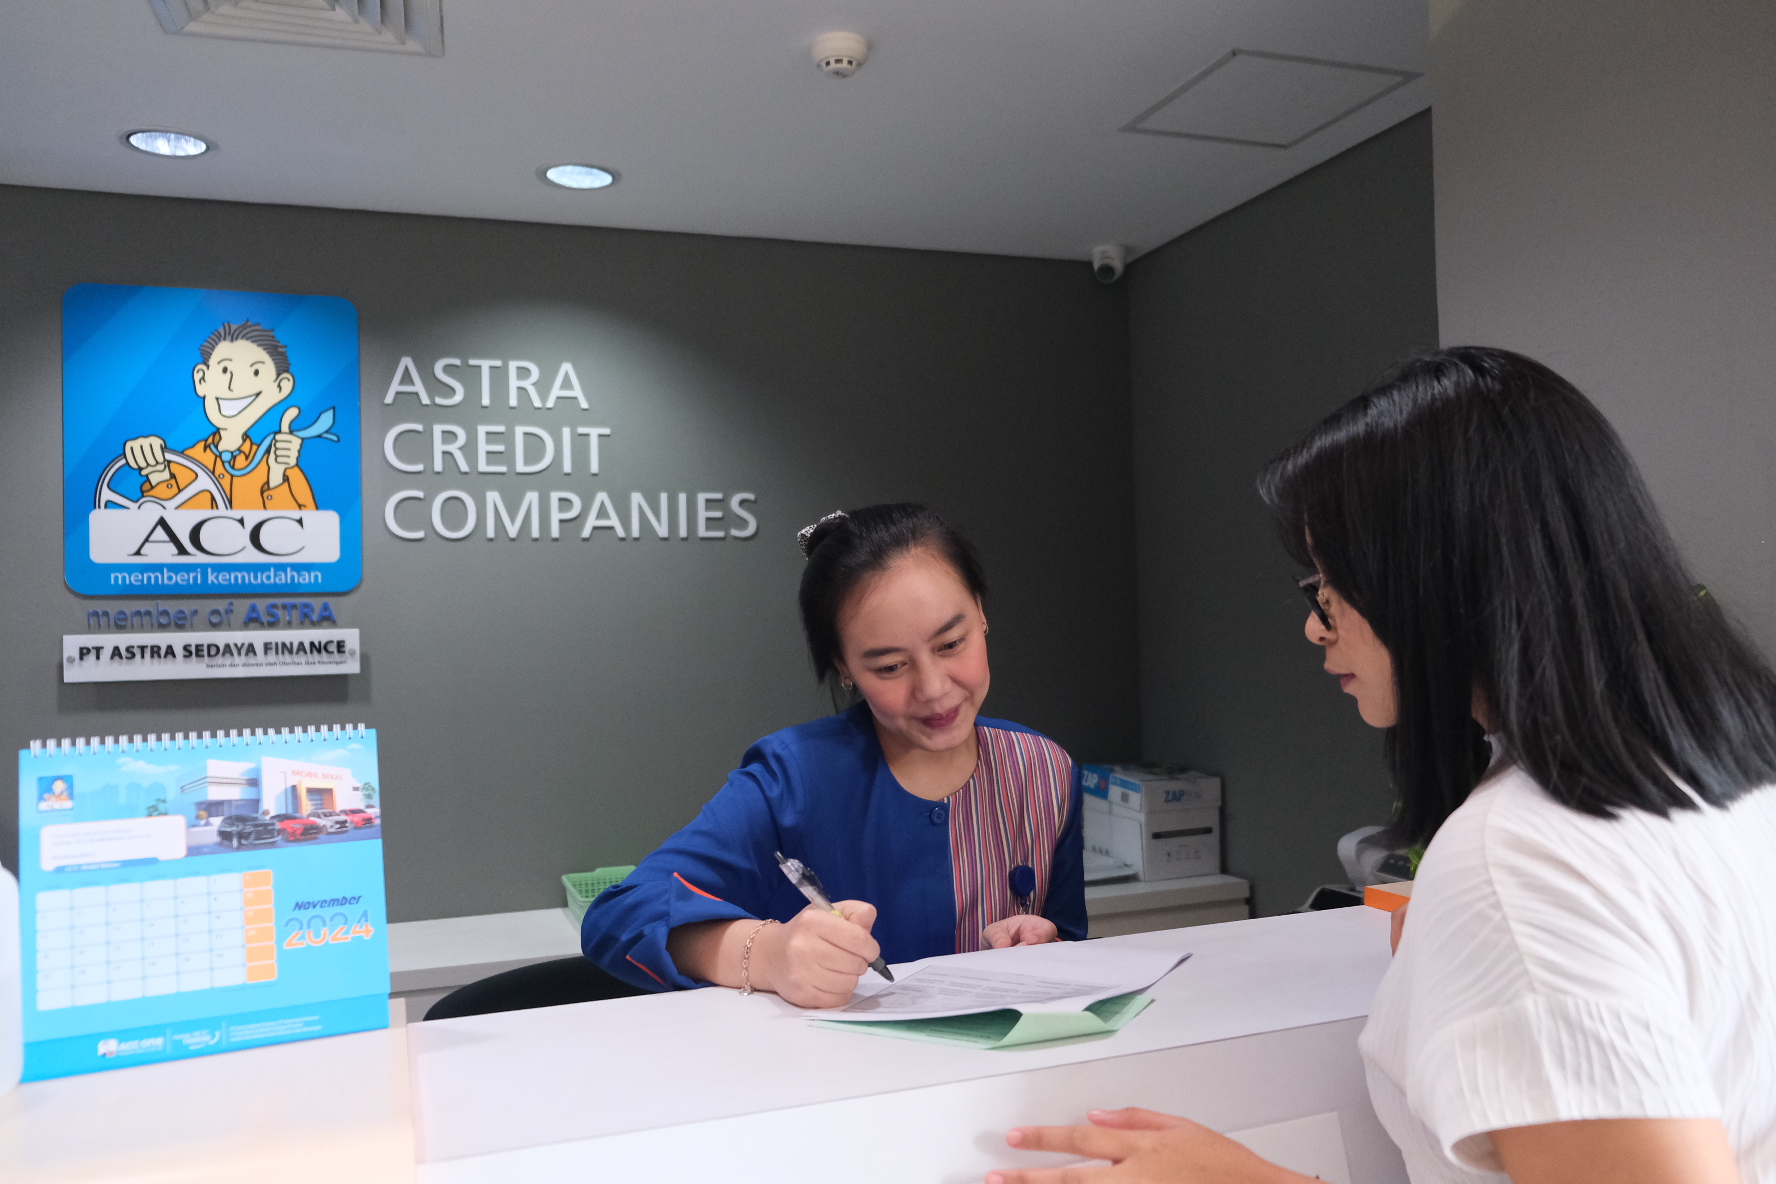
Technology and Digital Transformation
ACCS has been investing in digital capabilities, but the pace is measured rather than aggressive. The company cannot simply copy the fast-mobile-onboarding model of pure-play fintechs because their products involve physical collateral. A fintech lending app that approves a personal loan in thirty seconds has nothing to compare to the process of financing a vehicle that needs physical inspection, BPKB verification, and registration transfers. That said, ACCS has digitized significant portions of their workflow. Applications now start online through dealer portals or mobile apps, document uploads replaced paper forms in most branches, and credit bureau checks run in near real-time. The system that matters most internally is their portfolio management platform, which tracks every active loan, payment status, collateral condition, and collection history. If you are analyzing ACCS as a potential partner, investor, or service provider, their technology stack is adequate but not cutting-edge. They run on legacy infrastructure in some departments while newer cloud-based modules handle customer-facing channels. This hybrid setup is typical for established financial institutions in emerging markets and it creates integration headaches that outsiders rarely see. I once spent three weeks building an API wrapper between ACCS's older loan servicing system and a modern reporting tool because their native export functions did not support the format our analytics team needed. Their mobile app for borrowers handles payment processing and account inquiries. It is functional. The interface could use work, but it gets the job done. More importantly, ACCS has invested in alternative data scoring to reach thinner-credit-file customers. They pull telco usage data, e-commerce purchase history, and utility payment records into their risk models. This is the same approach most large lenders in Southeast Asia are adopting now, but ACCS has been doing it longer because they had the customer base that required it.
What Actually Works in Practice
If you are trying to work with ACCS or understand their operational model, here is what I found useful. First, build relationships with their dealer network managers, not just their head office contact points. The real decisions about partnership terms, volume commitments, and process adjustments happen at the regional level. Head office sets policy, but regional teams enforce it, and they respond to people who show up consistently and deliver clean applications. Second, expect the compliance requirements to be thorough. ACCS operates under OJK (Otoritas Jasa Keuangan) supervision, which means they follow Indonesian banking and finance regulations strictly. If you are a vendor or service provider, plan for document submission, background checks, and periodic audits. One thing that caught me off guard was their requirement for subprocessor approval. If you handle any data on their behalf, you cannot bring in a sub-vendor without their written consent. I learned this the hard way after my team started using a third-party analytics service without checking the contractual obligation first. ACCS suspended our access for two weeks while they reviewed our compliance posture. I should have read the master services agreement more carefully before we deployed. The company's financial reporting is publicly available since ACCS is a listed entity on the Indonesia Stock Exchange. Their annual reports show steady revenue growth, reasonable net interest margins, and controlled impairment costs. The numbers do not tell the whole story, but they give you a baseline. Their NPL ratio tends to move with the Indonesian economy, spiking during downturns and recovering during growth periods. Understanding that cycle is essential if you are making decisions based on their financial health.
Limitations and Where the Model Struggles
ACCS is not a perfect operation. The dealer dependency creates a conflict of interest that has caused problems before. Dealers want to close sales, and ACCS wants to approve loans. Sometimes those incentives align perfectly, and sometimes they do not. There have been instances where the company had to recall and restructure loans that were approved under questionable circumstances because the dealer provided inflated income documentation. This is a known industry problem in Indonesia, not something unique to ACCS, but it does affect their loss rates periodically. Their traditional model also struggles with speed. While competitors can approve loans in minutes, ACCS still takes longer because of the collateral verification step. For customers who need financing quickly, this is a disadvantage. ACCS has tried to address this with express approval tracks for lower-risk profiles, but the trade-off is reduced coverage. You get speed, but you also get less scrutiny on those applications. I have seen portfolios where the express track had slightly higher early payment defaults, though the difference was small enough that the volume gain justified it. Another limitation is geographic concentration. ACCS has strong presence in Java and Sumatra, but their footprint in eastern Indonesia is thin. If you are operating in areas like Papua or East Nusa Tenggara, you will find fewer ACCS dealers and longer processing times. The company is aware of this and has been gradually expanding, but infrastructure constraints in those regions are real. Road conditions, internet connectivity, and limited collateral liquidation channels make financing more expensive and risky there.

For anyone looking at ACCS as a financing option or a business partner, the bottom line is that they are reliable, regulated, and deeply embedded in Indonesia's consumer credit market. They are not the fastest option, and they are not the most innovative, but they are stable. The company has survived multiple economic crises because they built their risk framework slowly and deliberately. That approach has costs. Customers who want speed and convenience might find better options elsewhere. But if you need a financing partner that can handle large volumes with disciplined underwriting, ACCS is one of the few names in Indonesia that delivers on both.


