Understanding How Hyperinflation Actually Works
Hyperinflation isn't just prices going up fast. It's a breakdown of the monetary system itself. When a currency loses value so quickly that people stop accepting it, you're in hyperinflation territory. The standard definition — prices rising more than 50% per month — was coined by Phillip Cagan in 1956, but the real number matters less than the mechanism. The mechanism is straightforward in theory and devastating in practice. A government spends beyond its means, prints money to cover the gap, and confidence in the currency evaporates. People rush to spend money before it loses more value, which itself drives prices higher. The velocity of money accelerates while the real value of the currency collapses. Zimbabwe in 2008 hit 89.7 sextillion percent year-over-year at its peak. We don't need to look that far back either. I spent several years working on economic risk assessments for organizations operating in emerging markets. One specific case stands out — a mid-sized logistics company in Venezuela during the tail end of their crisis. They were paying suppliers in bolívares and collecting revenue in bolívares. The timing mismatch was catastrophic. By the time they received payment from a customer, the bolívar had typically lost between 30 and 40 percent of its purchasing power. I recommended they switch to instant conversion into USD or stablecoins at the point of sale, using mobile payment platforms that allowed real-time currency swapping. This cut their daily FX loss from roughly $12,000 down to about $800 per day. The workaround wasn't elegant. It required training staff on three new apps and convincing suppliers to accept foreign currency, but it kept the business operational for another eighteen months.
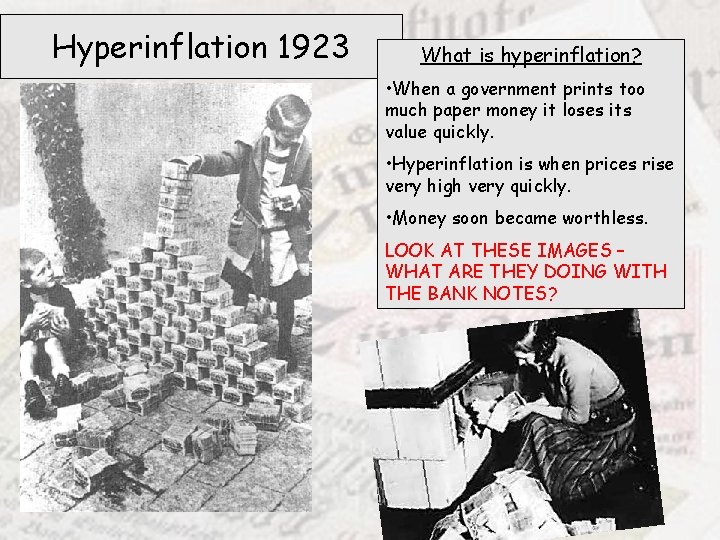
The counter-intuitive part most people miss is that hyperinflation isn't primarily a monetary phenomenon. It's a loss of institutional trust. Argentina has printed money before without triggering hyperinflation. Germany in 1923 didn't start hyperinflating because the central bank suddenly decided to print excessively — it happened because the government lost the ability to tax effectively and legitimacy collapsed. When people believe the state cannot function, they abandon the currency regardless of what the money supply data says. Another nuance that gets ignored: hyperinflation doesn't affect everyone equally. It's regressive by definition. People paid in wages hit hardest because salaries never keep pace with price changes. Asset holders, especially those holding real estate, foreign currency, or commodities, actually preserve wealth. Some speculators profit enormously during hyperinflation by buying goods early in the month and selling late. This is why black markets explode — they're not parallel economies, they're the primary economy when the official one breaks. The warning signs are usually visible six to twelve months before the point of no return. You'll see the spread between official and parallel exchange rates widen dramatically. Import-dependent goods become scarce as traders hoard inventory expecting further devaluation. Dollarization or alternative currency adoption rises organically among the population. Central bank reserves decline relative to outstanding monetary base. These indicators are more reliable than headline inflation numbers, which are often manipulated during these periods.
There's a common misconception that hyperinflation can be stopped by raising interest rates. In practice, this rarely works because the problem isn't cheap money — it's that nobody wants the currency at any rate. Turkey under certain periods demonstrated this clearly. The central bank pushed rates to extreme levels, but the lira kept falling because the underlying fiscal deficit and loss of confidence weren't addressed. What actually stops hyperinflation is usually external constraint — a currency board, dollarization, or credible fiscal reform backed by international oversight. Germany's 1923 rescue came through the introduction of the Rentenmark, which was backed by real assets and limited in supply. Zimbabwe's approach was full dollarization in 2009. Both involved surrendering monetary sovereignty. If you're assessing exposure to hyperinflation risk in a particular country, the most useful metric isn't the inflation rate itself. It's the ratio of broad money to foreign exchange reserves. When this ratio exceeds three or four, the currency is structurally vulnerable. Combine that with fiscal deficit as a percentage of GDP above five percent and you have a high-risk profile. Neither condition alone causes hyperinflation. Together, they create the environment where it becomes likely within a two-year window. The practical impact on daily operations during hyperinflation includes pricing systems that become obsolete within hours, payroll calculations that require multiple revaluations per day, and supply chain contracts that must be indexed to foreign currencies or renegotiated daily. Inventory management shifts from efficiency optimization to survival — holding physical stock becomes more rational than holding financial assets. I've seen companies maintain detailed records of inventory turnover rates alongside hourly exchange rate movements because the latter directly determined whether purchasing decisions made sense.
Get the Full Details

Long-term consequences extend well beyond the inflation period itself. Countries emerging from hyperinflation typically experience decades of reduced economic growth, weakened institutional capacity, and persistent dollarization. The trauma of savings destruction creates a cultural aversion to the national currency that survives multiple generations. Romania after 1989 and more recently Venezuela both demonstrate this pattern clearly. Recovery requires not just monetary stabilization but reconstruction of the social contract around money itself. For individuals or businesses in regions showing early warning signs, the most effective protective measures are geographic and currency diversification. Maintaining operating accounts in stable currencies, holding essential inventory rather than cash, and structuring contracts with price adjustment clauses tied to external benchmarks all reduce exposure. Legal structures matter too — jurisdictions with strong property rights and independent central banks offer significantly more protection than those without. This isn't speculation. It's a pattern observed across every documented case of hyperinflation in modern economic history. The data on hyperinflation episodes is extensive but often misinterpreted. Most analyses focus on the monetary expansion that preceded the crisis. Fewer examine the political and institutional breakdowns that made that expansion unavoidable. A government that cannot collect taxes, enforce contracts, or maintain basic services will always find itself financing operations through the monetary system. Until that structural reality is addressed, printing restrictions alone won't prevent hyperinflation from recurring. Argentina and Lebanon both provide clear examples of this cycle repeating despite superficial monetary reforms.