What Actually Happens When You Open General Ledger Software
The moment someone opens their first accounting package, they stare at a blank chart of accounts and suddenly realize they have to name every possible thing money can do. That is the actual entry point. There is no dramatic reveal. It is just a spreadsheet with more rows than you expected. I learned this the hard way in 2014 when a mid-size manufacturing client asked me to clean up their books before a bank review. Their chart of accounts contained 412 lines, half of which were duplicates created over six years by three different bookkeepers who never talked to each other. Account 6010 was "Office Supplies." Account 6011 was also "Office Supplies" but under a different cost center. Account 6200 was "Miscellaneous Expenses" and held roughly forty thousand dollars in unrecognized items. The bank asked for detail and we had nothing to give.
Unveiling The Mysteries Of Accounting Accounts A Clear Definition
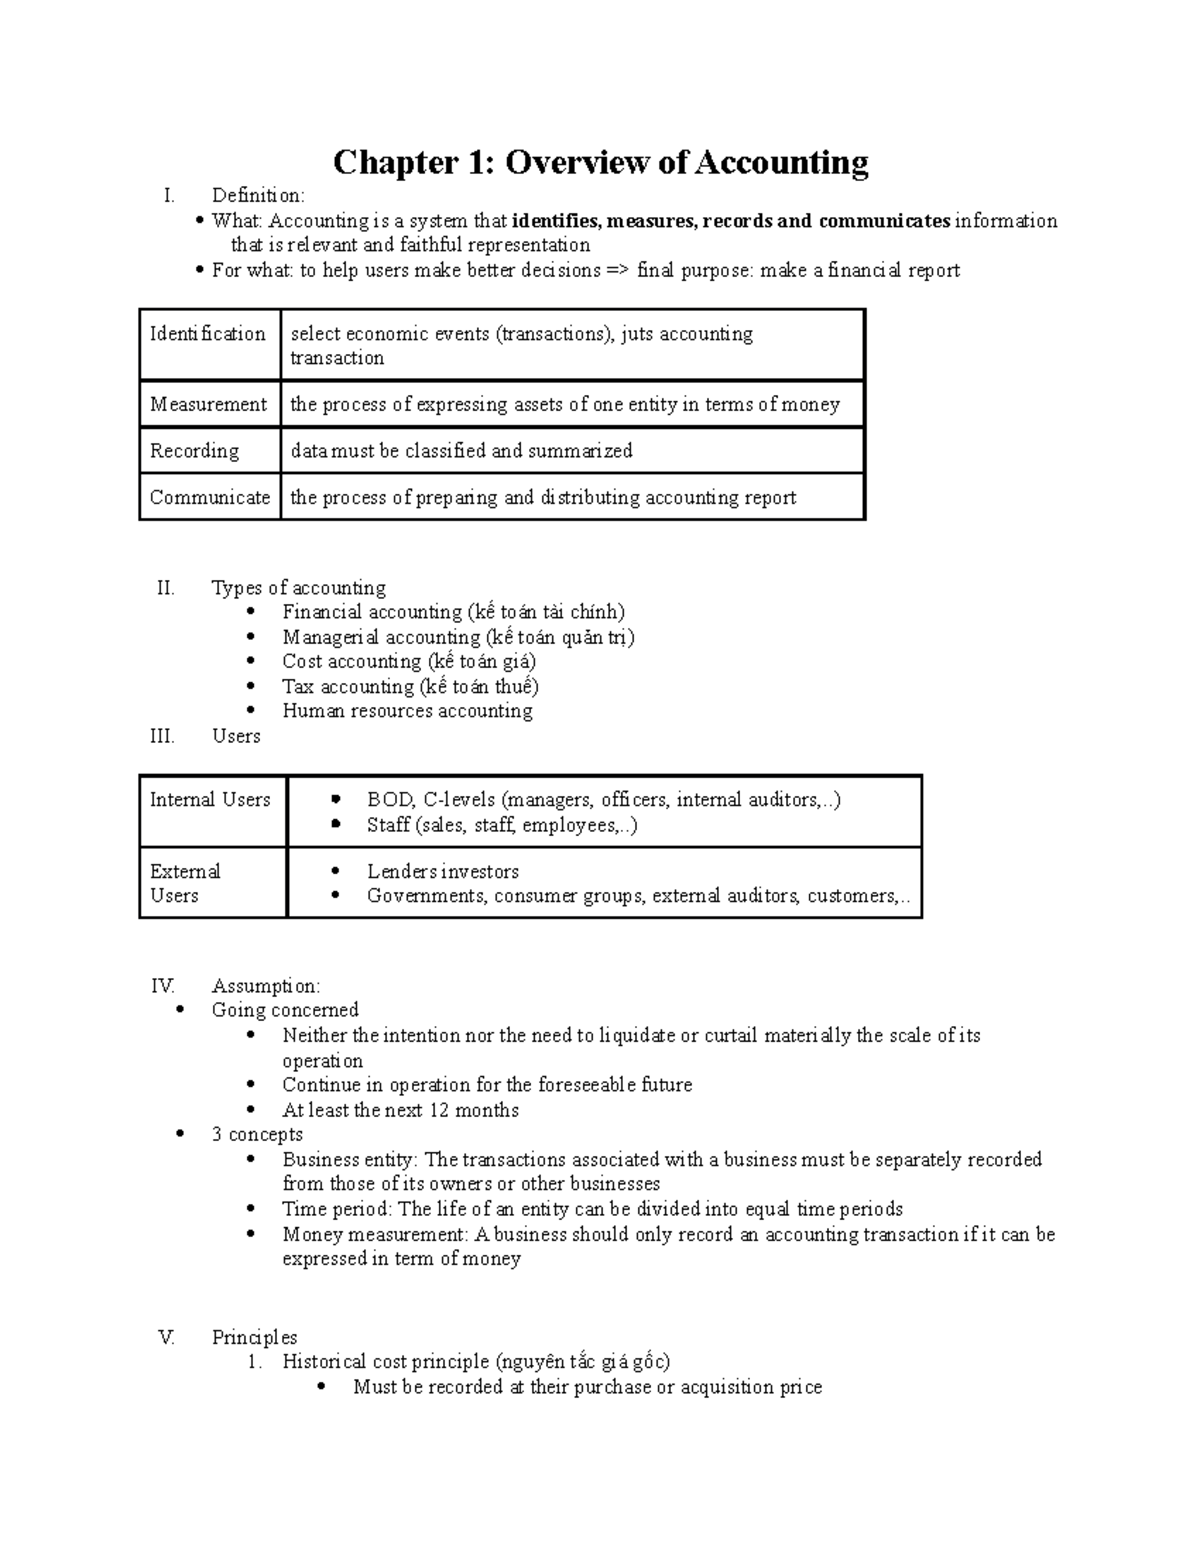
An accounting account is a structured container that tracks one specific category of financial activity over time. It has a number, a name, and a type. That is all. What makes it useful is that every transaction you post flows into exactly one or two accounts, and the sum of those flows tells you what happened to your money during a period. The five standard account types are assets, liabilities, equity, revenue, and expenses. Some systems add cost of goods sold and other sub-categories, but they are just children of those five. Every entry you ever make belongs to one of them. If you try to force a transaction into an account that does not match its nature, the financial statements will lie to you without saying anything out loud.
The Mechanics of Posting, Not the Theory
Posting is the part most people gloss over. You record a transaction by debiting one account and crediting another. The numbers move. The total stays balanced. That balance is what separates real accounting from a grocery list with math. Let me give you a practical example. You buy a printer for your office. It costs eight hundred dollars. The accountant in you wants to expense it immediately because it feels small. But if your capitalization policy is five hundred dollars and above, you have to capitalize it as a fixed asset instead. You debit Equipment for eight hundred and credit Cash for eight hundred. Then you depreciate it over three years using straight-line method. That is the full path from purchase to P&L impact. Skip the capitalization rule and your expense account is inflated in year one while year two through four show artificially low costs. The annual profit swings look like volatility when it is just a classification error. Another example that bites people constantly. You receive an invoice for legal fees totaling twelve thousand dollars but the work spans three months. If you post the full amount to one month, your P&L for that month looks terrible and the other two months look fine. The correct treatment is accrual: book four thousand per month across the three periods. Your balance sheet carries the remaining liability until the work is done or the period closes.
Get the Full Details

How to Build a Chart of Accounts That Does Not Collapse
I recommend starting with a template and deleting everything you do not need rather than building from scratch. QuickBooks, Xero, and Sage all ship with a chart of accounts. Import it into your system, then remove lines you will never use. Every unused account is noise. Noise creates confusion. Confusion leads to wrong postings. The numbering scheme matters more than most people admit. Use a logical structure. Assets from 1000 to 1999. Liabilities from 2000 to 2999. Equity from 3000 to 3999. Revenue from 4000 to 4999. Expenses from 5000 to 5999. Keep it simple. Avoid gaps larger than fifty between sub-categories because you will need them later. I have seen people create accounts numbered 1001, 1003, 1007, 1100 and then spend three hours trying to figure out where the missing numbers went. They never come back. Do not name accounts with slang or internal jargon. "Money in the till" and "Petty Cash Float" are two names for the same thing unless you know why they are different. Name accounts after what they represent, not after how your office talks about them. Future you will thank present you. Past you spent six weeks reconciling a mess that could have been avoided with better naming.
A Specific Problem I Ran Into and the Exact Workaround
During a forensic review for a nonprofit organization, I discovered that someone had been using a single expense account called "Program Services" for nearly twenty different transaction types. The account held rental payments, consultant invoices, software licenses, conference registrations, and shipping costs. The result was a single line item on the functional expense report that looked like one cost center when it was actually a graveyard of categories. The auditor flagged it immediately. The organization had to reconstruct eighteen months of transactions by pulling bank feeds, matching receipts, and manually recoding each entry. The workaround was brutal but straightforward. We created six sub-accounts under Program Services: rent, professional fees, software, travel, supplies, and other program costs. We then ran a date-range export of every transaction in the old account. Each line was recoded to the appropriate sub-account based on the vendor name and memo field. Vendors like "WeWork" and "Regus" became rent. Vendors like "Adobe" and "Zoom" became software. The process took about forty hours for eighteen months of data. The alternative was leaving the account as-is and risking a qualified opinion on the audit. I learned two things from that exercise. First, never let a single account absorb more than five to seven distinct transaction types. If it grows beyond that, split it. Second, write a one-page posting guide for every account. A posting guide states what belongs in the account, what does not, and what the approval threshold is. That document alone prevents about sixty percent of misclassifications before they happen.
Counter-Intuitive Truths Beginners Miss
Depreciation is not optional even for small purchases. Many small business owners expense everything below a certain dollar limit and move on. That works for tax purposes under Section 179 or bonus depreciation rules, but it distorts your internal financial statements. If you run a reporting system for management, capitalize assets above your materiality threshold and depreciate them. The P&L will reflect the true cost of doing business across the useful life of the asset. Revenue accounts should rarely be used for refunds. When a customer returns a product or cancels a service, do not credit the revenue account. Create a separate contra-revenue account called "Sales Returns and Allowances" and post there. Revenue gross of returns is what you earned. Contra-revenue shows what you gave back. Separating them gives you gross margin calculations that are actually meaningful. If you reverse revenue directly, your top line becomes a ghost that changes every time a refund occurs.

Where This System Breaks Down
The traditional chart of accounts fails when your business operates in multiple currencies and you do not have multi-currency support in your ledger. I worked with a freelance design studio that billed clients in USD, EUR, and GBP but tracked everything in USD. Exchange rate gains and losses ended up buried in a miscellaneous income account because the software did not auto-generate forex adjustments. The result was a balance sheet that showed a gain of twelve thousand dollars that was purely fictional. The fix was importing a monthly forex adjustment journal that pulled rates from OANDA and posted to a dedicated gain/loss account. It added thirty minutes of work per month and saved us from presenting fabricated profits to investors. The system also breaks down for service businesses with heavy project-based revenue tracking. A single revenue account cannot distinguish between recurring subscription revenue and one-time consulting fees if both flow through the same line item. The workaround is to use classes or departments alongside the chart of accounts. QuickBooks and Xero support this natively. If your system does not, you are working with a tool that is too small for the business. Upgrade early. Migration costs are lower than reclassification costs.
Practical Steps to Implement This Now
Start by listing every account in your current ledger and categorizing each one as active, inactive, or unused. Remove the unused accounts. Merge the inactive ones into a holding account that you close quarterly. Keep only active accounts. Audit the active list against your latest P&L and balance sheet. Any account showing a zero balance for more than two quarters should be flagged for review. Most of the time, it means no one is posting to it anymore. Next, define a posting guide for each active account. One page per account maximum. State the account number, name, type, and what transactions belong there. Add a line for common mistakes. "Do not post client refunds to revenue" or "Do not expense equipment above five hundred dollars." This guide becomes the reference document for anyone who touches the ledger, including you when you come back six months later and have forgotten why Account 5120 exists. Finally, reconcile every account at least monthly. Not quarterly. Monthly. A reconciliation takes between fifteen and forty-five minutes per account depending on volume. If an account takes longer than an hour, you have a posting problem, not a reconciliation problem. Fix the posting process, not the schedule. I have spent entire days reconciling accounts that should never have needed more than thirty minutes because someone was mixing personal and business transactions in the same account for six months straight.
If you want a downloadable template for a chart of accounts with posting guides built in, most accounting software vendors provide one in their help library. Intuit has a sample chart for QuickBooks. Xero has one for its platform. Download the template, strip it to your industry, and fill in the posting guides. It takes about two hours and prevents about six months of headaches later.